Morning Report: Republicans address problems with Dodd Frank 6/8/16

Markets are higher this morning on no real news. Bonds and MBS are flat

Mortgage applications rose 9% last week as purchases rose 11.7% and refis rose 7.4%. Interest rates were flat for most of the week until the jobs report on Friday, so these are good numbers, all things considered. The 10 year continues to bump to see resistance at the 1.7% level.

Job opening increased to 5.8 million in April, according to the JOLTS report, which matches a record set last July. Hires and quits fell however, which is another reason for the Fed to stand pat at the FOMC meeting next week.

Separately, a survey of CFOs indicates that companies are holding off hiring due to uncertainties regarding regulation and the general machinations in DC. Interestingly, hiring and retaining skilled labor came in as the #2 concern from #5 last year. That corroborates what the JOLTS report is saying: there are a lot of openings for skilled labor, but hirings are down because skilled labor is tough to find. On the other side of the coin, unskilled labor is becoming more expensive due to the recent spate of minimum wage hikes, which is creating an even bigger glut as companies substitute technology for labor.

Meanwhile in banking, machine learning continues to displace more and more workers. What can be automated ultimately will be.

Hillary Clinton won California and has enough delegates to sew up the nomination. Donald Trump continues on his mission to alienate as many people as possible. The big question is Bernie Sanders. Given the backdrop of the FBI investigation, he may decide to stick around until that is settled. That said, Obama has signalled that Hillary did nothing wrong, and I am sure his DOJ and his FBI has taken note. The Democratic establishment is going to put more and more pressure on Bernie to throw his support behind Hillary and unite to defeat Trump.

Was the big miss in payrolls just a spurious data point or is it the start of a downturn in the labor market?  Citi says to watch the initial jobless claims number tomorrow. Typically you should see a spike in initial jobless claims following such a weak number.

Republicans are drafting a bill to fix some of the issues with Dodd-Frank, particularly Volcker rule and some of the issues with the CFPB. Banks that meet capital requirements will be allowed to prop trade, and the CFPB will come under Congressional oversight and have a Board instead of a single director. There are two issues this is intended to fix. First, market making almost doesn’t exist any more as banks are afraid to venture too close to proprietary trading and the Volcker rule. The next crash (and there will be one) investors will be in for a rude awakening when they cannot sell their less liquid stocks because there is no bid. It will be even worse for bonds, and could be a major issue for ETFs. The second issue is the CFPB, which is regulating by enforcement action. Consumer advocates are getting sick and tired of tight credit, which is creating some consternation with other members of the left who still think the banks are unregulated and need to be reined in. Elizabeth Warren is leading the charge against this, which makes sense since the CFPB is her baby.

Morning Report: ADP jobs report comes in line with expectations 6/2/16

Markets are lower this morning as ECB President Mario Draghi speaks. Bonds and MBS are flat.

The ECB will now start buying corporate bonds in an attempt to stimulate their economies. Truly an amazing time we live in.

We get some labor market data this morning, before the big jobs report tomorrow.

The ADP Employment Change report came bang in line with expectations at 173k jobs created. Tomorrow’s non-farm payroll expectation is for an increase of 160k jobs created in May. Small business led the way, adding 76k employees. Professional and business services increased the most. Manufacturing jobs fell.

Note that tomorrow’s payrolls number could be affected by the Verizon strike. Regardless. the number to focus on tomorrow is the change in average hourly earnings.

Job cuts fell to a 5 month low, according to outplacement firm Challenger, Gray and Christmas. Announced job cuts came in at just over 30k, a drop of about 50% from April. The two biggest industries in job cuts – energy and finance – appear to be slowing down the pace of headcount reduction.

Initial Jobless Claims came in at 267k last week,

Homebuilder Hovnanian reported second quarter earnings this morning. Deliveries were up 31% and revenues were up 40%. Earnings were still below expectations. The stock is down this morning

US auto sales fell in May, which is usually one of the stronger months for auto sales. Auto sales had been increasing for 6 years, pushed by a stronger economy and ridiculously cheap financing. Yield pigs may find that doing 8 year auto loans at 3.5% is a dumb trade.

Despite being disappointed by the current crop of presidential candidates, consumers still plan to buy cars and houses. Despite all the rhetoric, the economy is not doing all that badly, and there is tremendous pent-up demand for housing, especially from younger buyers. The issue for them is affordability, and tight inventory combined with a lack of building is making it hard.

Here is a new one in the world of apartment leasing: Like our facebook page, or else.

The House included language in the 2017 budget to bring Congressional oversight to the CFPB and subject it to the appropriations process. Currently, it is funded by the Fed, who really has no choice but to give them what they want. Second, the provision would replace the single director with a five-member board appointed by the President. While this is going nowhere (we haven’t had a budget since early in Obama’s Presidency), it will be fodder for the fall elections. For the moment, it appears the CFPB is directing its attention to payday lenders.

Morning Report: Don’t fear another real estate bubble 6/1/16

Markets are lower this morning on overseas weakness. Bonds and MBS are up.

Mortgage Applications fell 4.1% last week as purchases fell 4.7% and refis fell 3.9%. Refis ticked up to 54.3% of the total number of loans.

The ISM Manufacturing report came in better than expected, indicating that the manufacturing economy is expanding, albeit modestly. The ISM services number is much more important, as manufacturing only represents 15% of the economy. It looks like the exporters are getting hit harder than those who mainly focus domestically. Employment was flat month-over-month, however it is in a contracting trend.

Construction spending fell 1.8% month-over month, however the previous 0.3% print was revised upward to 1.5%. Residential construction fell 1.5% month-over-month, however it is up 8% YOY.

As we saw from the FHFA House Price index, home prices have recouped their losses from the bubble years. Is it time to start worrying about a new housing bubble? Freddie Mac takes a look at real estate prices relative to incomes, credit scores, inventory, and leverage in the system and concludes that it is not yet time to worry. While house prices are indeed stretched relative to incomes, that figure ignores the effect of interest rates. The overall credit profile for new originations has been strong since the crisis, and while we are beginning to see some credit deterioration in the oil states, it is nothing like 2007-2008. Tight inventory remains a huge issue in terms of pricing, and notwithstanding last week’s 617k print on new home sales, new construction is still well below historical levels. Consumers are increasing mortgage debt, however they seem to be using the cash-out refi to pay down credit card debt instead off funding consumption. The froth in the housing market still remains concentrated in the big coastal urban areas like San Francisco and Manhattan, which is driven by foreign demand.

At the end of the day, bubbles are psychological phenomenons, where investors and lenders both believe an asset is “special” and cannot go down in price. We will probably never see another real estate bubble, but our grandkids might. If anything, the bubble is in sovereign debt, and people will wonder why investors chose to tie up their money for 10 years for negative returns. Purchasing a German Bund yielding 13 basis points over 10 years is in the same category as buying a new construction McMansion in Stockton CA circa 2006 or paying $76 a share for E Toys the day of its $20 IPO in 1999.

Auto sales are coming in this morning, and it looks like they are coming in weaker than expected.

Interesting editorial by Clintonite Doug Schoen who says Hillary might not be the Democratic Party nominee. There is talk in the Democratic party about a white knight candidate, like Joe Biden or John Kerry who could enter the race at the convention, and select someone like Elizabeth Warren to be VP.

Morning Report: Incomes and spending rise 5/31/16

Markets are up this morning after Chinese stocks rallied overnight. Bonds and MBS are down.

The second revision to first quarter GDP came in at 0.8%, slightly below the Street estimate of 0.9%. This was an upward revision from the initial 0.5% estimate.

Personal incomes rose 0.4% in April, in line with expectations. Personal spending rose 1%, which topped the 0.7% estimate. The personal consumption expenditures index (which is the inflation measure preferred by the Fed) rose 0.2% month-over-month and is up 1.6% annualized. We are seeing some sell-side firms take up their second quarter GDP estimates on this number.

Home prices rose 0.9% MOM and 5.4% YOY, according to the Case-Shiller Home Price Index. This was slightly ahead of estimates. An improving labor market along with tight inventory is driving prices higher.

In other economic data, both the Chicago Purchasing manager index and the consumer confidence index fell.

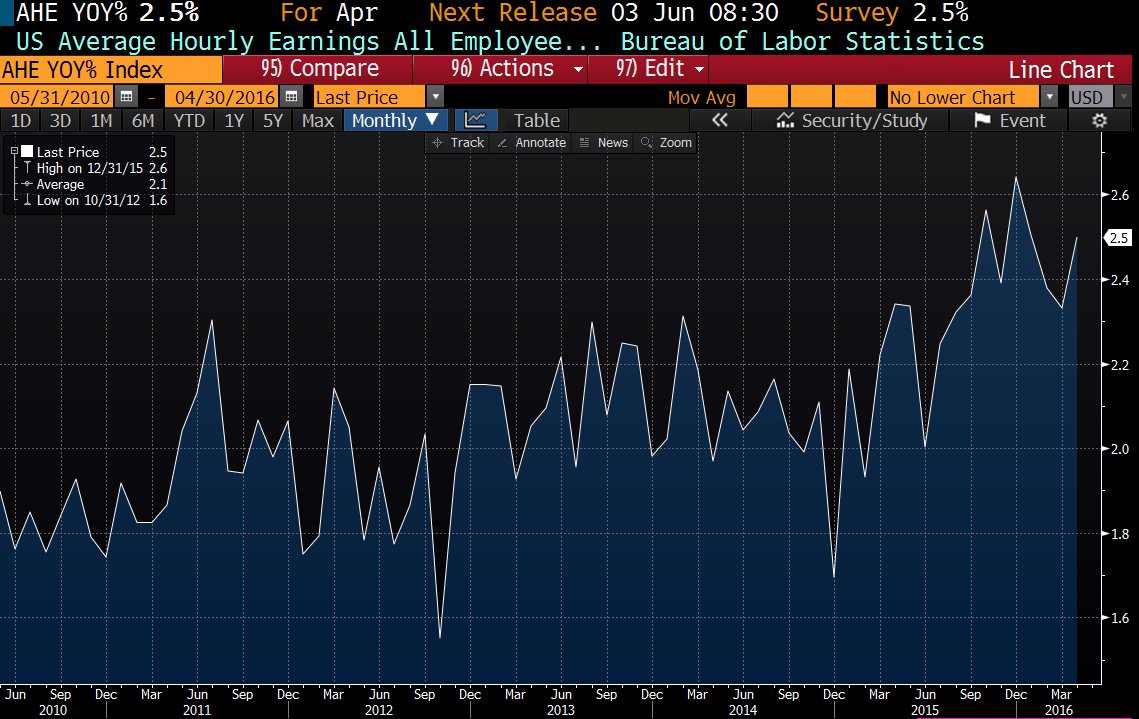
The highlight of this short week will be the jobs report on Friday, which will be the last big data point before the FOMC meeting in a couple of weeks. The number to watch: average hourly earnings. Average hourly earnings growth has been accelerating over the past 6 months or so, to around 2.5%. You can see the trend in average hourly earnings growth in the chart below:

On Friday, Janet Yellen hinted that the next rate hike is probably at the June or July FOMC meetings.

Misunderestimating Donald Trump 5/27/16

I feel like Donald Trump has a good chance of winning the Whitehouse for two major reasons: his populism (a novel campaign strategy in this day and age), and the Democrats’ and the left’s lack of understanding as to what his appeal actually is (arguably, this is why his Republican opponents in the primaries lost, as well).

From the Plum Line this morning:

Donald Trump just made an extremely important promise. It’s one of his worst yet.

Believe it or not, Donald Trump has now made a very important policy statement. Introducing what he billed as an “energy plan,” Trump promised to “cancel the Paris Climate Plan.” Unlike so much of what comes from Trump on policy, this is a genuinely clarifying moment, with potentially enormous long-term implications.

Of course, Greg Sargent thinks this is an awful idea, one that dooms any hope Donald had of being president, if in no small part because it means Bernie and Hillary will totally definitely team up to stop Trump now, and that’s all it will take: Bernie and Hillary teaming up. The part where cancelling the Paris Climate Accords actually appeals to a lot of people, and increasing domestic energy production appeals to even more . . . that doesn’t seem to enter into it.

I think that’s just wrong. And the more the Democrats allow themselves to be painted as (or paint themselves as) the side where “it’s sad domestic energy production is losing all those jobs, but, eh, what can you do?” versus Trump’s promise of increasing domestic energy sector jobs and production (never mind the specifics, it’s magic!), the more I think they are mistaking what makes the difference between victory and defeat in November.

I also think it’s interesting that, for Greg Sargent, the significant thing about Trump’s “energy plan” (so-called) is how it will impact the Hillary/Sanders dustup. That’s the take away. Not that Trump’s own dismissal of climate change as an apocalyptic inevitability might actual appeal to Independents or swing-voters, not to mention his promise of supporting domestic energy production.

I don’t think Anthropogenic Climate Change is a big winner for the Democrats. Independents and Republicans can be peeled away by lots of things, such as talk of jobs (green energy jobs!) or ending of perpetual military engagement or promises of financial benefits to the middle class, but I think the prioritization of Climate Change as the Most Important Thing Ever is not the political talisman many seem to think it is. And Donald saying he’s going to pull America out of the Paris Climate Accords (pretty much just posturing bullhockey anyway, good for politicians to preen over and little else) is not going to send shockwaves and fear and disgust through the American electorate.

And it’s just one way they seem to be misunderestimating The Donald.

Morning Report: Home prices continue to rise 5/25/16

Stocks are higher this morning as emerging markets rally. Bonds and MBS are down.

Mortgage Applications rose 2.3% last week as purchases rose 4.8% and refis rose 0.4%. The average 30 year fixed rate mortgage rose 3 basis points to 3.85%. The average jumbo rate increased 8 basis points to 3.82%.

Home prices rose 0.7% in March, according to the FHFA House Price Index. “While the overall appreciation rate was robust in the first quarter, home price appreciation was somewhat less widespread than in recent quarters,” said FHFA Supervisory Economist Andrew Leventis. “Twelve states and the District of Columbia saw price declines in the quarter—the most areas to see price depreciation since the fourth quarter of 2013. Although most declines were modest, such declines are notable given the pervasive and extraordinary appreciation we have been observing for many years.” Interesting to see prices begin to decline in some states.

A US appeals court threw out the $1.27 billion judgement against Bank of America for Countrywide’s sins related to the “hustle.” The 2nd U.S. Circuit Court of Appeals in New York said the proof at trial was insufficient under federal fraud statutes to establish liability. No comment yet from Manhattan U.S. Attorney Preet Bharara.

Hillary Clinton is trying to take Donald Trump to task over comments made as the real estate bubble was bursting. Not sure how much traction that is going to get, however she had a conference call with reporters to push the message. Separately, the Republican party is beginning to unite behind Trump.

Morning Report: Home prices continue to rise

Stocks are higher this morning as emerging markets rally. Bonds and MBS are down.

Mortgage Applications rose 2.3% last week as purchases rose 4.8% and refis rose 0.4%. The average 30 year fixed rate mortgage rose 3 basis points to 3.85%. The average jumbo rate increased 8 basis points to 3.82%.

Home prices rose 0.7% in March, according to the FHFA House Price Index. “While the overall appreciation rate was robust in the first quarter, home price appreciation was somewhat less widespread than in recent quarters,” said FHFA Supervisory Economist Andrew Leventis. “Twelve states and the District of Columbia saw price declines in the quarter—the most areas to see price depreciation since the fourth quarter of 2013. Although most declines were modest, such declines are notable given the pervasive and extraordinary appreciation we have been observing for many years.” Interesting to see prices begin to decline in some states.

A US appeals court threw out the $1.27 billion judgement against Bank of America for Countrywide’s sins related to the “hustle.” The 2nd U.S. Circuit Court of Appeals in New York said the proof at trial was insufficient under federal fraud statutes to establish liability. No comment yet from Manhattan U.S. Attorney Preet Bharara.

Hillary Clinton is trying to take Donald Trump to task over comments made as the real estate bubble was bursting. Not sure how much traction that is going to get, however she had a conference call with reporters to push the message. Separately, the Republican party is beginning to unite behind Trump.

Morning Report: New home sales spike 5/24/16

Markets are higher this morning on no real news. Bonds and MBS are down.

New Home Sales came in much stronger than expected, at an annual rate of 619,000. This is the highest level since early 2008. While it is premature to bust out the champagne quite yet (prior to the bubble, the last time sales were this low was the early 90s), it is an encouraging sign. The Spring Selling season got off to a somewhat slow start, but seems to be picking up momentum. Note this number has an unusually wide margin for error this month, so expect a revision.

Speaking of new home sales, we got second quarter numbers out of Toll Brothers this morning. Earnings beat on the top and bottom lines, with revenues increasing 31% in dollars and 9% in units. Interestingly, average selling prices of signed contracts were flat. Contracts only rose 3%, and the problems were in California, with not enough inventory for sale. They continue to build out their urban apartment segment and plan to expand it to smaller cities and suburbs.

The Richmond Fed manufacturing index fell in May to -1 from 14.

More millennials are living with their parents than they are with a partner or significant other, for the first time in the modern era. This is probably a reflection of a lot of things – from the weak economy to people getting married later in life. However, it does represent pent-up demand for housing.

Foreclosure starts fell to 58,700 in April, the lowest level since 2006. Delinquencies increased slightly, but are still down 10% YOY. The active foreclosure inventory fell below 600,000 for the first time since 2007. The Northeast still has some wood to chop in terms of liquidating foreclosures.

Morning Report: Lending Club is tarnishing the rest of the fintech industry 5/23/16

Markets are flattish this morning on no real news. Bonds and MBS are flat as well

Not a lot of data this week – the biggest number will be the second revision to first quarter GDP later this week. The Street is forecasting GDP rose 0.9%. We will also get pending home sales and new home sales.

Pain in the junk bond market is spreading to the non-commodity space as retailers are beginning to take it on the chin.  This is one issue that could certainly cause the Fed to maintain low interest rates. Pain here is generally considered bond bullish as well, which means it is a catalyst for lower mortgage rates.

Mohammed El–Erian says that the markets are still not fully pricing in two more hikes this year. He believes the Fed has a small window in which to pursue normalization and they intend to take advantage of it.

Lending Club’s woes are putting a wet blanket on the rest of the fintech industry. The industry is going from playing offense in Washington to playing defense. The regulators are hungry to bring this industry to heel.

Morning Report: The Fed has a credibility problem 5/20/16

Stocks are up this morning as commodities rally. Bonds and MBS are slightly lower

Existing Home Sales rose to an annualized pace of 5.45 million in April, according to the NAR. The median home price rose to $232,500, an increase of 6.3% YOY. Total inventory is 2.14 million homes, which represents a 4.7 month supply at the current pace.

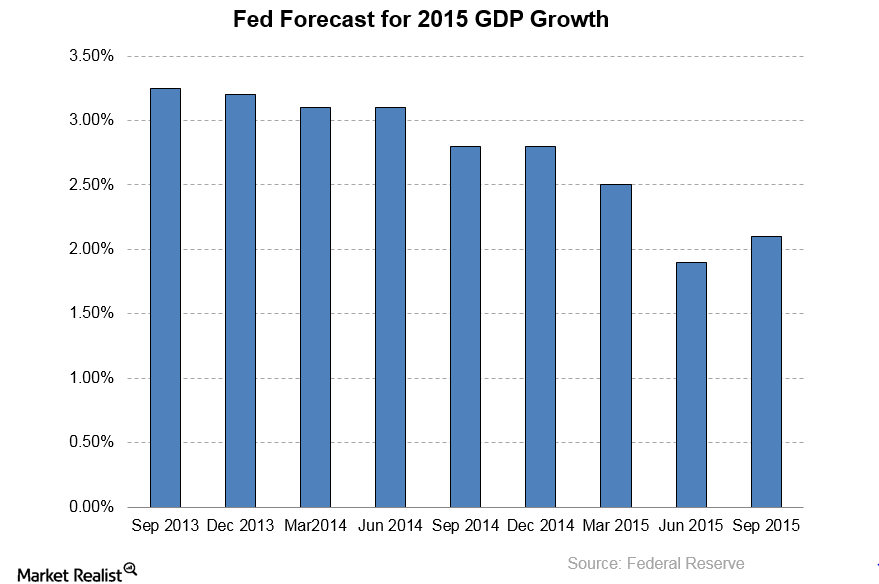
One of the Fed’s problems right now is credibility. As the minutes from Wednesday showed, the markets have been relatively complacent about the possibility of a Fed move. Part of that is certainly the Fed’s own doing, as they have tried to prep the markets for a rate hike several times over the past year or so, only to decide that the economy isn’t strong enough to withstand a rate hike. Here is the problem:

This is what the Fed’s forecast for 2015 GDP growth at all of the FOMC meetings starting in September 2013. As you can see, the Fed has been consistently high in its forecast for GDP growth. So, they begin to prep the markets for a rate hike based on their forecast that GDP will improve to a 3%+ rate of growth, and then back off when we start getting real numbers. I suspect the reason is because the Fed’s models are based on the garden-variety business cycle, where inventory build drives the process. We are in the aftermath of an asset bubble, and the problem here isn’t excess inventory – it is excess debt. And aside from the 1930s and Japan’s current experience, we don’t have a lot of experience with it.

Everyone knows auto loans are the new subprime, as low interest rates have pushed investors into riskier and riskier paper. Eight year car loans with rates around the current mortgage rate are common now. The other new issue: negative equity.

Separately, the CFPB is going after auto title loans as well as payday lenders. Is the government basically setting the stage such that the unbanked have nowhere to go to get credit? Many would like to see the post office become a bank.