Morning Report: Lennar’s take on the housing market 6/22/16

Markets are flattish ahead of the Brexit vote tomorrow. Bonds and MBS are down small.

Mortgage Applications rose 2.9% last week as purchases fell 2.4% and refis rose 6.5%. Refis rose to 57.7% of all loans as rates bombed out on the FOMC decision.

The FHFA House Price index rose 0.2% in April, and is up 5.9% year-over-year. Interestingly, New England went from cellar-dweller to the leader in monthly price appreciation. The region is still lagging the most on a YOY basis however. The FHFA index is the only housing price index that has regained all of the losses from the crisis. This is because it concentrates only on houses with a conforming mortgage, so it ignores the all-cash distressed sales and the jumbo space.

Existing home sales rose 1.8% in May to 5.53 million. This is the highest pace since February 2007. The median house price was $239,700 up 4.7% YOY. Total housing inventory is at 2.15 million units, which represents a 4.7 month supply. Inventory is still tight. The first time homebuyer accounted for 30% of all sales, a decrease from last month and last year. Days on market dropped to 32 days, a record.

On Lennar’s earnings conference call, CEO Stuart Miller summed up Lennar’s view of the housing market. In a way, he also explained why housing starts remain so low. “As we’ve noted consistently over the past years, the overall housing market has been generally defined by a rather large production deficit that has continued to grow over the past years. While questions have been raised as to the real normalized levels of production that are required to serve the U.S. current population, we believe that production levels in the 1 million to 1.2 million starts per year range are still too low for the needs of American household growth that is now normalizing.While measuring current production levels against historical norms of 1.5 million starts per year might be flawed logic as there may be a new normal, we believe that the very low inventory levels in existing and new homes and the low vacancy rates and high and growing rental rates for apartments indicate that we are in short supply nationally.

The idea of a “new normal” being somewhere above current production levels (1.2 million units) and the historical average (1.5 million units) is as good an explanation as any. Lennar mentioned on their call that they have been transitioning from the early growth phase of the cycle to the mature phase of the cycle. In other words, they aren’t looking for the typical 2 million level of starts you usually see in the recovery from a recession. They do give a good graphic analysis of the supply / demand state of the housing market in this slide from a recent JP Morgan housing conference.

Notice that the current level of production (sub 1.2 million units is closer to the the “housing depression” line than the “normal production” line. That would make 2009-2012 “nuclear winter.” Lennar is making the same bet a lot of other builders are making that multi-fam is the way to go as they see the Millennials happy to rent. Actually, the meta-bet they (and everyone else in the financial markets) are making is that inflation is gone, dead, buried, and never, ever, ever coming back. The only reason why you would lend money to the government for no return is that you think inflation is gone. It truly is a “this time is different” argument, which is the most dangerous argument in all of investing. Especially when every central bank on the planet is on a mission to create inflation. Inflation is a debtor’s best friend, and if the Millennials can get out from under their student loan debt, we should see a bull rush for new SFR housing. The cautious homebuilders will probably be caught with too little inventory, and will suddenly start bidding against each other for workers, land and materials. And that is how recessions end.

KB Home also reported earnings last night. Earnings were better than expected, and they see a return of the first time homebuyer. Note that the current number of first time homebuyers (30%) is well below the historical average of 40%. Average selling prices were up 2%, which is much lower than the other builders.

Morning Report: Janet Yellen gets more dovish 6/21/16

Markets are up this morning as the market frets about Brexit and Janet Yellen speaks. Bonds and MBS are up small.

The latest polls for Brexit are mixed, and the bottom line is that it is too close to call. If the UK leaves the EU, the most likely effect will be a flight to safety, which would mean global flows to US Treasuries, lowering rates. Some of the forecasts I am seeing would be a sub 1.4% on the 10 year if the UK leaves, or a return to the old 1.7% – 1.9% range if they stay. FWIW, spread betting is common in the UK, and the markets there are much deeper than the political betting sites in the US. Right now, the spread betting markets are assigning a 25% probability of Brexit.

Janet Yellen adjusted her language to be slightly more dovish ahead of her testimony today in front of the Senate Banking Committee. She is exhibiting a little more uncertainty over whether the economy is ready to return to moderate growth. Not sure what changed in the last week or so, but there you go.

Homebuilder Lennar beat estimate this morning as the housing market continues to improve and wage growth begins to appear. Interestingly, they are pulling back a little from the market, it appears: “As this year’s spring selling season improved over last year, our second quarter new orders increased 10% to 7,962 homes year-over-year, while our home deliveries and home sales revenue also increased to 6,724 homes and $2.4 billion, respectively.  As the recovery has continued to mature, we have remained focused on our strategy of moderating our growth rate in community count and home sales, as well as on our soft-pivot land strategy, targeting land acquisitions with a shorter average life.” For some reason, the builders don’t seem to trust this recovery in housing.

Perhaps Lennar’s reticence comes from the attitudes of consumers. A recent survey shows housing affordability remains a big problem. That said, perceptions of real estate as a good long-term investment are improving. They should, since rental inflation is generally outpacing house price appreciation and the buy-rent decision is skewed heavily towards buying. That said, consumers are becoming more pessimistic that the housing crisis is over.

Good breakdown on how big of a boost homebuilding is for the economy. Unfortunately, the only discussion of housing in DC revolves around how hard we should be slugging the banks.

Basketball Report

This post was inspired by this Tristan Thompson (TT) hype from ESPN:

http://espn.go.com/blog/statsinfo/post/_/id/120082/tristan-thompson-the-real-mvp

That was the University of Texas connection to the stunning NBA Finals, and our TT’s play was in fact magnificent. Even his little midrange jumper in traffic seemed to float in again and again, and there was no denying his timing, his hustle, his D, and his connection to LeBron James.

But there was also no denying who was the MVP. LeBron James is the only  player ever who could play PG, PF, and defensive rim protector on the same sequence of plays. The man would be competitive with the best at every single position on the floor. In leading his team to a come back three consecutive wins he often eschewed scoring for finding the open man – as he did with Thompson on several memorable plays. On defense, he was the superb rim protector, the thief, and that spectacular late game block on Iguodala’s easy fast break lay up – just how fast can LBJ run the 40? -was one for the ages. Having a terrific shooting guard in Irving opened the floor for him, of course, and it meant that LeBron had to be played one-on-one. But Golden State is an excellent one-on-one defensive team; perhaps that was as crucial to their great regular season total as their extraordinary shooting.

Golden State’s game is Spurs 2014 taken to a different level because the requirement to guard three shooters 25′ or more from the basket opens passing lanes and driving lanes as nothing else. This is a type of game engineered for the reincarnation of Larry Bird. The combination of three great shooters, one agile rim protector who can score when needed, and a slasher/defensive stopper will be the model now that many will try to emulate. If the slasher/defensive stopper is LeBron, or Kawhi, or the second coming of MJ, all the better.

Tristan Thompson is a becoming one model for the agile rim protector in the three out offense. Surely Olajuwon would have been great in this offense, but we will never know. The agile rim protector must be aware of his shooters and get the ball out to them on offense, when he is not wide open underneath or when early in the possession, usually looking to score as the last option and on set plays. This is because three points are cumulatively much better than two per possession. So while Cleveland cannot yet match Golden State from three, and while the Cavs depended on stellar performances from Irving and Thompson and an overwhelming effort from LeBron, I think with one additional sharpshooter they would become nearly unbeatable.

It is to me interesting that in the three point era there have been some teams prior to GSW that could have played like them. I think, particularly, that Stockton-Hornacek averaged nearly 50% from trey some seasons, but did not shoot nearly as often as the Splash Brothers. I am guessing that trusting the three as a staple in the arsenal just took a long time to happen, or it took an assemblage of three sharpshooters at once.

It was a great series. And TT is also terrific in that commercial making fun of old Kobe.

Morning Report: Housing starts flat in May 6/17/16

Markets are flattish on no real news. Bonds and MBS are flat as well.

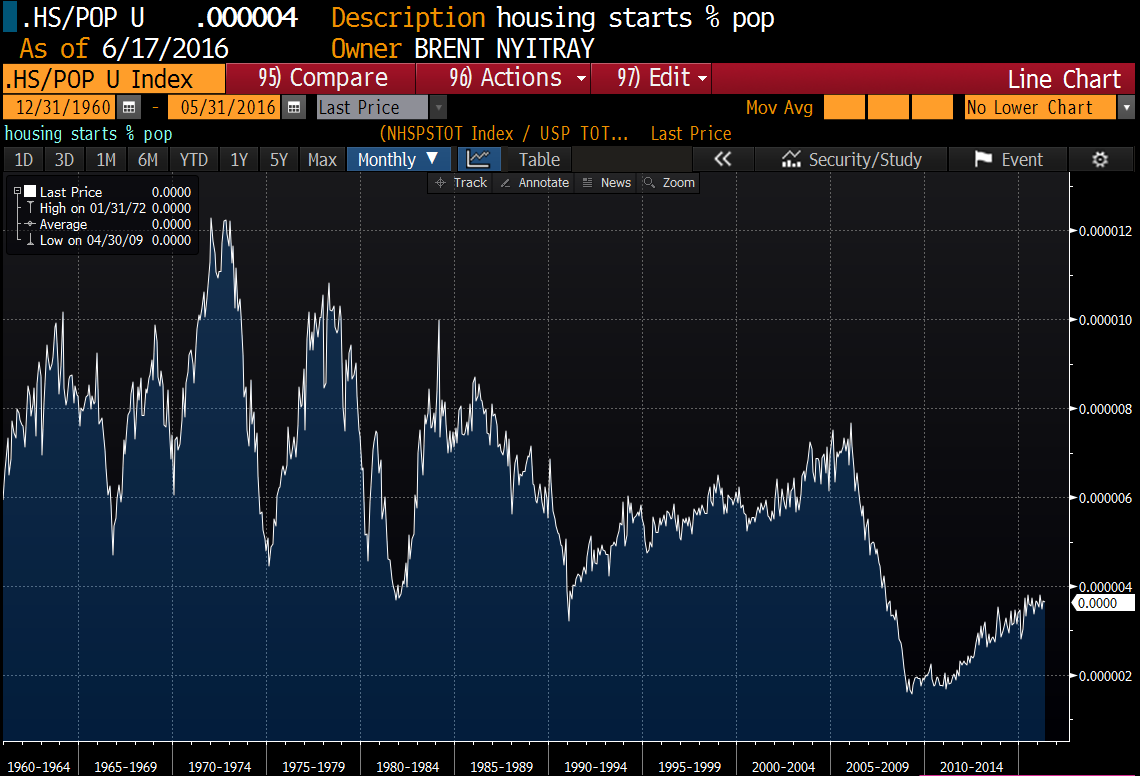
Housing starts came in at 1.16 million in May, a tiny decline from the downward-revised April number. Building Permits rose slightly. Starts rose the most in the West and fell the most in the Northeast. It is amazing that we have a shortage of housing and are building very little. Take a look at the chart below: It is housing starts divided by population. We have just barely touched the low from the 91-92 recession, which also was the result of a frothy real estate market. If the government wants to get the economy going, it should be asking the question why housing is still so depressed in the face of such tight inventory and high demand.

The Brexit campaign is on hold after a member of Parliament was murdered yesterday. Officials don’t have a motive, however there have been calls on both sides to tone down the rhetoric.

The current global economy resembles the 1930s in many ways, and can help explain why the Fed is going so slowly in raising interest rates. Of course there are major differences as well – rates didn’t go negative in the 1930s, the world was on the gold standard, and capital was much less mobile. Still, we have a recession in the aftermath of an asset bubble and the hangover is debt that needs to be worked down. The Fed is trying to avoid the mistake of the 1937 “depression within the depression” where they hiked rates too quickly. Of course by that time, FDR was on an anti-business tear with the undistributed profits tax, and that certainly put a wet blanket on business investment.

The most deadly words in investing are “this time is different.” That said, we are in a world of negative bond yields, and massive central bank balance sheet growth, which you won’t find in your Econ 101 textbook. This time is indeed different. Or, is the answer more simple: we are in a bubble for sovereign debt? When you are purchasing a German Bund for no yield whatsoever, the only reason why you would make that investment is because you anticipate a capital gain – in other words you are making the investment on the “greater fool” theory. Which is of course no different from paying 60x earnings for Cisco Systems in 1999 hoping to flip it to someone willing to pay 61x earnings. Or flipping condos in Palm Beach for that matter.

I went on Louis Amaya’s Capital Markets Today podcast after the Fed decision and discussed the Fed, the economy, housing and regulations. You can hear the podcast here.

Morning Report: The Fed acknowledges reality in the bond market 6/16/16

Markets are lower this morning on overseas weakness. Bonds and MBS are flat

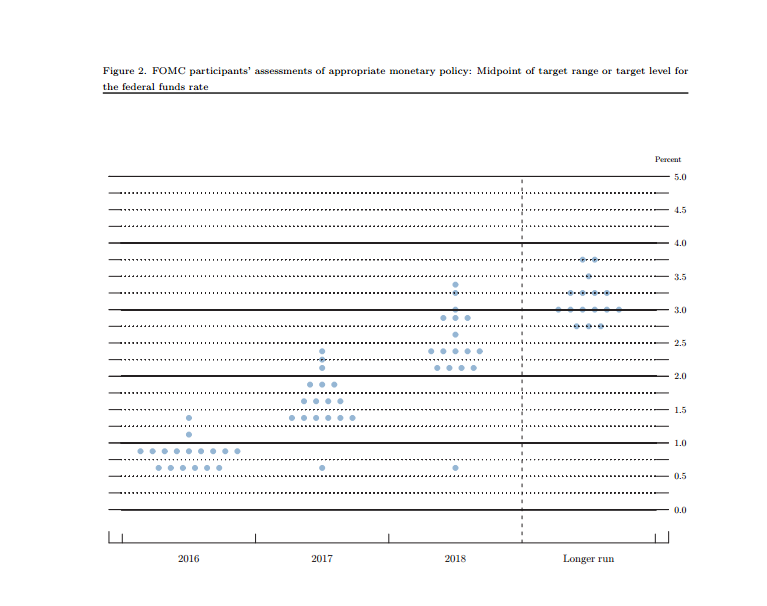
The Fed left interest rates unchanged yesterday, and the biggest data point was the dot graph which showed 6 members expect no change in interest rates this year. That sent the 10 year yield down 4 basis points and the 2 year down 5. The actual language of the statement wasn’t dramatically different from April. They released new economic forecasts, taking down their estimate for 2016 and 2017 GDP to 2%, and increasing their estimate of 2016 inflation from 1.2% to 1.4%. In the press conference afterward, Janet Yellen acknowledged the upcoming vote in the UK (Brexit) was also a factor. The big admission was that rates will remain lower for longer.

The Fed Funds futures market is now discounting a single-digit chance of a rate hike in July, and the futures are predicting less than a 50% chance of a move throughout the rest of the year.

Bond yields are falling worldwide, with the German Bund trading at -2.3 basis points, the Swiss 10 year at -51 basis points, and the Japanese government bond yield at -20 basis points. Like it or not, the US 10 year probably won’t be able to escape the low rate vortex in the rest of the world, as investors swap out negative-yielding assets and buy Treasuries. Not saying we are going to go negative, but I find it hard to see where the selling pressure is going to come from. Are we going to be positioned for another refi boom? Don’t rule it out.

The other potential beneficiary of low rates worldwide should be mortgage backed securities, especially GN securities which are guaranteed by the government. I would have to imagine overseas investors will find these appetizing at some point. GN and FN TBAs have lagged the movement in Treasuries so far this month. This should translate into better conforming and government pricing going forward, even if bonds take a breather.

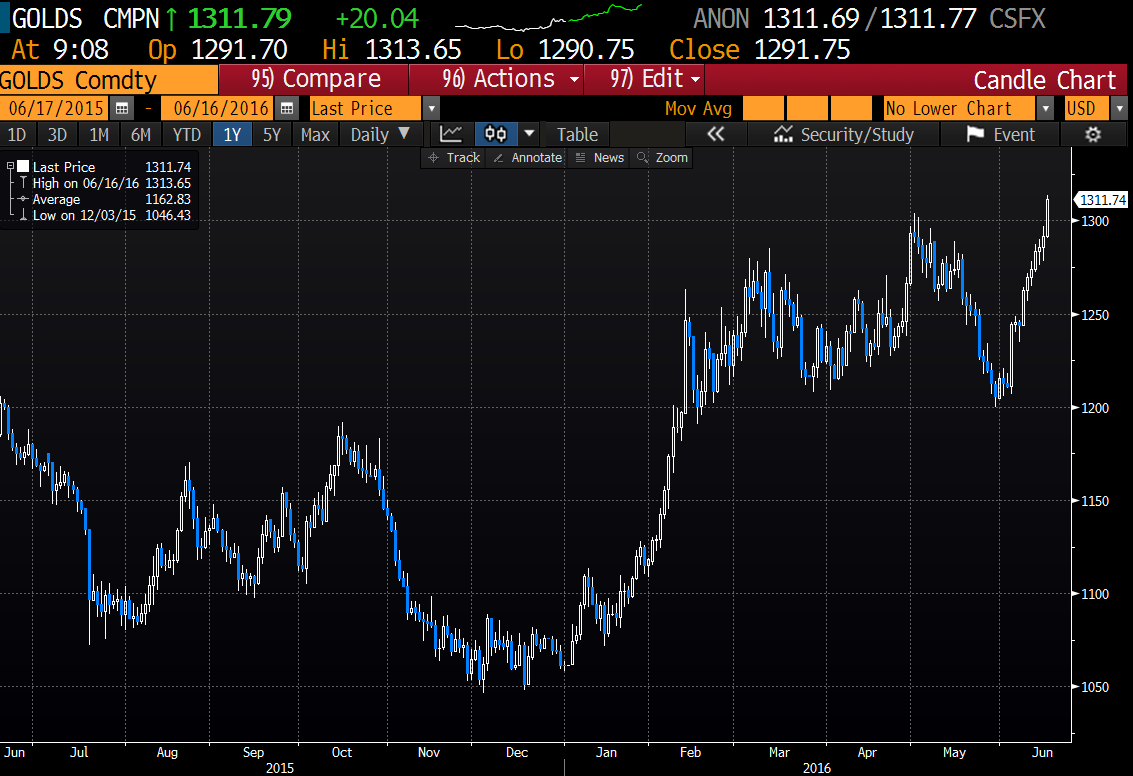
The other beneficiary of negative interest rates? Gold, which has been on a tear lately. The knock on gold has always been that it has no yield. No yield is better than negative yields, and gold has upside, while there probably isn’t much upside in a government bond with a negative yield. A rule of thumb for gold has always been that an ounce of gold should buy a high quality men’s suit.

Initial Jobless Claims rose to 277k last week from 264k the week before. While it looks like payroll growth is slowing, we aren’t yet seeing evidence of layoffs. As a rule of thumb, a sub-300k initial jobless print is a sign of strength in the labor market.

The consumer price index rose 0.2% in May, and is up 1% YOY. Ex-food and energy, it is up 2.2%. Note the Fed doesn’t use the CPI, it uses the PCE.

Real average weekly earnings rose 1.1%.

Purchase loans are the majority of new originations despite the rally in bonds, according to Ellie Mae’s Origination Insight Report. Purchases accounted for 62% of all loans. Days to close increased a day to 45 days and average FICO increased a point to 724.

Morning Report: Awaiting the Fed 6/15/16

Stocks are higher this morning as we await the FOMC decision at 2:00 pm today. Bonds and MBS are flat.

Bonds had a sensational rally yesterday, with the 10 year yield falling to 1.57% and the German Bund going negative before giving it all back. The Bund is basically at zero this morning.

The FOMC decision is due out at 2:00 pm EST today. No one is expecting a rate increase, but we the press release and press conference might have some market-moving news. We will also get new a new Fed Funds dot graph and updated forecasts for inflation, unemployment, and GDP growth. Here is a primer on what to look for.

Mortgage Applications fell 2.4% last week as purchases fell 4.9% and refis fell 0.7%. Refis accounted for 55% of the total number of loans.

Inflation remains in check at the wholesale level, as the producer price index rose 0.4% MOM and fell 0.1% YOY. Ex food and energy, the PPI was up 1.2%, much lower than the Fed’s 2% target rate.

Paul Singer of Elliott discusses central banks and how all of their policies have been slowing growth and exacerbating inequality. He is bearish on stocks, bullish on gold. Separately, Jeffrrey Gundlach of DoubleLine says that central bankers are losing control.

Completed foreclosures ticked up to 37,000 in April from 36,000 a month ago, however they are down 16% YOY. The foreclosure inventory is just over 400,000 homes, which works out to be 1.1% of all homes with a mortgage. This number is down 23.4% from a year ago. Foreclosure inventory remains concentrated in the Northeast, Florida, and the sand states.

iServe got a nice mention in Rob Chrisman’s blog this morning. If you want to learn more about VA loans, we conduct seminars all over the US with our VA expert. We serve those that served.

In other economic news, the New York State Empire Manufacturing Index rebounded in June, while industrial production and manufacturing production fell in May. Motor vehicles (which can be volatile) accounted for a big part of the drop. Capacity Utilization fell to 74.9%. Interestingly, more CEOs intend to increase capital expenditures than they did in the first quarter.

Morning Report: Uncle Sam is a huge consumer creditor 6/13/16

Stocks are lower this morning on fears over Brexit (The 6/23 vote to decide whether the UK leaves the EU). Bonds and MBS are up small.

No economic data today. The big event this week will be the FOMC meeting Tuesday and Wednesday. The markets are expecting no changes to interest rates, so any bond rally on the news of no changes will probably be limited.

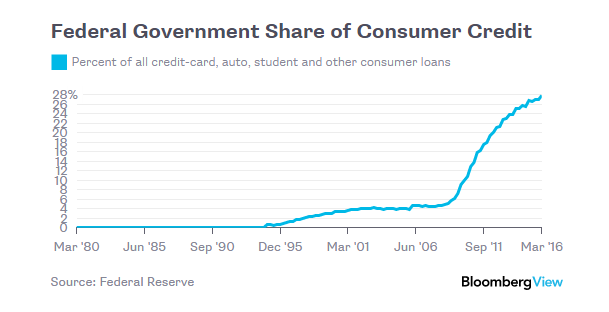
Interesting chart about the Federal government’s percent of ownership of consumer debt. This is money that US citizens owe Uncle Sam. Ever since Obama nationalized the student loan sector, they have taken their percentage of consumer debt from 5% to 28%. The student loan market is a $1.3 trillion market – not exactly chump change. Expect some sort of write-down of student loan debt in the future: many graduates have degrees that will never pay enough to work this down. As a side note, more young adults aged 18-34 live at home with Mom and Dad than in any other arrangement.

Speaking of Millennials, the high student loan debt is causing lower credit scores. The average credit score for the 18-34 age cohort is 625, compared to the national average of 667. Almost a third of that age cohort have sub-600 scores. Good luck getting a loan with that. Finally, all of the new post-2008 regulations have added anywhere form 50k-100k to the cost of building a starter home, making it difficult for builders to make homes that are affordable for the first-time homebuyer.

There is now $10 trillion worth of global sovereign debt trading at negative yields. Bill Gross of Janus Capital calls that a “supernova” that will explode one day. All of the worlds’ central banks are on a mission to create inflation: one day they will succeed. What has been the best trade for bond investors lately? The Japanese 30 year bond, which now yields 28 basis points. Bill says that bond yields today are the lowest in 500 years. Not sure where he comes up with that number.

Speaking of Central Bank jiggery-pokery, ECB corporate bond buying now makes up for 1 in 5 trades. We are truly in uncharted waters with global central banking.

As a general rule, buy stocks in an election year. Election years tend to be optimistic times, and the Fed is usually on your side. That might not be the case this year.

Carbon capture and storage – Turning air into stone 6/11/16

How to keep waste carbon dioxide in the ground
Jun 11th 2016 | From the print edition The Economist |  They probably would have given permission to reprint, right?

THIS year the world’s power stations, farms, cars and the like will generate the equivalent of nearly 37 billion tonnes of waste carbon dioxide. All of it will be dumped into the atmosphere, where it will trap infra-red radiation and warm the planet. Earth is already about 0.85°C warmer than last century’s average temperature. Thanks to the combined influence of greenhouse-gas emissions and El Niño, a heat-releasing oceanic phenomenon, 2016 looks set to be the warmest year on record, and by a long way.

 
It would be better, then, to find some method of disposing of CO 2 . One idea, carbon capture and storage (CCS), involves collecting the gas from power stations and factories and burying it underground where it can do no harm. But CCS is expensive and mostly untried. One worry is whether the buried gas will stay put. Even small fissures in the rocks that confine it could let it leak out over the course of time, undoing much of the benefit. And even if cracks are not there to begin with, the very drilling necessary to bury the gas might create them.

 
A paper just published in Science offers a possible solution. By burying CO 2 in the right sort of rock, a team of alchemists led by Juerg Matter, a geologist at Southampton University, in Britain, was able to transmute it into stone. Specifically, the researchers turned it into carbonate minerals such as calcite and magnesite. Since these minerals are stable, the carbon they contain should stay locked away indefinitely.

 
Dr Matter’s project, called CarbFix, is based in Iceland, a country well-endowed with both environmentalism and basalt. That last, a volcanic rock, is vital to the process, for it is full of elements which will readily react with carbon dioxide. Indeed, this is just what happens in nature. Over geological timescales (ie, millions of years) carbon dioxide is removed from the air by exactly this sort of weathering. Dr Matter’s scheme, which has been running since 2009, simply speeds things up.

 
Between January and March 2012 he and his team worked at the Hellisheidi geothermal power station, near Reykjavik. Despite its green reputation, geothermal energy—which uses hot groundwater to drive steam turbines—is not entirely emissions-free. Underground gases, especially CO 2 and hydrogen sulphide (H 2 S), often hitch a ride to the surface, too. The H 2 S, a noxious pollutant, must be scrubbed from the power-station exhaust before it is released, and the researchers worked with remainder, almost pure carbon dioxide.

 
They collected 175 tonnes of it, mixed it with a mildly radioactive tracker chemical, dissolved the mixture in water and pumped it into a layer of basalt half a kilometre below the surface.  They then kept an eye on what was happening via a series of monitoring wells. In the event, it took a bit less than two years for 95% of the injected CO 2 to be mineralised.
They followed this success by burying unscrubbed exhaust gas. After a few teething troubles, that worked too. The H 2 S reacted with iron in the basalt to make pyrites, so if exhaust gas were sequestered routinely, scrubbing might not be needed. This was enough to persuade Reykjavik Energy, the power station’s owners, to run a larger test that is going on at the moment and is burying nearly 10,000 tonnes of CO 2 and around 7,300 tonnes of H 2 S.

 
Whether CarbFix-like schemes will work at the scale required for fossil-fuel power stations remains to be seen. In these, the main additional pollutant is sulphur dioxide, which has different chemical characteristics from hydrogen sulphide. Scrubbing may therefore still be needed. Another constraint is the supply of basalt. Though this rock is common, it is found predominantly on the ocean floor. Indeed, geologically speaking, Iceland itself is a piece of ocean floor; it just happens to be above sea level. There are some large basaltic regions on dry land, but they are not necessarily in convenient places.

 
Nevertheless, if the will were there, pipelines from industrial areas could be built to carry exhaust gases to this basalt. It has not, after all, proved hard to do the reverse—carrying natural gas by pipeline whence it is found to where it is used. It is just a question of devising suitable sticks and carrots to assist the process. How much those sticks and carrots would cost is crucial. But Dr Matter’s proof of the principle of chemical sequestration in rock suggests it would be worth finding out.

Morning Report: Negative equity falls 6/10/16

Stocks are lower this morning on no real news. Bonds and MBS are up as sovereign bonds rally globally.

The 10 year has broken out of its range and is now trading at 1.65%. The catalyst has been lower rates throughout the world. The German 10 year Bund is now trading at 2 basis points. The Japanese Government Bond yields negative 13 basis points. At some point, gold has to become interesting as an investment. The knock on gold was always that there is no yield, but compared to long term sovereign bonds that have no yield and (probably) no upside, why not? Definitely a better risk / reward.

Mortgage originator and servicer Walter Investment got slammed yesterday after the CEO resigned. Regulatory difficulties and costs were the catalyst. The stock has lost 82% of its value over the past year.

In economic news, initial jobless claims fell to 264k from 268k the week before. So in spite of the low job creation numbers, we aren’t seeing firms lay off people yet.

Consumer confidence fell slightly in June to 94.3 from 94.7 according to the University of Michigan Consumer Sentiment Survey

268,000 homes regained positive equity in the first quarter, according to CoreLogic. They estimate that 4 million homes (or about 8% of the homes with a mortgage) have negative equity. 18% of homes have less than 20% equity. Negative equity remains a problem in the Northeast, the Rust Belt and FL, NV, and AZ.

Ex Fed Head Narayana Kochlerakota argues the Fed should be doing more to get inflation up. Not only should they hold off on raising rates until the core PCE is above 2%, but it should pay nothing on excess reserves.

Scott Adam’s is a Fascist 6-8-16

Today, Amanda Marcotte published an article in Salon maintaining that Dilbert has Gone Fascist.

As an interesting aside, I discovered this when I was typing in the words “scott adams” into my search bar to get to Scott Adams blog. Google and/or Apple is apparently heavily invested in making sure that everybody who wants to go to Scott Adam’s blog gets a chance to read Amanda Marcotte’s wisdom on Dilbert’s/Scott Adams’ embrace of racism.

scottadamssearchbar

Anyway, onto Marcotte:

In the real world, Trump has off-the-charts unfavorability ratings, but in the world of Scott Adams, Trump is  a svengali of politics, headed for a landslide in November, due to the enormous persuasive power of racist cracks and non sequitur ramblings. If you read enough of Adams’s blog, it becomes quickly apparent that the only reason Adams thinks this is because he himself is persuaded to vote for Trump. And, like his fellow narcissistic Donald Trump, Adams mistakes his views for the majority.

I think this is a legitimate objection to Scott Adams’ insistence that Trump will win by a landslide in November. Specifically, what I have not seen Adams address is the difficulty of persuading entrenched opposition. Persuasion and branding are powerful things, but their effects are also often semi-permanent to permanent. Once successfully persuaded to buy fully into something from a car brand to a computer ecosystem to an ideology, it’s very difficult to brand and persuade someone out of it.

If you’ve been buying Apple Macintosh computers for years, your next one is likely to be an Apple Macintosh, and no amount of compelling persuasion techniques by Lenovo or Intel or Microsoft is going to change that. No matter how good. This is why Trump’s powerful persuasion techniques identified by Adams’ are unlikely to result in a landslide for Trump in November. This is not a competition between two brand new products in an entirely new category. There is already a lot of baked-in brand loyalty, and a good advertising campaign may move the needle, but the shift will not be seismic.

However, things like this are awesome:

Despite claiming not to support anyone, Adams has largely handed his blog over to defending Trump from his critics.

He doesn’t really do a lot of defending Trump from his critics. He’s asserting that Trump’s dispensing of facts and logic in favor of persuasion techniques, intentional or accidental, is superior to what anybody else is doing in the campaign, and that certainly proved to be true as far as the Republican primary went.

Trump makes a blatantly racist remark about Judge Gonzalo Curiel being “Mexican” and therefore, in Trump’s opinion, unable to render an impartial verdict in the Trump U case? Adams says that Trump critics must therefore be saying Curiel is a “robot” because “100% of humans are biased about just about everything.”

She includes a link to the original blog post which makes it pretty clear Adams is writing a satirical piece on the absurdity of identity politics and the concept of impartiality (in his opinion), and analyzing Trump’s strategy from his perspective on the art of persuasion:

Curiel looks human on the outside, and he has passed as human for decades. But Cooper made it clear in his interviews yesterday that while science understands that 100% of humans are biased about just about everything, this robot judge is not susceptible to being influenced by his life experiences. It sounds deeply implausible, but no one on CNN challenged Cooper’s implication that Judge Curiel is the only bias-free entity in the universe. Ergo, he must be a robot.

Anyway, lots of folks on Twitter are asking me why Trump would accuse the robot judge of being “Mexican” when that is obviously a racist thing to say. Did Trump make a huge mistake, or is it some sort of clever persuasion thing?

Clearly, Adams is defending both racism and fascism. It is not possible to reach any other conclusion.

The nut of Adams argument (as with pretty much all his Trump posts) and basically untouched on by Marcotte, who tries to use her own lame skills at persuasion to convince us that Adams only wants to slavishly defend Trump and was only using the above blog post to assert that Trump critics were saying the judge, Curiel, is actually a robot (literal, much?) … and, where was I? Oh, yes, the nut of Adams argument regarding Trump and Curiel:

1. Trump wins in court, in which case, Trump wins.

2. Trump loses in court, in which case, Trump says Democrats rigged the system to give him an unfair trial. We’re already primed to believe it.

From a legal perspective, race is not a reason to remove a judge. I haven’t heard anyone argue otherwise. But from a persuasion perspective, Trump is setting the stage for whatever is to come. So yes, it is smart, albeit offensive.

Not quoted by Marcotte, of course, presumably to avoid her readers being offended by reading what Adams actually said, instead of her skewed interpretation of it.

Adams writes a whole blog post sneering at the very idea that one is capable of predicting a person’s future behavior on their past record.

Except, of course, Adams is demonstrably correct in his actual assertion. Also, there are no quotes, of course, because things like this would erode her primary assertion:

So, how did President Obama do on the job? Was he a good president?

If you have an answer in your head – either yes or no – it proves you don’t know how to make decisions. No judgement can be made about Obama’s performance because there is nothing to which it can be compared. No one else in a parallel universe was president at the same time, doing different things and getting different results.

I’m not a fan of everything our president has done, but I feel as if historians will rank him as one of our best presidents. Definitely in the top 20%.

Wait, what? Am I crazy?

Many of you think Obama nearly destroyed civilization. You and I can’t both be right. But both of us can be irrational in trusting our opinions. We are literally comparing Obama’s actual performance to imagined alternatives that exist only in our minds. Maybe you think the imaginary president in your mind is way better than the real one, whereas I think the real one did well compared to my imaginary alternative.

That isn’t thinking. Science is pretty clear on that.

Marcotte never mentions that this Trump-infatuated sycophant thinks Obama will be ranked in the top 20% of US Presidents. Hmmm.

I will not dive into the plenitude of evidence that people are horrible at prediction, and wildly overestimate their own ability to predict the future, their own future behavior, and the future behavior of others beyond the simplest degrees of complexity.

Back to Marcotte:

Now Adams has a real doozy of post, where he pretends to endorse Clinton, but of course it’s a cover story for his real endorsement: Trump. In the post, Adams literally accuses Clinton of trying to get Trump killed because, “once you define Trump as Hitler, you also give citizens moral permission to kill him.”

I understand that when people lampoon our sacred cows, we don’t find the humor funny. However, I am prone to believe that Marcotte doesn’t understand that part of what Scott Adams is doing is parody. I find it also ironic (and interesting un-self-aware) that Marcotte does not seem to associate that post as using an inversion of the same logic Trump’s critics do when they blame him for violence at his rallies.

Obviously, this is not a Clinton endorsement. The purpose of this is to try to convince people that Clinton is some kind of dangerous fascist demagogue who will send her brownshirts into the street to force people into compliance with violence. This opinion, of course, has nothing to do with the real life Clinton and everything to do with Adams’s fantasy version of her.

I’m not sure she understands satire. Or irony. There has been a constant and ongoing comparison of Trump to Hitler and his supporters to brownshirts for the more hyperbolic elements of the left and the Democrats. Did Marcotte miss that?

It’s a fantasy version of Clinton that is quite obviously a direct result of Adams’s own bizarre hang-ups about women. Adams has a long history of being obsessed with the idea that women have grown too powerful and they are pushing hapless men around in our new feminist dystopia.

Oh, well. Of course she missed it. When you are a hammer, I suppose everything looks like a nail.

For instance, there is the classic post where he argued that ours is a “female-dominated” society, because, in what he clearly believes is a grave injustice, “access to sex is strictly controlled by the woman.” They are allowed to turn you down even if you pay for dinner first. And you ladies think you have it bad just because you get paid less, are far likelier to be raped, and have to endure politicians trying to force childbirth on you against your will.

Some of that she’s just making up. An important part of that post that Adams’ perhaps should have emphasized is this:

Now compare our matriarchy (that we pretend is a patriarchy) with the situation in DAESH-held territory. That’s what a male-dominated society looks like. It isn’t pretty. The top-ranked men have multiple wives and the low-ranked men either have no access to women, or they have sex with captured slaves.

He’s arguing that a real patriarchy looks like ISIS or the Taliban or Saudi Arabia. Yet she asserts that Adams is suggesting the fact that America isn’t run by the Taliban is a “grave injustice”.

About another post, in which Adams suggest there’s really no middle ground in the war between the sexes, either men or women will win (and he seems, to me, to think it’s sad that men can’t win, but it’s better for humanity that women do) , Marcotte writes:

 He concludes that the only solution to this problem is to “come up with a drug that keeps men chemically castrated” and eliminate all copulation, because clearly, in his mind, the only way men can express themselves sexually is by abusing women.

Always comes to the same thing with feminists. Men and women having sex = abusing women.

I gotta say, she needs to work on her persuasion skills.