An “independent”, agenda-setting bureaucracy 10/24/16

There is an op-ed article today in the WSJ, unfortunately behind the firewall, that unwittingly lays bare the unconstitutionality of the regulatory state as it currently exists in the US. The article was written by former Chairman of the SEC, Arthur Levitt Jr., and is ostensibly a critique of Senator Elizabeth Warren’s call for current SEC Chairman Mary Jo White to be removed for failing to implement a “rule” regarding corporate political donations that Warren favors. Levitt correctly calls out Warren for improperly trying to influence the SEC’s “agenda”, but his reasoning reveals the mindset of these unelected bureaucrats and how shamelessly unmoored from the Constitution the regulatory state has become.

Levitt says:

No rule—no matter how merited—is worth the damage that would be caused if the SEC were compelled by political intimidation to write it. That’s not how good regulations emerge, and what’s worse, it would poison the regulatory process for all time. The moment the SEC loses its ability to set its own agenda is the moment it loses its ability to protect the investing public.

The SEC does not operate as a pass-through entity for Congress, merely following congressional direction. Rather, it’s an independent agency, and its chairman is empowered to set the agenda for the agency’s work. This agenda takes shape in many forms—rule makings, speeches and enforcement actions—and must be set by the chairman, not Congress. This is by design.

Say what? The “agenda” of unelected bureaucrats agency “must be” set by themselves and not by the elected members of Congress? Perhaps Levitt would like to point out where in the Constitution such bureaucrats have been granted this rather awesome power. Contrary to what Levitt seems to think, that the SEC is supposed to operate as a “pass-through” entity for Congress, following its direction, is the only way it can operate that would justify its existence.

Levitt goes on to say:

That’s not to say the agency should be free from congressional oversight. Throughout its history, politicians from both parties have sought to influence its work. That’s to be expected, and a good regulator welcomes outside views, especially those coming from elected leaders who write the laws the SEC implements. Ultimately, Congress holds the power to pass laws requiring agency action; and that option is available to Sen. Warren.

But Congress must respect the SEC’s independence, and thus freedom, to focus on a fixed agenda. Once confirmed to lead the SEC, its chairman has a singular goal: To meet the agency’s mandate to protect investors, facilitate capital formation, and ensure fair and orderly markets.

Well, isn’t that generous. Good regulators should “welcome” the “outside” views of elected representatives, the very people who are actually empowered by the Constitution to write legislation.

Levitt is of course correct to inform Warren that if she wants to impose a new law, Congress has the power to do exactly that through actual legislation. But it is precisely the vaguely defined regulatory “mandate” that Levitt himself embraces which allows the likes of Warren to think that she can impose new laws without the hassle of actually going through the constitutional process.

This is an excellent example of how pervasive and shameless the undemocratic, unconstitutional mindset that typifies the regulatory bureaucracy has become.

(This link may or may not work to get the article…not sure: http://on.wsj.com/2e3zIc8)

Morning Report: More rent versus buy 10/21/16

Vital Statistics:

Last Change
S&P Futures 2124.7 -12.0
Eurostoxx Index 343.3 -1.0
Oil (WTI) 50.3 -1.3
US dollar index 88.6 0.0
10 Year Govt Bond Yield 1.74%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.57

Stocks are lower this morning on no real news. Bonds and MBS are up.

No economic data today, however we do have some Fed-speak.

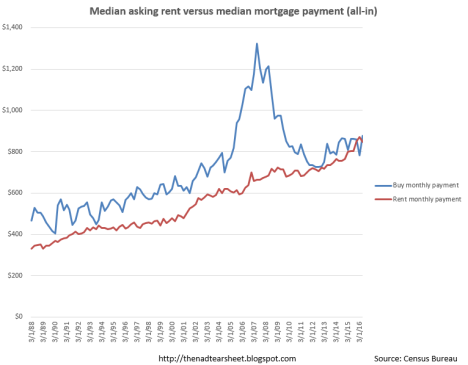
Following on yesterday’s rent-versus-buy article from Trulia, I crunched some numbers to demonstrate the relative value proposition currently. Using census data for median asking rent and median house prices, I plotted the median asking rent against the mortgage payment for a FHA loan with 3.5% down, including mortgage insurance, property taxes, homeowner’s insurance, and the tax benefit of deducting interest and property taxes for a borrower making the median income. Historically, buying has resulted in a payment higher than the median rent payment. This makes sense: your mortgage payment will be more or less fixed, while rent will increase with inflation.

The chart below plots the two numbers in absolute dollars. You can see the two lines converging which means the rent-versus-buy decision is about as far skewed towards buying than it ever has been.

rent-vs-buy-graph

In the second chart, I plotted the difference between the “median” mortgage payment and median asking rent. The range recently has been anywhere from -10% to 100%.

rent-vs-buy-percent

The other thing to keep in mind with the rent vs buy decision is that the world’s central banks are on a mission to create inflation. They will eventually succeed, and over time the asking rent is going to increase, while the mortgage payment will be largely fixed, with the exception of property taxes and perhaps homeowner’s insurance. On the other side of the coin, home price appreciation will probably maintain at least a mid-single digit rate of appreciation, which is higher than the mortgage interest rate, especially when you take into account the tax benefits.

The takeaway is that the Fed is giving the homeowner a gift in low rates, and that won’t last forever.

Morning Report: Buying is still a better deal than renting 10/20/16

Vital Statistics:

Last Change
S&P Futures 2135.3 -3.0
Eurostoxx Index 341.6 -2.0
Oil (WTI) 50.7 -0.9
US dollar index 88.0 0.0
10 Year Govt Bond Yield 1.75%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.57

Stocks are lower this morning after ECB President Mario Draghi said the ECB is not looking at doing more QE after the program ends in March. Bonds and MBS are up.

In economic data this morning, initial jobless claims rose 13k to 260k. Separately, the Bloomberg Consumer Comfort Index fell. The Philly Fed manufacturing index improved in September, but manufacturing has generally been weak across the board as the stronger dollar hurts competitiveness overseas.

Existing Home Sales rebounded in September to an annualized pace of 5.47% from a downward-revised pace of 5.3 million in August. The median home price was up 5.6% to $234,200. The first time homebuyer represented 34% of all sales, which is a big improvement from the 30% – 32% range it had been stuck in for the past year. Inventory remains tight, however with about 2.05 million homes on the market, which represents a 4.5 month supply. A balanced market is closer to 6.5 months. Distressed sales (foreclosures and short sales) represented 4% of all sales, which is a post-crisis low. Days on market ticked up to 39 days from 36 in August. The increase in the first time homebuyer is definitely good news, and we may finally be seeing the pent-up demand that has been building over the past 10 years finally come to market.

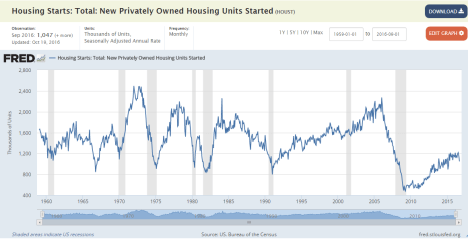
In spite of all that pent-up demand, housing starts remain anemic given where we are in the economic cycle. Housing construction has been the missing link this whole recession. Note the shaded grey areas on the chart. Those are recessions. See how housing construction historically experienced a sharp rebound after the economy bottomed? We haven’t seen that this time around. Some of that was due to an overhang of inventory from the bubble years that needed to be sold, however that adjustment was made by 2011 or so. Since then, tight inventory and rising prices have been the story. The reason why this recovery has been so tepid has been the absence of a robust housing construction market.

housing-starts-fred

Note that Fannie Mae thinks that housing construction will remain muted. In their latest Economic Commentary, they forecast housing starts will grow to about 1.3 million in 2017, which is about 12% higher than their forecast for 2016. The bright spot? SFR will increase to 15% to an annualized pace of 883k. SFR will cannibalize multi-fam going forward as the economy improves and more Millennials go from being renters to being buyers. Speaking of which…

Trulia has a good piece out on the advantages of buying versus renting. Buying a home is 37% cheaper than renting nationally. Naturally, the advantage differs from market to market, but even the worst markets for buying are still 17% cheaper. This assumes the buyer puts down 20% and stays in the house for 7 years. The advantage was as high as 41% in 2012, and got as low as 34% in 2014. Of course this is a moving target as mortgage rates and house prices change. Where are the tipping points to flip the relationship? For home prices, it is a median house price of $468k. For mortgage rates, it is 9.1%.

trulia-rent-vs-buy

Who Needs to Internet Hack a Secured Computer if the Hired Hands can Walk Out With Thumb Drives Every Night?

They expressed astonishment that Mr. Martin managed to take home such a vast collection of classified material over at least 16 years, undetected by security officers at his workplaces, including the N.S.A., the Office of the Director of National Intelligence and Pentagon offices.

I could understand a contractor coming in for a specific project requiring a specialist.

One of my remaining Friday morning group of friends, George, was the electronics/room environment/controls specialist at IBM’s huge Austin facility until he retired at 58. Since then, he has done month long projects for other folks, including Chinese companies, finding glitches and spikes, hunting down and changing out motherboards with heating problems, measuring the cooling necessary in an enclosed area, imposing clean standards in a room, but also rewriting control software code and substituting parts that gives him access to secret or proprietary stuff. George often faces days of security checks on his work that slow him down, as one result, but allay his employer’s fears, as another.

Of course I am sure NSA has in-house employed engineers for the job of keeping the control systems operational and up to date, but I am sure there would be a need for specialists from time-to-time.

I draw a distinction between that use of short term one-off specialists and Martin having so many years of continuing access. That’s crazy.

Working at NSA should come with weekly polygraph tests and federal courthouse level searches every morning and every night, at least. Whatever they are doing to secure against physical theft by thumb drive, it isn’t working.

Morning Report: Housing starts disappoint 10/19/16

Vital Statistics:

Last Change
S&P Futures 2137.5 4.0
Eurostoxx Index 343.1 0.6
Oil (WTI) 51.1 0.8
US dollar index 88.0 0.0
10 Year Govt Bond Yield 1.76%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.57

Stocks are up this morning as earnings reports continue to pile in. Bonds and MBS are flat.

Mortgage Applications rose 0.6% last week as purchases rose 3% and refis fell 1%.

Housing starts fell to a 1.05 million pace in September, driven by a big drop in multi-fam. Single fam was up around 8%. Building Permits rose to 1.23 million. Housing continues to be the biggest underperformer in the economy, but the subject hasn’t really come up in this election, for either side.

We have some Fed-speak today, with John Williams speaking at 8:45, Rob Kaplan at 1:30 and William Dudley tonight.

The final debate is tonight, and it looks like Hillary is pulling away from Trump at this point. The black swan event for the markets is a Democratic Party sweep, which will probably cause the stock market to spit up a hairball.

Lending standards in the jumbo space are loosening, even as the luxury end of the housing market underperforms. Loan Depot is now offering 40 year jumbo products that are interest-only for the first 10 years. Redwood is now offering a 90 LTV product that goes down to a 660 FICO.

The NAR is releasing its latest Profile of Home Buyers and Sellers. Here are the big changes over the past 35 years.

  • The first time homebuyer is a smaller percentage than it has been in the past.
  • The internet is not replacing the real estate agent
  • Houses have been getting bigger of the past 30 years, but have leveled out in recent years
  • Down payments have been going down
  • The home search process is taking longer than ever due to tight inventory

Zillow has their own report on trends in housing. Here is the executive summary (the report is very long and detailed):

“The home buying experience is both an intimidating financial transaction and an emotional milestone. Half of home buyers in the U.S. are under 36, meaning a new generation— Millennials—is shaping the future of real estate. Despite demographic reports about young adults’ urban lifestyles, Millennials share their parents’ aspirations for a single-family home, often in the suburbs.

The process of finding or selling a home is much more collaborative for Millennials than for older generations. They bring all available tools to the process, including their smartphones, social media and online networks. While older generations rely on real estate agents for information and expertise, Millennials expect real estate agents to become trusted advisers and strategic partners.

Millennial home buyers are also diverse. While only 9 percent of all homeowners are Hispanic, nearly 15 percent of the Millennials buying homes are Hispanic—reflecting the changing demographics of the American middle class.

Homeownership remains a vehicle for wealth in the U.S., but it can also be a financial burden, as families stretch their finances to afford the space they need, and large, dated homes owned by Baby Boomers and the Silent Generation demand maintenance and improvements.”

Morning Report: Inflation returns 10/18/16

Vital Statistics:

Last Change
S&P Futures 2137.5 15.0
Eurostoxx Index 342.3 5.0
Oil (WTI) 50.4 0.4
US dollar index 88.1 -0.2
10 Year Govt Bond Yield 1.78%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Stocks are higher this morning on no real news. Bonds and MBS are down.

It looks like the Fed has made some progress in getting inflation up to its goal of 2%. The Consumer Price Index came in at 0.3% MOM. Ex-food and energy it is up 2.2% on a YOY basis. The Fed doesn’t really look at CPI all that much – it prefers the Personal Consumption Expenditure Index – but it looks like we are moving further away from the deflation ledge that central bankers fear.

What drove the increase in the core index? Owner-equivalent rent, which is a proxy for real estate prices. It rose 0.4%, which is the highest reading since 2006.

What does increasing inflation mean for the mortgage business? Assuming higher inflation translates into wage inflation, you should see a pick-up in the purchase business as Millennials get jobs / raises. On the other hand, the refi business is going to take a hit.

One Texas builder is focusing on the entry-level homebuyer and using USDA loans to help make the sale. LGI Homes, based in Houston, is marketing to people in apartment complexes with flyers discussing the monthly payment they could have if they bought. These are largely properties in the exurbs around Dallas and Houston, where lower land acquisition costs translate into lower average selling prices. ASPs for LGI are below 200k, while ASPs for new homes in general is over $350k. LGI reports seeing the steadiest demand in entry-level.

Sentiment for the builders is high in general. The NAHB Housing Market Index fell 2 points in October, from its record in September.

High property taxes got you down? Here is something you can do about it.

Morning Report: Manufacturing disappoints 10/17/16

Vital Statistics:

Last Change
S&P Futures 2126.5 -0.5
Eurostoxx Index 338.0 -2.0
Oil (WTI) 40.4 0.0
US dollar index 88.3 -0.2
10 Year Govt Bond Yield 1.78%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.58

Stocks are lower this morning on overseas weakness. Bonds and MBS are down.

Manufacturing in the US rose slightly in September, but came in lower than expected. August’s numbers were revised downward. Industrial Production rose 0.1%, while manufacturing production rose 0.2%. Capacity Utilization rose to 75.4%. The strength in the dollar is probably driving the weakness.

Manufacturing dropped in New York last month, according to the Empire State Manufacturing Index. The index fell for the third month in a row.

The black swan event for the financial markets? A democratic party sweep in November. If so, buy infrastructure stocks, sell pharma and financials.

Meanwhile, turnout is looking to be low this year as voters dislike both candidates and are tuning out all the rhetoric.

Elizabeth Warren fired a shot across the bow of the SS Hillary, directing her to demote SEC Chair Mary Jo White. Her sin? Not going along with the left who wants more disclosure of political activities and donations for corporations. Of course this has absolutely nothing to do with investor protection: it is more about using the regulatory power of the SEC to silence opinions that she doesn’t approve of (mainly businesses that donate to the Chamber of Commerce or other groups that argue for lighter regulation or lower taxes).

Morning Report: bank earnings 10/14/16

Vital Statistics:

Last Change
S&P Futures 2137.5 11.0
Eurostoxx Index 340.8 5.0
Oil (WTI) 50.7 0.3
US dollar index 88.3 0.2
10 Year Govt Bond Yield 1.78%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.58

Stocks are higher this morning on good overseas economic data. Bonds and MBS are down.

Inflation at the producer level is picking up, according to the Producer Price Index, which rose 0.3%, higher than expected. The core index is up 1.5% YOY. Inflation remains under the Fed’s target, but we are seeing it creep up towards their preferred 2% range.

Retail sales increased 0.6% last month, in line with expectations. Retail Sales ex autos and gasoline rose 0.3%. Housing-related sales did particularly well, with furniture up 1% and building materials up 1.4%. I wouldn’t be surprised to see some strategists take up their Q3 GDP estimates on this number.

Consumer sentiment unexpectedly fell in early October, according to Reuters and the University of Michigan.

Business inventories rose 0.2%, a little higher than expected. This will have the effect of goosing Q3 GDP growth at the expense of Q4.

Wells Fargo reported earnings this morning. Origination was up 11% QOQ to $70 billion. Purchase activity accounted for 58% of originations. The stock is unchanged in early trading.

JP Morgan reported earnings this morning as well. Mortgage origination was up 8.4% QOQ to $27.1 billion. On an annualized basis, it is down 9.4%.

The typical homeowner’s perception of the value of their home is about 1.25% lower than where the appraised value has been coming in. Appraised values are up almost 8% YOY, which is a faster rate of appreciation than we have been seeing in the real estate indices like FHFA or Case-Shiller.

Morning Report: PIMCO is buying mortgages 11/13/16

Vital Statistics:

Last Change
S&P Futures 2116.0 -15.0
Eurostoxx Index 334.4 -4.0
Oil (WTI) 50.0 -0.1
US dollar index 88.4 0.1
10 Year Govt Bond Yield 1.75%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Stocks are lower this morning after weak Chinese data. Bonds and MBS are up.

The FOMC minutes showed that September was a close call with respect to raising rates, and definitely set up the markets for a December rate hike. The Fed noted that third quarter GDP was stronger than the first half of the year, and the labor market is strengthening. The consensus for a December tightening doesn’t necessarily indicate that there is the same consensus for further rate hikes. Interestingly, the Fed views consumer spending as”growing strongly” when the actual data does not suggest much strength at all. Bottom line, it looks like we are getting a rate hike in December, and the November meeting will be a non-event. The Fed Funds futures are assigning a 68% probability of a December hike of 25 basis points.

Initial Jobless Claims fell to 245k last week, which is the lowest since the early 70s.  Consumer comfort increased last week as well.

Import prices rose 0.1% MOM and are down 1.1% YOY. Export prices rose 0.3% MOM and are down 1.5% YOY. Strategists are warning that the rise in the dollar is going to hit corporate profits.

PIMCO is getting into a defensive posture, buying mortgage backed securities and inflation-linked securities. Mortgage backed securities now account for 55% of the Total Return portfolio from 49% in August. Why mortgages? Think about what will happen to long term bonds as the Fed hikes rates. If long term bonds don’t really move all that much (in other words, the yield curve flattens) the yield on mortgage backed securities will be much better than the yield on Treasuries. If the long end of the curve increases in line with the increase in the Fed funds rate, PIMCO is betting that the decrease in prepayment speeds will offset (at least partially) the interest rate effect. You can see over the past 5 tightening cycles, the yield curve has flattened.

John Stumpf is out at Wells. COO Tim Sloan, will take over. While the scandal was in the retail banking are and not the mortgage division, there probably will be fallout there too.

The Fed shrinks its balance sheet using this one weird trick..10/12/16

Vital Statistics:

Last Change
S&P Futures 2130.8 -4.0
Eurostoxx Index 339.6 -0.6
Oil (WTI) 50.8 0.0
US dollar index 88.4 0.1
10 Year Govt Bond Yield 1.79%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Stocks are down again after getting roughed up yesterday. Bonds and MBS are down as well.

Mortgage applications fell 6% last week as purchases fell 3% and refis fell 8%.

Job openings decreased by 400k to 5.4 million in August, according to the BLS. The quits rate (which is probably the best indicator for strength in the labor market) was steady at 2.1%. I wonder if we are seeing employers begin to hire the long-term unemployed, which would account for the drop in openings and the flat quits rate. The labor force participation rate is beginning to pick itself off the floor, as we saw in the latest jobs data.

We will get the FOMC minutes from the September meeting at 2:00 pm EST today. Be aware of possible market movement around then, especially if the minutes turn out to be a bit more dovish than expected. On Sunday, Fed Vice Chairman Stanley Fischer said that September’s decision to wait on hiking rates was a “close call.” The minutes will hopefully shed further light on that statement.

The biggest problem with QE is what to do with all of these assets that now sit on the Fed’s balance sheet. The Fed can’t sell the Treasuries it bought without withdrawing liquidity from the system. That would be contractionary, and the economy (or at least the financial system) might be too fragile to handle it. That would be the case even if the Fed just lets it run off by not re-investing maturing proceeds. There is now a school of thought that the Fed’s balance sheet should simply remain the size it is now, and we shouldn’t return to pre-bubble levels. The thinking is that governments should simply consolidate the Fed’s assets onto its own balance sheet. (called “permanent monetization”) Given that central banks are ultimately owned by the government, its Treasuries would effectively “cancel out” the debt issued by the government. This is why looking at the debt to GDP ratio is somewhat misleading: about a quarter of our debt is owned by the central bank. It is like taking out a loan and leaving the money in your savings account. In nominal terms, your debt is up, but your net worth is unchanged. One thing is for sure: none of this is in the econ textbooks. We are all making it up as we go along.

A Federal Appeals court ruled yesterday that the CFPB’s structure is unconstitutional. The director of the CFPB is appointed for a 5 year term, and can only be fired for cause by the President. The court found that this structure puts too much power in the hands of one person, and is more or less unaccountable. Rob Chrisman takes a look at what is going on.

A study from the Urban Institute forecasts that the homeownership rate will continue to decline. The question ultimately rests on whether the Millennials are going to follow a different path than previous generations, or are they simply late bloomers who will eventually marry, have kids, and want a place in the suburbs. Note that the homeownership rate started going vertical in 1994, with the Clinton Administration’s policies to encourage homeownership, as a tool for social engineering. Post-crisis, the rates has returned to its previously undisturbed rate.