Morning Report: Existing home sales near 10 year record 11/22/16

Vital Statistics:

Last Change
S&P Futures 2197.5 5.0
Eurostoxx Index 341.5 1.3
Oil (WTI) 48.5 1.8
US dollar index 91.3 0.1
10 Year Govt Bond Yield 2.31%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.99

Stocks are up this morning as commodities rise on anticipated economic strength. Bonds and MBS are flat.

Existing home sales rose 2% to a seasonally-adjusted run rate of 5.6 million in October, according to the NAR. September’s numbers were revised upward to 5.49 million. October’s number is 5.9% higher than a year ago, and the highest reading since February 2007. The median home price rose 6% to $232,200. Total housing inventory dipped to 2.02 million units, which represents a 4.3 month supply at current levels. NAR considers 6.5 month’s worth to be a balanced market. Days on market ticked up to 41 days from 39 the month before. The first time homebuyer accounted for 33% of all

sales, which is up a couple percentage points from a year ago. Now, if we could just get housing starts up to catch up with the increase in sales we could have a real recovery on our hands.

The post-election rise in interest rates is beginning to affect home sales. First time homebuyers are being hit particularly hard. One loan officer has great advice however: the increase in rates may appear dramatic, but the difference in monthly payment often is not. “I tell people, interest rates are 80 percent psychological and 20 percent math. I do the math for them and their next reaction is, ‘Oh that’s all?’ Forty dollars a month, $75 a month. They initially think it’s going to be a lot more painful than that,” said Anker, who added he hasn’t lost any deals yet. ” While we have yet to see any effect in the home price indices (that will probably be a few months out) be prepared for a deceleration in home price appreciation, and maybe even flat / declining prices in the hottest markets.

The Richmond Fed Manufacturing index improved last month from -4 to 4.

Speculators in the US Eurodollar market are betting $2.1 trillion that short term rates are going up as economic growth and inflation return. Note that yesterday, all of the major stock market indices hit new highs. We have been seeing the biggest asset allocation change out of bonds and into stocks over the past week.

Donald Trump took to YouTube last night to give an update on the transition. Probably the biggest news in that was essentially a moratorium on regulations – where for every new regulation, two must be removed. Not sure how that is going to work in practice. The Trans Pacific Partnership trade deal is probably dead at this point as well. Separately, he isn’t going to launch any further investigations on Hillary Clinton.

Front-runner for Treasury Secretary Steve Mnuchin was part of a Goldman consortium that bought failed bank IndyMac, renamed it OneWest and sold it to CIT. This was post-crisis, however his confirmation hearing (if he gets the nom) will undoubtedly spend some time on the mortgage industry and past practices.

Impac said that low interest rates hurt demand for non-QM products last quarter.

When the Chinese bet on real estate, they bet big.

Morning Report: Trump causes jump in Fannie stock 11/21/16

Vital Statistics:

Last Change
S&P Futures 2186.8 6.0
Eurostoxx Index 340.0 0.7
Oil (WTI) 47.0 1.3
US dollar index 91.1 -0.5
10 Year Govt Bond Yield 2.31%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.99

Stocks are higher this morning on no major news. Bonds and MBS are up small.

Should be an uneventful week with the Thanksgiving holiday. Markets will be closed on Thursday, and SIFMA is recommending an early close on Friday.

Donald Trump continued to interview candidates for cabinet posts over the weekend. For Secretary of the Treasury, he talked to famed investor Wilbur Ross, Blackstone head of real estate Jonathon Gray, and David McCormick of Bridgewater. The “in-depth” discussion with Gray “included the economy, global capital markets and the world financial situation as well as “future legislation regarding the tax code and long-term debt. The Ross meeting covered “negotiating the best foreign deals, American manufacturing and job creation,” as well as “engaging Ambassadors to participate in creating more economic opportunities for America,” Trump’s office said. With McCormick, Trump and Pence talked “global financial markets, currency and the American economy,” and “special emphasis was placed on restoring long-term economic growth rates on an annual basis of four to five percent.” Trump insider Steve Mnuchin and Congressman Jeb Hensarling are considered to be the front-runners, however.

Mitt Romney is under active consideration for Secretary of State.

The Chicago Fed National Activity Index improved to -.08 from a downward-revised -.23. Overall economic activity remains slightly below trend.

Traders are now pricing in a 100% chance the Fed hikes next month.

Ever since Trump won, shares in Fannie Mae and Freddie Mac have been soaring. Hedge fund giant John Paulsen has a huge position in the shares and investors are betting that a Trump administration may be more shareholder-friendly than Obama was. Just as Fannie Mae was beginning to turn a profit, the Obama administration re-wrote the rules of the bailout and has taken all of Fannie’s cash flows for the government. The bailout money has now been paid back and shareholders are in litigation with the government over what to do now. Just some numbers: Market cap: 18 billion. 2015 earnings 11 billion. P/E: 1.6.

AIG is looking to boost its investment in residential mortgages. They intend to make “direct investments” into the sector, which may mean buying whole loans instead of MBS.

The CFPB is appealing a Federal Appeals Court ruling that says the agency’s structure is unconstitutional. Regardless of the outcome, the agency is probably going to have at least some changes.

Quick, what has been the best-performing IPO of the tech sector since the Great Recession? It isn’t the names you would think of like Facebook or Tesla. It is Ellie Mae, who makes software that helps automate the mortgage process. Bears are beginning to bet that a Trump administration will be more friendly to the big banks, who will get back into the mortgage business, which is bad news for Ellie Mae’s clients, who are smaller independent lenders.

Morning Report: Jeb Hensarling for Treasury? 11/18/16

Vital Statistics:

Last Change
S&P Futures 2184.0 -0.5
Eurostoxx Index 339.4 -1.2
Oil (WTI) 45.5 0.1
US dollar index 91.3 0.1
10 Year Govt Bond Yield 2.28%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4

Stocks are flat this morning on no real news. Bonds and MBS are down.

Bonds are ending their worst two week run in 25 years as the 10 year bond yield increased almost 50 basis points. Strategists are suggesting that the 10 year will be in the 2.5% – 2.75% range a year from now if Donald Trump manages to get his infrastructure spending plan and tax cut. The US dollar continues to strengthen as well.

So far, it looks like Jeb Hensarling is in the mix to take over as Secretary of the Treasury for Donald Trump. Note he is a politician, not a Wall Streeter. In fact, the banks believe he is a bit of an obstacle for getting real reform. Hensarling is generally viewed as not a friend of the big banks, and he really isn’t that interested in their input. Hensarling does have a plan to reform Dodd-Frank, which would include scrapping the Volcker Rule (which prohibits proprietary trading), reining in the CFPB, eliminating caps that banks can charge merchants for debit card transactions, and reforming the SIFI (systemically important financial institutions) rules. The big banks will need to raise a lot of capital in order to have more latitude however, as his bill requires a 10% capital cushion. Citi, for example, is at 7.4%, which means the banks would need to raise hundreds of billions in new equity capital.

The glory days of the CFPB are numbered. A court ruling that prevents the director from being fired and the potential for a business-friendly Trump Director has made it possible for a bipartisan consensus that the director be replaced with a 5 person committee, and that it be subject to Congressional appropriations. At least one expert believes that will slow down the agency and probably cut its enforcement actions in half. As of right now, if you are a graduate of a top law school and have an interest in financial regulation, the CFPB is the hot place to be.

Bottom line: we could get some regulatory relief, however it will be at the margin and probably not a wholesale change from what we have now. Will it be enough to get the private label securitization market back? So far I have not seen anything with respect to required equity tranches etc, so it is hard to tell. The only name for HUD I have heard is Westchester County Executive Rob Astorino, who is fighting HUD on zoning issues and affordable housing mandates.

After rising for several years, average home sizes are falling, as construction moves away from focusing in the high end to starter homes.

Morning Report: Housing starts jump 11/17/16

Vital Statistics:

Last Change
S&P Futures 2173.8 1.0
Eurostoxx Index 338.3 -0.2
Oil (WTI) 46.1 0.5
US dollar index 90.8 0.2
10 Year Govt Bond Yield 2.25%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4

Stocks are flattish on no real news. Bonds and MBS are down small.

Janet Yellen is speaking on Capitol Hill this morning. Her prepared statement is here. She said that job growth has been lower than last year but still above forecasts. They believe the labor market has further room to run. She pointed out that economic growth has improved from its sluggish start of the year and inflation remains tame. Nothing in the statement would change the forecast for a 25 basis point hike next month.

Speaking of inflation, the consumer price index rose 0.4% in October, in line with forecasts. Ex-food and energy, it rose 0.1% and is up 2.1% YOY.

The NAHB / Wells Fargo Housing Market Index, a measure of homebuilder sentiment was flat at 63, and is still well above neutral.

Housing starts rose to 1.323 million. This is an increase of 23% YOY, which shows the housing market may finally be getting some traction at long last. This is a 9-year high. Remember, “normalcy” is closer to 1.5 million units, so we still have a lot of room for growth. Building Permits were up 4.6% YOY to 1.23 million.

Initial Jobless Claims fell to 235k last week, which is the lowest level since early 1973, just after the Vietnam War draft ended. Employers continue to hang onto their workers.

House prices increased 7% in October, according to RedFin. Inventory dropped by 8.6% YOY, which is the 13th consecutive monthly drop. Homes stayed on the market an average of 49 days, a drop of 5 days from a year earlier. 21% of all homes were under contract within two weeks, and 20% sold for more than their asking price.

Average FICOs for closed loans dropped somewhat in October to 730 from 731, according to Ellie Mae. Purchases accounted for 53% and refis accounted for 47%.Time to close was steady at 48 days. ARMS slipped to 4% of all loans, however as rates increase they will undoubtedly become more popular at some point.

Consumer comfort increased last week, according to Bloomberg.

Democrats named Chuck Schumer Senate Minority Leader yesterday. As a practical matter, he comes from NY so he should be at least somewhat sympathetic to the financial sector, which could go a long way in helping fix some of the issues with Dodd-Frank.

Morning Report: Confidence in the economy improved 11/16/16

Vital Statistics:

Last Change
S&P Futures 2171.8 -8.0
Eurostoxx Index 337.7 -2.0
Oil (WTI) 45.4 -0.4
US dollar index 90.6 0.2
10 Year Govt Bond Yield 2.27%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4

Stocks are weaker this morning as commodities rally. Bonds and MBS are down.

Mortgage Applications fell 9% last week as purchases fell 6% and refis fell 11%. I’m actually surprised it wasn’t worse, as the 10 year bond yield went from 1.78% to 2.14%.

Inflation at the wholesale level remains low as the producer price index was flat for October. Ex-food and energy, they were down .2%. Ex food, energy and services the index was down .1% and is up 1.6% for the year. Certainly nothing to concern the Fed, however the Fed Funds futures are factoring in a 94% chance of a rate hike next month. At the beginning of the month, the odds were 68%.

Donald Trump’s transition team is already having power struggles, as Chris Christie loyalists were sent packing after VP Mike Pence replaced him as head of the transition team. Given that Trump was an outsider, his transition is going to be a lot more rocky than we are used to.

It looks like Trump is considering famed value investor Wilbur Ross and ex-Goldman guy Steve Mnuchin to Treasury and Commerce. Apparently an announcement is imminent.

Industrial Production was flat in October, while manufacturing production was up 0.2%. Capacity Utilization slipped to 75.3%. The strong dollar is going to be a headwind for the manufacturing sector, although its weight in the US economy is a lot smaller than it used to be.

Confidence in the economy surged after the election according to Gallup. The improvement was largely partisan as Republicans became more bullish on the economy.

Fast money poured into ETF last week on the election news. Large caps were bought while small caps were sold. Pharma and biotech saw big inflows, as well as tech, which would benefit the most from an overseas repatriation tax holiday.

Home prices rose 6.6% last month according to the FNC indices.

Morning Report: Retail Sales improve 11/15/16

Vital Statistics:

Last Change
S&P Futures 2165.0 5.0
Eurostoxx Index 338.3 0.1
Oil (WTI) 44.6 1.3
US dollar index 90.5 0.0
10 Year Govt Bond Yield 2.22%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.89

Stocks are up modestly this morning on no real news. The bond bears are taking a break today, everywhere except Japan, where the JGB 10 year yield is now positive.

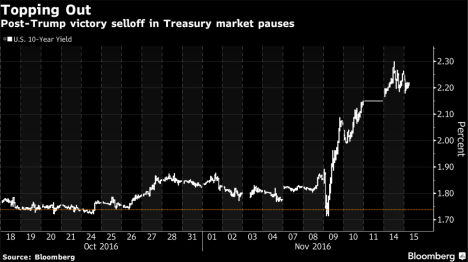
You can see just how dramatic the sell-off in the 10 year has become. Note the big drop in yields as the election was called for Donald Trump, and then the huge reversal. That is the mother of all head fakes. Carl Icahn was buying about a billion dollars worth of S&P 500 futures contracts during that head fake.

10-year

Retail Sales came in stronger than expected in October, rising 0.8%. Ex-autos and gas, they rose 0.6%. The October readings are in that sort of trough period between back to school and the holidays. BTS sales were on the weak side, FWIW so I am not sure what this necessarily means for holiday sales. Stocks seem to like it, with the S&P SPDR retailer ETF (XRT) up a couple of percent pre-open.

More stirrings of inflation? Import Prices rose 0.5% in October, higher than expected. The headline number is even more surprising given that the dollar rose during the month, however the increase was pretty much concentrated in the petroleum sector. Export prices fell.

The Empire State Manufacturing Survey increased modestly in November, climbing out of negative territory for the first time in 4 months. New York State remains in a bit of a funk compared to the rest of the US. The employment indices fell.

More good news for housing: The Despot reported better than expected earnings this morning as people spend more on home improvement.

Is the firing spree finally over in the financial sector? It could be. Since 2005, approximately 800,000 jobs have been shed in the sector. About the only demand came in compliance.

People have been saying for a while that auto loans are the new subprime. It looks like the next subprime is online consumer loans, which were supposed to disrupt the banking industry, but are taking way more credit losses than anticipated. Technology is all fine and good, but if you can’t analyze credit risk properly, you aren’t going to make it.

Head of the SEC Mary Jo White submitted her resignation, which clears the way for a more pro-free market head of the regulatory body.

The jump in rates has been bad news for many in the mortgage business, as it weighs down the refi shops. VA IRRRLs have been a gravy train for many shops and that party looks to be winding down between higher rates and new rules on securitization. Certainly this isn’t great news for the first time homebuyer, however if the employment market continues to improve, that should offset the increase in rates. It will almost certainly mean that further home price appreciation will be harder to come by, as the affordability gift of low rates goes away. Does that necessarily mean the refi market is dead? Cash-out refis where borrowers can refinance their credit card debt will still make a ton of sense, even if mortgage rates top 4%. We may see an increase in ARM demand as a way to lower payments, but with the Fed in a tightening cycle, that is a risky way to go.

Morning Report: Potential Dodd-Frank reform 11/14/16

Vital Statistics:

Last Change
S&P Futures 2164.5 3.0
Eurostoxx Index 338.2 0.7
Oil (WTI) 42.7 -0.7
US dollar index 90.2 0.5
10 Year Govt Bond Yield 2.20%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.89

Stocks are up modestly this morning on no real news. Bonds and MBS are up again.

No economic data this morning, but we will have some Fed-speak in the afternoon.

About $1.2 trillion in wealth was wiped out in the bond market last week as yields soared in response to the Trump victory. The yield on Treasuries increased by 37 basis points last week. Bonds are reacting to (a) the potential inflation from a big infrastructure spending program, and (b) the potential for reduced trade and increased protectionism. Yields are now at highs we haven’t seen since January.

Richmond Fed President Jeff Lacker said that if Trump enacts a large fiscal stimulus plan, it might cause the Fed to move faster than the markets anticipate. Lacker will be a voting member in 2018.

One of the first jobs the new administration will tackle is to reform Dodd-Frank. The biggest piece of that will be to reform the CFPB, by making it subject to the Congressional appropriation process and to replace a single director with a bipartisan board. Banking stocks have been rallying since the election. Other rules would center around capital requirements and stress tests, which would mainly affect the smaller banks that don’t have massive derivatives portfolios or international operations, in an attempt to ease the regulatory burden on them. Democrats might attempt to filibuster any reform if it goes too far, but there probably is enough common ground in the Senate to make some sort of reform possible.

Could Donald Trump end up facing the nemesis of Bill Clinton’s first administration – the bond vigilante? Certainly if you take his promises at face value: a big uptick in spending with a massive tax cut, then you might see the creature that has been in hibernation since the early 90s resurface.

Morning Report: Will the late teens resemble the early 80s? 11/10/16

Vital Statistics:

Last Change
S&P Futures 2167.5 7.0
Eurostoxx Index 340.7 0.9
Oil (WTI) 44.9 -0.3
US dollar index 89.3 0.4
10 Year Govt Bond Yield 2.09%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.75

Stocks are higher this morning as the markets come to grips with a Trump presidency. Bonds and MBS are down.

Strangely, the 2 year bond is trading at 90 basis points, while the consensus is that we should be getting 2 more rate hikes by late 2018. This is even more surprising given the action in the 10 year. A poll of economists and strategists indicates that the Fed will still raise rates in December. Given the market action since Trump won, the Fed has every excuse to do so.

Trump will not ask for Janet Yellen’s resignation. That said, she probably won’t get re-nominated when her term expires in 2018. Donald Trump has been critical of Fed policy, insisting that rates should be higher than where they are now.

After an appeals court ruling, President Trump could fire CFPB Director Richard Cordray.

Mortgage Applications fell 1.2% last week as purchases rose 1% and refis fell 3%. The average interest rate for a 30 year fixed conforming mortgage rose 2 basis points to 3.77%.

Initial Jobless Claims fell to 254k last week as employers continue to hang onto their workers.

The conventional wisdom that a Trump victory would be stock bearish, bond bullish, and dollar bearish turned out to be dead wrong, at least initially. Stocks were destroyed in the wee hours of Wednesday morning, and then had a massive turnaround during the day. Legendary investor Carl Icahn probably singlehandedly cleaned up the sellers overnight, pouring $1 billion into S&P 500 futures. He was probably up about 6% on that trade by noon.

The overall feel to the tape is “risk on” and investors are definitely selling bonds to buy stocks. Financials, Pharma, and construction stocks led the charge. Surprisingly the homebuilder ETF (XHB) underperformed. Ultimately a Trump presidency should be bullish for housing, so I am surprised at the stock action.

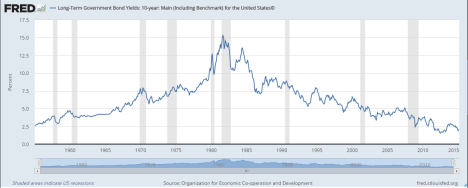
The more I think about it, the more I believe the Trump presidency will most closely resemble the early Reagan Administration economically. Reagan took over after a long period of economic underperformance and shocks to the economy. Early in his administration, the Fed was tightening while fiscal policy loosened. I think that dynamic is going to play out here, as the government cuts taxes, deregulates, and spends on infrastructure while the Fed methodically raises interest rates off the zero bound. Ultimately the Fed has an easier job here, as they don’t have the raging inflation problem and any recession will probably be more mild since we are already at full employment. I don’t see a deep recession like 81-82 in the cards, however we are certainly in uncharted territory with monetary policy worldwide. The biggest difference is that that the early 80s ended a secular bear market in bonds that began in the 50s. This time around, we are ending a secular bull market in bonds that started in the early 80s. Note that we are also probably at the beginning of a secular bull market in stocks, just like the early 80s.

10 year long term.PNG

The Lessons To Be Learned from This Election – 11/09/16

trumpup

First, a disconsolate victory lap for the predictions I got right. I believed Trump would take Florida, and he did. I believed he could win the election, although as election night neared I decided he would not. So, I ultimately was swayed by the polls and my general sense of his awfulness as a candidate. So I was mostly wrong, but at least I foresaw the possibility that he would win.

I warned a few very cocky liberals and Democrats at the Plum Line to be careful what they wish for. During the Republican primary, they were talking about crossing party lines, even temporarily registering as Republicans to vote for Trump. They were excited about the possibility of Trump being the nominee, because he was clearly the most easily defeat-able Republican.

No small number of liberals helped Trump to win the Republican nomination. Those few cases where I interacted with them, I warned them to be careful what they wished for. So, did I call that, or what? I called it when there were still 14 Republican presidential hopefuls.

It was the same thing I said during 2008, when excited Republicans were calling into Rush Limbaugh to report how they had crossed party lines and voted for Barack Obama. Tee-hee-hee! There’s just no way Barack Obama could possibly win. Limbaugh doesn’t tend to bring up his campaign to make Barack Obama the Democratic nominee in 2008, but he did it.

Be careful what you wish for. I would always recommend folks vote for what they want, not to game the system. But people will always want to be too clever by half. Human nature.

So, that’s lesson 1 (other than always listening to me, because 60% of the time I’m right all the time): be careful what you wish for. You might get it. And then keep getting it, even though you want it to stop now.

cliches

I think lesson number 2 is the demographics isn’t destiny, at least not yet.

It might be, 8 years from now or 16 years from now or 24 years from now, but not yet. The corollary lesson is: impatience is not a virtue. Demographics looks to be the critical factor in American elections in the future, but it isn’t yet, and saying “But I want it now” like Veruca Salt doesn’t make it happen.

In fact, it might end up with your candidate being determined a bad egg and getting memory-holed by a reclusive serial child-abuser disguising himself as a chocolatier.

polls

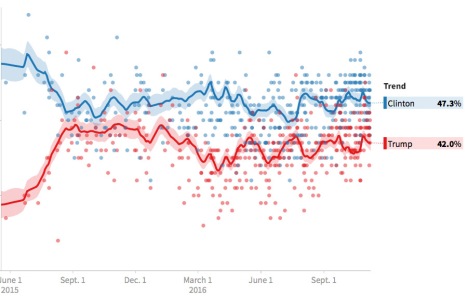
Lesson 3 is that polls are not worthless, just almost worthless.

In the lead up to the election, while Trump was complaining that the vote would be rigged, there was some interesting discussing on the Plum Line about how elections weren’t rigged, but Republicans only won when they rigged elections.

The primary example given was 2004, where exit polls predicted a clear Kerry victory, but somehow George W. Bush stole the election. Although an incumbent president who replaced a president of the opposite party almost always wins re-election. But never mind, it was stolen, because the exit polls said Kerry won. Kerry did, briefly, mull a challenge to the results based on those exit polls.

But the problem wasn’t that Bush stole the election, the problem was that the exit polling was bad. This time, almost all the polling was off. The polls captured growing momentum as election night neared, but in no way captured the scale of Trump’s electoral victory.

Another way to restate this lesson: don’t trust the polls.


dkh

Lesson 4 is a lesson for both parties and political sides, but I think it’s particularly applicable to the Democrats and liberals in this cycle: name calling is fine, if it’s your opponent or common enemies of the people. It’s bad when it’s potential voters.

Making everyone who disagrees with you into a hopeless racist sexist bigot homophobe beyond redemption is a losing strategy. And will continue to do so, until demographics finally do become destiny. Until then, insisting there is no reason not to call a spade a spade, and you will, in principle, stand tall and strong and call everyone who doesn’t agree with you a Nazi, is not a winning strategy.

There is a deeper dive into the risks of playing identity politics that could and should be had, but that’s a future lesson.

Insulting the voters also applies to the Republicans, of course, but I think it’s pretty clear who had the lower opinion of rural folks, flyover country, and middle-town America in this election. Not to mention what Democrats apparently think of folks south of the Mason-Dixon line.

sara-palin1

Lesson 5 is mostly for the Democrats: when playing identity politics, stick with race, not gender. An important part of identity politics ultimately has to be that the candidate reflects the identity of the class of people you want to vote for you. Ergo, Obama was a successful candidate in terms of identity politics. He got African-Americans to turn out and vote Democrat in unprecedented numbers and, importantly, vote for him specifically.

Hillary was unable to do that with women, and I’m not sure any woman could. Could Sarah Palin? Carly Fiorina? I don’t think so. Not every potential grouping of humanity is susceptible to identity politics-style appeals. Whichever woman finally does become president, in other words, it’s not going to be because she is a woman and “it’s time”.


george-soros

Lesson 5? Money doesn’t buy electoral victories.

This will be lost on most of the left, I expect, but it’s simply true. Demonstrated repeatedly. Donald Trump didn’t spend as much as Clinton. His supporters didn’t spend as much on him as Romney’s did on their candidate. The PACs weren’t as flush with cash. Jeb! Bush had far more money, and spent far more money, in the primaries than Trump, and went nowhere. Meddlesome billionaires poured cash into the election, and not just in ads, but into support networks and astroturfing and on and on. The result? Rich jerk who occasionally said positive things about the working class, and actually would do a little fighting for them, sort of, won the election. Oligarchs who plowed money into the election like their lives depended on it lost.

As corollary, I would say another lesson, to be learned or ignored, is this: in a democracy, the elites and oligarchs ignore the proletariat and the common man at their peril.

giphy

Lesson 6? Presidential debates just aren’t that important.

Might be becoming less important as time goes on. Neither performed that well but Trump was generally seen as the loser. My own observations were that he did not come off as presidential, and sometimes not even as competent. He missed obvious opportunities, was not articulate, and mostly HRC more than held her own against him. Ultimately, none of that seemed to matter that much.


Predictions now?

  1. Hillary will not go to jail, despite Trump’s implying that she’d be in jail under a Trump presidency.
  2. There will be more turn over in the Trump cabinet than is typical. This may not be a bad thing.
  3. Deportation will become self-deportation, perhaps a beefing up of e-Verify.
  4. There will be no wall.
  5. He will urge the house to repeal ObamaCare. It will become something similar with a different name. I don’t believe pre-existing condition coverage will be going anywhere. Now that the Republicans control everything, Obamacare will cease to be a huge issue.
  6. Many on the left will rend their garments and tear out their hair, predicting that abortion will be outlawed, all Mexicans forcibly deported, Muslims shot on site at airports, etc. None of this will happen, but nobody will be called out on their crazy predictions.
  7. Democrats will continue to make a serious push for an end to the electoral college, especially if they get the house or the senate in midterms, but will make no headway.
  8. The filibuster, if used much, will get the nuclear option. For reals, this time.
  9. And, my far out prediction? Trump puts some fairly well-known Democrats in his cabinet, and maybe plays identity politics (minorities edition) with some of his choices.
  10. And, along with that, keep in mind that Trump is less partisan than he is Trumptastic. He will continue to make enemies amongst Republicans and Democrats. It won’t matter, he’ll still win re-election in another close race in 2020.

Morning Report: The unthinkable just happened 11/9/16

Vital Statistics:

Last Change
S&P Futures 2134.5 -4.0
Eurostoxx Index 333.0 -2.0
Oil (WTI) 44.8 -0.2
US dollar index 88.3 0.3
10 Year Govt Bond Yield 1.96%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.61

Stocks are bonds are down after Republicans ran the table last night. Volatility will be the rule of the day.

Republicans ran the table. House, Senate, and Presidency. Obviously the conventional wisdom was dead wrong.

Bonds are down surprisingly, given how they were behaving in the early Asian sessions. As a Trump victory was looking more and more likely, bond yields were falling (having hit a low of 1.72% at one point). Just after midnight, the rally reversed, and bonds sold off to where yields hit 1.96%. Interestingly, the 2 year has rallied to 71 basis points or so and has now sold off to 83 bps. So people got whipsawed big time overnight, which means we should expect some volatility in rates going forward. Volatility tends to beget volatility. Be careful with your locks.

Stocks were initially slammed on the result as well, with the S&P 500 futures down over 120 points. That has since turned around and we are looking at modest losses. Just another day at the office for the markets.

Obviously, no one saw this coming, and a lot of people are wondering what a Trump presidency means to markets. First of all, I think fears that Ted Nugent would be running Homeland Security and Jesse the Body Ventura would be running Treasury are overblown. A lot of the serious candidates who would be good choices were not in the mix for consideration because they didn’t take Trump’s candidacy seriously. That will now change, however I think we will probably see a few outsiders: guys like ex-GE CEO Jack Welch, KKR head Henry Kravis, or Carl Icahn. VP Mike Pence will have a much bigger role than a traditional VP.

Trump’s model would be Ronald Reagan, which was probably the best comparison. Reagan was scoffed at by the elites: he was an actor, went to *snicker* Eureka College, was from the land of fruits and nuts, however he beat the brainiac Jimmy Carter who the establishment liked a lot. Reagan however surrounded himself with the best of the best and brightest of the conservative movement and became a successful president. Reagan was not a detail guy either. For Trump, it all comes down to his personnel who will handle the heavy lifting while Trump points in the general direction where he wants things to go. He doesn’t have the knowledge base to get all that involved in the nitty-gritty of policy-making. All of that said, the people who worry that he is Benito Mussolini II (actually I think the better comparison is Silvio Berlusconi) forget that people change, but the US system of government doesn’t. It was designed specifically to make it impossible for a dictator to make it work. He is going to be way more restricted in what he can actually do than the left fears.

I would suspect this morning a lot of market pros are googling Donald Trump’s economic policy. He has generally been all over the place. I think he will be more financial sector friendly than Obama was. He has trashed Dodd-Frank a number of times, and I suspect that D-F will get tweaked legislatively, with the goal of providing market participants more certainty into what the rules of the road are. Provided he does this right, it could help bring back the private label securitization market, which has been largely dormant with the exception of highly overcollateralized jumbo securities. Given the thin ice that the CFPB is on Constitutionally (and now a conservative replacement for Scalia on the Supreme Court), the agency might be pulled back onto the reservation.

Trump has been all over the board with respect to tax policy. He once advocated for a wealth tax, which even FDR couldn’t stomach. Now, he wants to eliminate the estate tax, cut corporate taxes and flatten the income tax code. Corporate tax reform is ripe as both parties agree we need to do something. Carried Interest could probably go by the wayside as a bargaining chip with the left.

Donald Trump has also been critical of the Fed, and he probably will nominate a more hawkish Chair than Janet Yellen, however her term expires in late 2018 so this isn’t a front-burner issue. The action in the 2 year suggests the markets are handicapping a lower chance of a hike at the December meeting. IMO, the Fed will do what it usually does: take a cue from the behavior of the markets.

Here is what Trump might do for housing finance reform. Punch line: Housing finance reform simply isn’t going to be a front-burner issue. It wasn’t really discussed by either party during the campaign, and the current system might not be ideal, but at least it isn’t a problem.

With respect to foreign policy, remember that Barack Obama ran as the ant-GWB. He would end the wars in the Middle East, close Guantanamo Bay, and build on our alliances in Europe. After all was said and done, he pretty much continued to do what GWB was doing. Trump will have the same constraints, especially in trade.