Morning Report: LEI shows strong growth ahead 7/19/18

Vital Statistics:

Last Change
S&P futures 2808 -8.25
Eurostoxx index 386.86 -18
Oil (WTI) 68.23 -0.53
10 Year Government Bond Yield 2.87%
30 Year fixed rate mortgage 4.51%

Stocks are lower as earnings continue to come in. Bonds and MBS are down.

Initial Jobless Claims fell to 207,000 last week, which is the lowest level since 1969. Despite the tightness of the labor market, wage growth is tough to come by.

I have discussed at length the disconnect between the Northeast and the rest of the country when it comes to the real estate market. It turns out that not only does the real estate market lag, so does mortgage banking. Last year was a rough year for mortgage banking, and the typical profit per loan was about 31 basis points. That varied by region, with the Midwest in the lead at 39 basis points while the Northeast lagged at 8.

The Fed’s Beige Book characterized the economy as strong, and said that labor shortages are beginning to impede growth. Engineers, skilled construction workers, truck drivers, and IT professionals are in short supply. So far increasing input prices are not translating into higher inflation – corporate margins are taking the hit. Residential housing continues to improve ever so slowly, and commercial real estate is flat. Overall, the picture points to a strong economy, with room to run. The lack of pricing pressures gives the Fed the leeway to go slow as they get off the zero bound.

The Conference Board echoed this assessment, with the Index of Leading Economic Indicators increasing 0.5% in June. The LEI is still rising faster than the CEI (basically the future indicators are showing that growth should accelerate) which means we have no sign of a slowdown.

Kathy Kraninger, the Administration’s nominee to run the CFPB, will appear before the Senate Banking Committee today. Little is known about her views on financial regulation. Congressional aides have said that she will have enough support to pass the Committee on a party-line vote. In her prepared remarks, she said she will continue Mick Mulvaney’s work of balancing the need for consumer protection with the need to treat the financial sector fairly. Suffice it to say, having come from OBM, she doesn’t really fit the type of bureaucrat who would normally be tapped to run the CFPB, and that may be the point. If her nomination bogs down, Mick Mulvaney can continue to run the agency.

Interesting stat: 70% of the Millennials who own a home have buyer’s remorse. Many used their retirement savings to fund the down payment, which is generally a bad move. Many first time home buyers completely underestimate closing costs as well. Others underestimated the costs of upkeep, which is around $16,000 a year. I suspect many of these lessons are learned by every generation who buys their first home.

The CoreLogic Mortgage Fraud Risk Index rose 12% in the second quarter compared to a year ago. An increase in borrowers taking on loans for multiple properties (i.e more professional investors) appeared to drive the increase.

Morning Report: Average wages growing faster than median wages 7/18/18

Vital Statistics:

Last Change
S&P futures 2808 -2.5
Eurostoxx index 386.74 1.76
Oil (WTI) 67.62 -0.46
10 Year Government Bond Yield 2.85%
30 Year fixed rate mortgage 4.51%

Stocks are lower this morning on no real news. Bonds and MBS are flat.

Mortgage Applications fell 2.5% last week as purchases fell 5% and refis rose 2%. The refi share rose to 36.5%.

Housing starts hit their lowest level since September last year, falling to 1.17 million annualized. This is a huge drop from the strong May print of 1.33 million. The Midwest and the South explain the declines, which was both in single family and multi. June weather was generally good, so that isn’t the explanation. Building Permits fell as well, although not as dramatically. They came in at 1.27 million. The Midwest accounted for most of the decline in permits. Housing starts tend to be volatile, but the moving average is turning down, which is worrisome.

Despite the drop in starts, builder confidence remains strong, at least according to the NAHB. The index was flat at 68, which is an elevated number. Pricing remains strong, but the supply is not there. Rising material costs are becoming an issue as lumber tariffs raise costs. So far builders are able to pass these costs on, but there is a limit, especially if wage inflation remains below house price inflation. The median house price to median income ratio is getting back to extreme levels, and interest rates are not going to come to the rescue this time around.

Jerome Powell begins his second day of testimony on Capitol Hill. There was nothing market-moving yesterday, so expect more of the same. Yesterday, his message was that the US economy has clear sailing ahead with strong growth and moderate inflation. With regard to the potential trade war, Powell downplayed the risks to the economy and said there will be a benefit if it turns out that Trump’s actions lower tariffs overall in the global economy. The US generally has much lower tariffs than its trading partners, and Trump has already made the offer to eliminate all US tariffs if our trading partners eliminate theirs. Separately, Powell said that it would ultimately be better for the US if the GSEs were off the government balance sheet. That is pretty much a universal opinion in DC these days, as the US taxpayer bears the credit risk of the majority of the mortgage market.

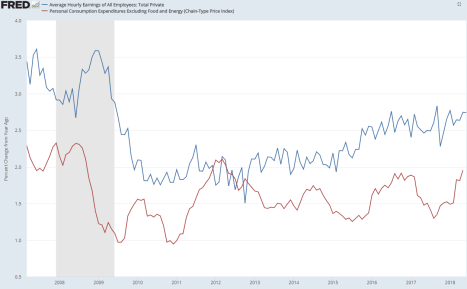
Median weekly earnings have not kept pace with the CPI lately, which means workers are losing ground, at least according to the latest survey out of the BLS. It shows that the median weekly wage rose 2% in the second quarter versus an increase in the CPI of 2.7%. Interestingly, the average hourly earnings increase during Q2 was 2.64% in April, 2.74% in May and 2.74% in June. It seems strange that the difference between average wage inflation and median wage inflation would be so stark, which would imply that wages are mainly rising at the high end, not the lower end. Note the other BLS measure of wage inflation, the employment cost index, shows comp growth of 2.9%, which takes into account benefits. For the most part, average hourly earnings have been rising faster than the core PCE index:

AHE vs PCE

New York, Connecticut, New Jersey, and Maryland sued the government yesterday over the state and local tax deduction cap. The lawsuit if probably more for show than anything and doesn’t seem to have much chance of success. Some of the states are looking at workarounds, allowing people to “donate” to charitable funds which go to funding state and local services. Charitable deductions are still deductible. At the end of the day, the biggest issue to states like NY and NJ are the property taxes. NY and NJ have some of the highest property taxes in the country, where people routinely pay $20 – $30k or more. That explains at least partially why you can’t find buyers for luxury properties in the Northeast.

The ECB concludes that QE may have helped the rich, but it helped the poor more. While QE did boost asset prices (housing, bonds, stocks etc) it also boosted growth, which more than offset the increase in asset prices.  “Low short rates do hurt savers via a direct effect, that is a reduction in income on their assets . . . however [low rates] also benefit savers, like all other households, via an indirect effect — that is, the reduction in their unemployment rate and the increase in the labour income,” the paper, called “Monetary policy and household inequality”, said. “The indirect effect dominates . . . The paper also finds that [QE] reduced inequality, mainly through a reduction of the unemployment rate of poorer households.”

Note that this contradicts the observation between median and average earnings. If QE was actually decreasing inequality, you should see median earnings growth close to average earning growth or even slightly higher. Not way below.

Morning Report: Building Permits in the Northeast struggle 7/17/18

Vital Statistics:

Last Change
S&P futures 2794 -2.5
Eurostoxx index 383.01 -1.04
Oil (WTI) 68.12 0.06
10 Year Government Bond Yield 2.85%
30 Year fixed rate mortgage 4.51%

Stocks are lower after Netflix (one of the FAANG leaders of the market) missed earnings. Bonds and MBS are flat.

Industrial Production rebounded in June by 0.6% and manufacturing production increased 0.8%. Capacity utilization is 78%.

Jerome Powell heads to Capitol Hill today to begin his semiannual testimony in front of Congress. Expect a lot of questions regarding wage growth, trade wars, and regulation. Overall, he is expected to say that the economy is in good shape overall with above-trend growth and a strong labor market. He will face some questions from Democrats on regulation, especially since the Fed approved Goldman and Morgan Stanley’s capital plans despite the fact they were technically failed their stress tests. The Fed Funds futures continue to move in a hawkish direction, with the Sep futures pricing in a 88% chance of a hike and the Dec futures pricing in a 63% chance of 2 hikes.

Despite trade tensions, the IMF still expects the global economy to grow 3.9% this year and next. Trade remains a threat, however the impact is relatively small: a decrease of 0.5% in global growth by 2020. They forecast the US economy will grow 2.9% this year. Note many strategists took up their Q2 numbers on the strong retail sales print yesterday.

The Fifth Court of Appeals ruled yesterday that the structure of the FHFA is unconstitutional. Not sure how that is going to play out. Separately it also ruled that the FHFA was within its authority to sweep the profit from the GSEs, which is bad news for shareholders. FNMA stock was hit to the tune of 6% after the ruling.

The difference in sentiment between Northeastern real estate markets and the West is night and day. Growth in single family permits was actually negative for the first 5 months of this year. Compare that to the West, where they are up almost 18%.

The Northeast still has yet to really recover from the Great Recession, although some of that has more to do with secular trends in banking and the securities industry than it does with the real estate bubble. The securities industry has been hit by secular trends (falling commissions, ETFs) that have been great for investors but not great for employment in the industry. 5 cent commissions and 2%/20% hedge fund fees supported a lot of jobs which supported a lot of $1MM + homes. Towns like New Canaan have banned For Sale signs and the only part of the real estate market that is moving is in the sub-$750k segment. Million dollar plus listings languish. It is amazing – we have a housing shortage in the US overall, but you would never know that if you looked at the NYC suburbs.

Morning Report: Empire State outlook dims 7/16/18

Vital Statistics:

Last Change
S&P futures 2802 -1
Eurostoxx index 383.92 -1.14
Oil (WTI) 69.81 -1.2
10 Year Government Bond Yield 2.84%
30 Year fixed rate mortgage 4.50%

Markets are flattish as earnings season gets into full swing. Bonds and MBS are flat.

Oil is dropping after US Treasury Secretary Steve Mnuchin said the US could waive some Iranian oil sanctions.

Bank of America reported decent earnings this morning. This is a big week for earnings, with about 200 major companies reporting. The early part of reporting season is generally dominated by the banks.

Jerome Powell will testify in front of Congress on Tuesday and Wednesday. Generally these events don’t yield much in the way of useful info – they are mainly for the benefit of politicians who want to draw attention to some issue that may or may not relate to monetary policy. Expect a lot of questions regarding how a trade war and income inequality will affect growth from Democrats, and expect a lot of questions regarding regulation from Republicans. The prepared remarks are here.

Retail Sales rose 0.5% in June, which was in line with expectations. Ex-autos and gas they rose 0.3% while the control group was flat. May numbers were revised upward. The control group was below expectations, but with the May revisions offset that. Discretionary items (clothing, sporting goods, department stores) declined, which building materials and furnishings rose.

Business Inventories rose 0.4% in May. The inventory-to-sales ratio is down to 1.34 from 1.39 last year.

Business activity in New York State exhibited continued strength in June, according to the New York Fed’s Empire State Manufacturing Survey. While the current conditions index exhibited strength, the outlook has slipped. The survey doesn’t say whether this is being driven by a potential trade war or something else. Planned capital expenditures (a proxy for expansion plans) decreased.

The Atlanta Fed took up their Q2 GDP estimate to 3.9%. Morgan Stanley warns that we are seeing a bit of a sugar rush in the economy courtesy of trade tensions. As companies worry about a potential trade war, they stockpile raw materials and other inputs. This gooses the inventory numbers which makes the current quarter look particularly strong. The problem is that you get a double whammy if the trade war materializes. Activity will drop, and that inventory will be liquidated, both of which will reduce GDP growth. Even if a trade war doesn’t happen, uncertainty could cause companies to pull in their horns. FWIW, I am skeptical of the “uncertainty” argument. Regulatory “uncertainty” out of DC generally causes companies to be cautious. The rest of the clatter is just noise. Certainly investors (judging by the S&P 500) aren’t worried.

One stat to watch: Corporate bond spreads. We are seeing a slight widening in some of the junkier investment grade debt. Baa spreads increased to 200 basis points from 165 in February. While spreads are still tight relative to historic levels, this is something to watch. Years of financial repression have given issuers the upper hand with regards to covenants and some of those chickens will come home to roost in the next recession.

Morning Report: Bank earnings pour in 7/13/18

Vital Statistics:

Last Change
S&P futures 2797 -1
Eurostoxx index 385.18 0.81
Oil (WTI) 70.6 0.27
10 Year Government Bond Yield 2.84%
30 Year fixed rate mortgage 4.53%

Markets are flat as bank earnings come in. Bonds and MBS are up small. Slow news day.

The US government held a reasonably strong auction yesterday, where primary dealers took down their smallest positions ever. Meanwhile, speculative shorts in Treasuries (one of the biggest trades on the Street) are struggling as rates stay stubbornly low. Some continue to warn that the flattening yield curve is really telling us that a recession is around the corner.

The prepared remarks for Jerome Powell’s semiannual report to Congress should be out today. Probably won’t be market-moving, but you never know.

Import prices fell 0.4% in June as petroleum and food prices fell. For the year, they are up 4.3% however.

Consumer sentiment fell according to the University of Michigan / Reuters survey. The current conditions index drove the fall, which is usually a function of gas prices. Trade fears also weighed on sentiment.

Wells Fargo reported earnings this morning. Earnings were down due to a tax charge. Stripping out the tax charge, they were flat. They had a tough quarter for mortgages like everyone else. Origination for the quarter was $50 billion, which is up seasonally from Q1, but down 11% YOY. The current pipeline of $24 billion is down 26% YOY. Margins were 77 basis points, which is down 17 from the prior quarter and down 47 bps from a year ago. The stock is down 3% pre-open.

JP Morgan had a similar story to Wells. They originated $23.7 billion in mortgages during Q2, which was higher seasonally and down about 10% from a year ago. Mortgage banking revenue (which includes servicing) was down 6% YOY. Margin compression again was the story, especially in correspondent lending. They marked up the MSR book. JPM is flat pre-open.

A bunch of other banks reported this morning and the whole sector is getting hit, with the XLF down about a percent and a half.

Federal Reserve Chairman Jerome Powell made positive comments about the economy, although he is concerned about trade and the effects of a long trade war with China. He is concerned about rising trade tensions, although he notes that Trump’s goal is to get others to lower their tariffs. If he succeeds in that, then the trade tension would be a good thing, not a bad thing. It is important to remember that China’s biggest weapon against the US is not imposing tariffs on US goods – it is ignoring US intellectual property laws. Those sorts of things will not really show up in the balance of trade numbers, but will have huge effects on IP firms, particularly media and software.

Morning Report: The Fed is looking for new recessionary indicators 7/12/18

Vital Statistics:

Last Change
S&P futures 2790 16
Eurostoxx index 384.01 2.61
Oil (WTI) 70.92 0.54
10 Year Government Bond Yield 2.86%
30 Year fixed rate mortgage 4.53%

Stocks are higher after China made some conciliatory comments regarding the trade situation. Bonds and MBS are flat.

Inflation at the consumer level remains under control, with the consumer price index rising 0.2% MOM / 2.9% YOY. Ex-food and energy it rose 0.2% / 2.3%. These numbers were more or less in line with Street expectations. Energy, especially petroleum drove the increase in the index. Housing also pushed up the index, while autos and utilities exerted downward pressure.

Initial Jobless Claims fell to 214,000 last week, which is at levels we haven’t seen since the early 1970s (when we had a draft).

Loan performance continues to improve, according to CoreLogic. The 30+ DQ rate fell from 4.8% to 4.2% in April. DQ rates are near historic lows, except for FL, TX, and LA which are still dealing with the fallout from Hurricane Harvey. The national foreclosure rate fell by 10 basis points to 0.6%. Home price appreciation of 7% is helping matters. In fact, home equity is increasing rapidly, but HELOC are not.

As the 2s-10s spread decreases, many in the financial press are worrying whether the slope of the yield curve is signalling a recession. We already have some strategists calling for the yield curve to invert sometime in 2019. An inverted yield curve (where short term rates are higher than long term rates) has historically been a strong recessionary signal. As a general rule, the yield curve flattens during tightening cycles. In fact, it did invert in the late 90s (before the stock market bubble burst) and during the real estate bubble (before the Great Recession).

Recent Fed research indicates the 2s-10s spread may not be the best signal of an upcoming recession. It suggests the spread between the 3 month T bills and 18 month Treasuries could be more predictive. Another signal is the Eurodollar futures market. The idea is that the Fed would use these indicators as a yellow signal and stop tightening before they risk a recession.

To me at least, the last two recessions had very little to do with the Fed. We had a stock market bubble, and we had a residential real estate bubble. To say the Fed caused those recessions implies that these bubbles would have kept on going had the Fed just stayed away (or stopped tightening sooner). That is a big assumption – all bubbles eventually come to an end, and when they do you have a recession. The tightening may have been the catalyst to initiate the recession, that is a question of “when,” not “if.” We were going to have a recession given we had a bubble in place already. And the Fed might have been guilty of causing the bubble in the first place, but that is a separate question.

Of course, all bets are off when it comes to this yield curve versus the past. The size of the Fed’s balance sheet relative to the economy is vastly different this time around. Pre-Great Recession, the Fed had about $800 billion worth of assets. Now it is about $4.4 trillion. To draw comparisons, you would have to estimate where the 10 year would have been without Operation Twist, QE1, QE2, and QE3. Punch line, the yield curve may in fact invert if the Fed continues to tighten and inflation remains under control. The signal-to-noise ratio of the yield curve is extremely low, so take it with a grain of salt.

Morning Report: Quits rate jumps in May 7/11/18

Vital Statistics:

Last Change
S&P futures 2781 -11
Eurostoxx index 382.05 -4.2
Oil (WTI) 73.29 -0.82
10 Year Government Bond Yield 2.85%
30 Year fixed rate mortgage 4.53%

Stocks are lower this morning after Trump threatened tariffs on $200 billion worth of Chinese goods. Bonds and MBS are flat.

China has vowed to retaliate if the Trump Administration follows through on its threat to impose 10% tariffs on about $200 billion worth of Chinese goods. Since China imports far less than $200 billion from the US, they may have to come up with other measures to retaliate – anything from denying visas to limiting tourism and increasing regulatory measures. Strategists are beginning to warn that the trade war could derail the recovery.

Inflation at the wholesale level increased in June, according to the PPI. The headline number rose 0.3% MOM / 3.4% YOY. Ex food and energy, it was up 0.3% / 2.8% and ex food energy and trade services 0.3% / 2.7%. Services and motor vehicles drove the increase.

Donald Trump nominated Brett Kavanaugh to the Supreme Court yesterday. He is generally a regulatory skeptic, and has ruled against overreach in the past. He has already weighed in on the CFPB, which he believes is unconstitutional. From CFPB vs PHH, writing for the majority: “The CFPB’s concentration of enormous executive power in a single, unaccountable, unchecked Director not only departs from settled historical practice, but also poses a far greater risk of arbitrary decision-making and abuse of power, and a far greater threat to individual liberty, than does a multi-member independent agency. The overarching constitutional concern with independent agencies is that the agencies are unchecked by the president, the official who is accountable to the people and who is responsible under Article II for the exercise of executive power.” That said, Kennedy was already considered a vote against the CFPB, so the nomination won’t move the needle there.

Kavanaugh has also ruled against the EPA, which generally ignored the “cost” side of the “cost / benefit” analysis of regulations during the Obama Administration. Overall the regulatory environment for the financial industry could get a little easier with Kavanaugh on the Court.

Speaking of the CFPB, Brian Johnson has been tapped to be the #2 of the agency. He replaces Leandra English, who resigned last week.

Small business optimism remains elevated despite trade concerns, according to the NFIB Small Business Optimism Survey.  Employment continues to grow, with 1 in 5 firms adding employees in June on net. Sales are up overall, but margins appear to be facing pressure from higher labor and input prices. Credit needs are being fully met.

Job openings fell to 6.6 million in May, which was just off the record high of 6.8 million set in April. Hires were strong at 5.8 million, led by health care and social assistance. The big number was the quits rate, which is one of the best leading indicators of wage inflation. It rose to 2.4%.

The big question remains: how much slack is there really in the labor market? Most of the official numbers imply there is none. Yet, there is only modest wage inflation. I suspect the employment-population ratio tells the real story, and that number has yet to really recover from the Great Recession. Demographics are part of the story, but as people work longer, the assumption of 65 = retirement might have to change. I suspect many of those who are retired would gladly take a job if offered.

For the construction sector, the number of unfilled jobs hit a record high. That sector has been facing labor constraints for quite some time, and this partially explains why housing starts have been so far below what is needed to meet demand.

Mortgage Applications increased 2.5% last week as purchases rose 7% and refis fell 4%. Last week included the 4th of July, so there are all sorts of adjustments baked into that number. Refis fell under 35%, the lowest number since August 2008. ARMS decreased to 6.3%. Overall rates fell about 3-4 basis points last week.

Meanwhile, the MBA’s mortgage credit availability index improved last month as increases in conventional and jumbo availability offset a contraction in government.

Nominee Kavanaugh

From Jonathan Adler at Volokh:


Judge Kavanaugh has served on the D.C. Circuit for twelve years. This court is often referred to as the “second-highest” court in the land because it hears the lion’s share of legal challenges to major federal regulations. Administrative law is a heavy part of the court’s docket, and forms a large part of Judge Kavanaugh’s record. In his time on the D.C. Circuit, Judge Kavanaugh has written over 200 opinions, over 100 of which concern administrative law.

Prior to serving on the D.C. Circuit, Judge Kavanaugh was a partner at Kirkland & Ellis, worked in the Bush White House, and for Independent Counsel Kenneth Starr. He clerked for Anthony Kennedy, as well as for two circuit court judges. There is no question about his qualifications for this nomination.

Attention will now turn to Judge Kavanaugh’s judicial opinions and other writings. Aaron Nielson has a summary of Judge Kavanaugh’s concurrences and dissents at the Notice & Comment blog. Going beyond Kavanaugh’s opinions, here are some other writings. Here’s a lecture Judge Kavanaugh gave at CWRU on the D.C. Circuit at the Case Western Reserve University School of Law. A published version of the lecture is here. Here is Minnesota Law Review article on the separation powers and here is Harvard Law Review piece on statutory interpretation.

Here are some additional thoughts on the Kavanaugh nomination:

  • Judge Kavanaugh is widely respected on the Supreme Court. Many of his clerks go on to clerk at One First Street. More importantly, his opinions attract notice from the justices. Several of his dissents have been vindicated by subsequent Supreme Court decisions. His dissents showed the way for the Court in Michigan v. EPA (White Stallion Energy Center v. EPA concerning mercury emissions), UARG v. EPA (CRR v. EPA concerning GHG emissions), Free Enterprise Fund v. PCAOB (concerning separation of powers), and D.C. v. Wesby (concerning qualified immunity). And even when certiorari was granted, Judge Kavanaugh’s dissents have been noted in subsequent Supreme Court cases (as in Lexmark International v. Static Control Components which favorably cited Kavanaugh’s dissent in Grocery Manufacturers Association v. EPA). This suggests other justices will take the new junior justice’s opinions quite seriously, especially on administrative law.
  • Judge Kavanaugh takes administrative law very seriously, and he makes agencies do their homework. As much as any other judge on the D.C. Circuit, he makes sure that agencies act within the scope of the authority they have been delegated by Congress, that they follow the procedures required by the APA, and that the adequately justify their decisions. This has often led to decisions invalidating agency action — both in challenges brought by supporters and opponents of regulation — but Judge Kavanaugh is not an anti-regulatory zealot. Where agencies play by the rules, he has upheld their actions against legal challenge, even where the actions in question may seem unreasonable or unfair (as when he rejected challenges to surface coal mining regulations).
  • Judge Kavanaugh shares the Chief Justice’s belief that there is a “major questions” exception to Chevron deference. In the challenge to the FCC’s “net neutrality” rule, Judge Kavanaugh echoed the Chief Justice’s admonition that courts should not lightly presume that Congress has delegated agencies broad regulatory authority if Congress never actually said so in the underlying statutory provisions.
  • Judge Kavanaugh takes separation of powers seriously, as can be seen in his dissenting opinions arguing that the structure of the Public Company Accounting Oversight Board (PCAOB) and the Consumer Financial Protection Bureau (CFPB) are unconstitutional. The former of these opinions was subsequently vindicated by the Supreme Court.
  • Like his former boss, Justice Kennedy, Judge Kavanaugh has a broad understanding of the freedom of speech protected by the First Amendment, including commercial speech. This is most noticeable from his separate opinion concurring in the judgment in American Meat Institute v. USDA. In this opinion, he showed a sophisticated understanding of how to reconcile various cases concerning commercial speech regulation and compelled commercial speech (an understanding better than that of the court’s majority, as I noted here).
  • Judge Kavanaugh’s views of executive power may depart from those of Justice Kennedy. Whereas Justice Kennedy voted with the Court’s liberals in support of habeas petitions filed by enemy combatants in the Boumediene case, Judge Kavanaugh has interpreted this precedent quite narrowly, and may be unlikely to follow his former justice’s lead. On the other hand, Justice Kennedy was himself highly supportive of executive power in many national security and foreign affairs cases, voting in support of Presidential power in cases such as Hamdi v. Rumsfeld, Trump v. Hawaii, and Zivotofsky v. Kerry.
  • Judge Kavanaugh will be criticized for prior statements he has made about Presidential immunity. In the Minnesota Law Review article linked above, he suggested that a sitting President should not be subject to litigation or criminal investigation. Note, however, that this was his opinion in 2009. More importantly, he did not suggest Clinton v. Jones was wrongly decided and said explicitly that any such insulation from litigation or investigation would have to be enacted by Congress, and could not be imposed by the Courts. Many early news reports on the nomination obscure or fail to mention this fact.
  • Judge Kavanaugh’s extensive record has created an extensive paper trail. There will be lots of documents for the Senate Judiciary Committee to review — and it’s certain that Senate Democrats will seek to slow things down on that basis. On the other hand, insofar as Senate Democrats have already announced their opposition to the nomination — some even before the nomination was announced — it’s not clear why they would need more time to review the record. After all, they don’t need more time to review materials if they’ve already made up their minds.

======================================================================

I think this is a fair assessment of his writings and decisions and different from the spin the media has put on it from their various political as opposed to judicial or legal analyses.  I did read a [basically non-political] opinion of his that I found to be totally off the point of the case, and that would be the basis of my questioning of him.  There was no reason for a guy as smart as he is to miss the point of the whole litigation.  Maybe his clerk wrote his opinion, but I would want to make sure I knew he wasn’t throwing in a spanner for some personal reason.  If y’all are interested I will dig up the case.

And no, my questioning him on his politics would be limited or non-existent.  If he satisfied me on how he freaking missed the point on a simple case I would vote for him.


Morning Report: 75% of the US Treasury market is underwater 7/9/18

Vital Statistics:

Last Change
S&P futures 2773.25 10.1
Eurostoxx index 383.72 1.4
Oil (WTI) 74.01 0.21
10 Year Government Bond Yield 2.86%
30 Year fixed rate mortgage 4.50%

Stocks are higher this morning as trade war fears recede. Bonds and MBS are down.

Earnings season begins this week, with a bunch of the big banks reporting on Friday.

The biggest econ data will be the PPI and CPI on Wednesday and Thursday. For the most part it should be a quiet week.

Leandra English has resigned from the CFPB. She was the Deputy Director for Richard Cordray, and believed she should have been given the job instead of Mick Mulvaney. She sued in Court and lost. Now that Kathy Kraninger has been nominated, she is gone.

Donald Trump will announce his SCOTUS pick at 9:00 pm tonight. The favorites are Brett Kavanaugh and Thomas Hardiman.

Interesting stat: 75% of the US Treasury market trades under par. This is the highest percent ever recorded (we started measuring this in the 80s). In the past, it generally peaked around 50%, which happened at the end of Fed tightening cycles and was usually a buying opportunity. I would note that these were in the context of a secular bull market in bonds. In secular bull markets, you buy the dip. We are now in a secular bear market in bonds and that changes the dynamic.

The REO-to-Rental Trade was a big winner over the past several years. Hedge funds and pension funds bought foreclosed properties for pennies on the dollar, fixed them up and rented them out, earning high single digit returns. As home prices rise, you would think these people will start ringing the register. Turns out they are doubling down. Professional investors are buying up homes in urban areas with good schools. This is making things even tougher for the first time homebuyer who is struggling to find a starter homes. That said, it isn’t a ridiculous number – last year major investors bought 29,000 homes, which is a drop in the bucket compared to total existing home sales of 5.45 million.

Morning Report: Goldilocks jobs report and the FOMC minutes 7/6/18

Vital Statistics:

Last Change
S&P futures 2740 2
Eurostoxx index 381.23 -0.36
Oil (WTI) 42.31 -0.63
10 Year Government Bond Yield 2.82%
30 Year fixed rate mortgage 4.52%

Stocks are flattish this morning as a good jobs report offsets the new tariffs that went into effect this morning. Bonds and MBS are up.

Jobs report data dump:

  • Payrolls up 213,000 (street was looking for 190,000)
  • Unemployment rate 4% (.2% increase, street was looking for 3.8%)
  • Labor force participation rate 62.9% (.2% increase)
  • Average hourly earnings +.2% MOM / 2.7% YOY (in line with expectations)

Overall, a good report – strength in payrolls, and an increase in the labor force participation rate. The labor force increased by 600k, where the number of unemployed increased 500k and the number of employed increased 100k. Of those 500k added to the ranks of the unemployed, 200k were re-entrants to the labor force. The achilles heel (at least as far as those looking for wage growth) has been the reservoir of the long-term unemployed. This will help ease some of the labor shortage, which has been a constraint on growth. It will also raise the non-inflationary growth rate for the economy overall, which is kind of like a speed limit. For the Fed, this is a bit of a Goldilocks report – it gives them the breathing room to lift rates gradually which limits the risk of a recession.

The FOMC minutes didn’t really reveal much new information. Most pointed to the strong labor market and cited several statistics (JOLTS, unemployment rate, regional Fed surveys) to point to a tight labor market. “Several” members (i.e. a minority) thought that there was still some slack in the market as the long term unemployed are re-entering the labor market. Note this morning’s jobs report bears that out. The members also discussed the slope of the yield curve, and whether the flattening was telling them anything. Interestingly, only “some” participants thought that the Fed’s asset purchase program (i.e. QE) was affecting the shape of the yield curve, and therefore distorting the information sent from it. Kind of begs the question – if QE didn’t affect the shape of the yield curve, then what was the point? Or even more importantly, why do they still have $4.5 trillion worth of bonds on the balance sheet?

The Fed also thought about the possibility of a trade war and how that would end up slowing down the economy. They also thought that they might have to raise the Fed funds rate further than they had anticipated earlier: “With regard to the medium-term outlook for monetary policy, participants generally judged that, with the economy already very strong and inflation expected to run at 2 percent on a sustained basis over the medium term, it would likely be appropriate to continue gradually raising the target range for the federal funds rate to a setting that was at or somewhat above their estimates of its longer run level by 2019 or 2020.”

The Fed Funds futures turned slightly more hawkish on the minutes, with the probability of a Sep hike increasing from 75% to 80% and the chance of a Sep and Dec hike hitting 53%.

In other economic news, the trade deficit fell to the lowest level in 18 months. Not sure how much of that is due to tariffs already in place.

Tariffs (especially lumber) are wreaking havoc on the entry-level new housing market. Builders generally have to purchase things like land and materials up front before they build and get paid for the construction. When materials prices are artificially supported by tariffs, that increases their risks, and makes them pull back.