Posted on August 6, 2012 by Brent Nyitray
Vital Statistics:
|
Last |
Change |
Percent |
| S&P Futures |
1391.8 |
2.8 |
0.20% |
| Eurostoxx Index |
2387.0 |
14.5 |
0.61% |
| Oil (WTI) |
91.27 |
-0.1 |
-0.14% |
| LIBOR |
0.439 |
-0.001 |
-0.11% |
| US Dollar Index (DXY) |
82.35 |
-0.024 |
-0.03% |
| 10 Year Govt Bond Yield |
1.55% |
-0.02% |
|
| RPX Composite Real Estate Index |
188.1 |
0.7 |
|
Markets are slightly higher this morning on a deal to rescue Knight Capital. There are very few economic releases this week, and Europe should be quiet as we get into August. Bonds are up half a point, while MBS are up a few ticks.
As some lenders exit the correspondent business, others enter. While Bank of America and GMAC are leaving or scaling back, Redwood Trust is applying for Fan and Fred approval in order to increase their focus from just jumbo loans. Redwood Trust is the main issuer of MBS without a government guarantee.
Knight Capital received a $400MM rescue from Getco LLC. Interestingly, the rescue was put together by Knight’s customers who fear too much concentration in market makers. While the trading error that caused it will undoubtedly draw regulatory scrutiny to high-frequency trading. Maxine Waters is already looking to hold hearings on it. Wonder if they will look to the unintended consequences of Reg NMS, which basically destroyed the business model of traditional market-making. HFT is what is left. If investors don’t want to pay commissions or bid / ask spreads, they will probably have to accept the volatility that goes along with computerized trading.
Filed under: Morning Report | 95 Comments »
Posted on July 31, 2012 by Brent Nyitray
No MR this week either. Working on the West Coast and the tech gremlins aren’t cooperating. Will try later this week, but so far having too many difficulties..
Filed under: Morning Report | 1 Comment »
Posted on July 27, 2012 by markinaustin
Vital Statistics:
|
Last |
Change |
Percent |
| S&P 500 |
|
+11.54 |
+01.75% |
| Eurostoxx Index |
|
+39.44 |
+1.91% |
| Oil (WTI) |
90.01 |
0.62 |
0.69% |
| LIBOR |
0.45 |
-0.002 |
-0.41% |
| US Dollar Index (DXY) |
82.51 |
-0.31 |
-0.37% |
| 10 Year Govt Bond Yield |
1.51% |
+0.076% |
|
WaPo:
ECB chief Mario Draghi said the words that many worried European officials had longed to hear: ‘Within our mandate, the ECB is ready to do whatever it takes to preserve the euro. . . . Believe me, it will be enough,’ he said.
I apologize for the brevity – I barely had time for this.
Ezra Klein has been substituting on The Rachel Maddow Show this week and has been doing a series of short video explanations of some of the financial stuff going on lately. Here’s his one on LIBOR:
#48311494
Between this and Scott’s series I think I actually understand LIBOR and why it’s a problem if the rates were actually manipulated now.
Here’s his explanation for how and why to break up the big banks:
#48329251
And here’s his translation of this sentence from the Bloomberg site: Draghi: Yields disrupting policy transmission are in ECB remit
#48347263
Ezra has gotten better and better on-camera, and I’ve enjoyed the way he’s able to boil complex concepts down verbally now as well as “on paper.”
Michigoose’s contribution to our collective financial expertise
Filed under: Morning Report | 18 Comments »
Posted on July 25, 2012 by markinaustin
Vital Statistics:
|
Last |
Change |
Percent |
| S&P Futures |
|
|
0.01% |
| Eurostoxx Index |
|
+12.74 |
|
| Oil (WTI) |
88.51 |
0.01 |
0.01% |
| LIBOR – 3 mo |
0.45 |
– |
– |
| US Dollar Index (DXY) |
83.67 |
0.09 |
0.0% |
|
|
1.40 |
|
-.05% |
http://www.ft.com/intl/cms/s/0/72845f10-d4d2-11e1-bb88-00144feabdc0.html#axzz21e1DVBYn
I like Mallaby. However, I am dubious about this scheme, which is rumored to be a possibility come the 8-1-12 FRB meeting. The notion that pumping more cash and cash equivalents into the banking system will stimulate Main Street, yet again, seems incorrect to me.
Filed under: Morning Report | 65 Comments »
Posted on July 24, 2012 by markinaustin
Vital Statistics:
|
Last |
Change |
Percent |
| S&P Futures |
|
|
-0.12% |
| Eurostoxx Index |
|
-5.25 |
-0.24% |
| Oil (WTI) |
|
0.550 |
0.62% |
| LIBOR – 3 mo |
0.45 |
-0.01 |
-2.2% |
| US Dollar Index (DXY) |
83.76 |
0.01 |
0.0% |
| 10 Year Govt Bond Yield |
1.45% |
-.025% |
|
POLITICO reports that: In the midst of a severe drought, the House Republican leaders are proposing to walk away from farm states and decades of precedent by not calling up the new five-year plan before the current law expires Sept. 30.
Read more:
Watched Geithner on Charlie Rose last night. He speaks with certainty about the uncertain. It’s not yet internet available.
Filed under: Morning Report | 44 Comments »
Posted on July 23, 2012 by markinaustin
Vital Statistics:
|
Last |
Change |
Percent |
| S&P Futures |
1344.96 |
|
|
| Eurostoxx Index |
|
|
-2.93% |
| Oil (WTI) |
88.35 |
-3.48 |
-3.79% |
| LIBOR – 3 mo |
0.46 |
0.000 |
0.00% |
| US Dollar Index (DXY) |
83.972 |
0.494 |
0.59% |
| 10 Year Govt Bond Yield |
1.41% |
-.044% |
|
| Penn State |
$60M to child abuse prevention |
strip PSU of all wins
from ’98-
2012 |
reduce schollies; no bowls for 4 yrs |
Penn State did not get DP. NCAA violated its procedural rules, wildly, to do this, so the penalties are largely unprecedented. NCAA will probably get away with this and Penn State will probably not appeal. That is because if the sanctions are reversed on procedural grounds, as they would surely be, the NCAA would come back with a “duly processed” Death Penalty as the next step.
Filed under: Football, Morning Report | 27 Comments »
Posted on July 20, 2012 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1362.1 |
-9.8 |
-0.71% |
| Eurostoxx Index |
2258.5 |
-44.0 |
-1.91% |
| Oil (WTI) |
90.8 |
-1.9 |
-2.01% |
| LIBOR |
0.452 |
-0.001 |
-0.22% |
| US Dollar Index (DXY) |
83.29 |
0.408 |
0.49% |
| 10 Year Govt Bond Yield |
1.46% |
-0.05% |
|
| RPX Composite Real Estate Index |
184.8 |
0.0 |
|
Equity markets are weaker this morning in spite of a deal to rescue the Spanish banks and decent earnings reports out of Google and GE. There is no economic data to speak of. Bonds are up a point and MBS are up as well.
Bloomberg has a good article discussing the state of the mortgage industry and how much capacity has been drained from it. “Efforts by Obama and Bernake to help homeowners get cheaper loans and spur the economy have been slowed by lack of staff at lenders and less competition.” Fears of buyback risk are also making lenders more cautious.
SIFMA (which oversees the To-Be-Announced mortgage securities) weighs in on the eminent domain issue. They are instituting a policy that would exclude municipalities that institute eminent domain claims on mortgages from the TBA market. Without getting into the gory details, the TBA market is the way newly originated mortgages get packaged into Fannie / Freddie / Ginnie mortgage backed securities. Punch line: It will be very difficult to get a mortgage in San Bernardino because the lender will have a tougher time disposing of the loan. I am surprised at how little interest the press has shown regarding this issue.
No MR for the next week – I will be on vacation.
Filed under: Morning Report | 47 Comments »
Posted on July 19, 2012 by Brent Nyitray
Vital Statistics:
Markets are generally higher this morning on hopes of further stimulus measures and some decent earnings reports out of Ebay and IBM. Morgan Stanley missed. Spain raised 3 billion euros but paid dearly for it. Bonds are down almost a point and MBS are down a tick or two.
Initial Jobless Claims for the week of 7/14 came in at 386k, more in line with typical readings. Last week’s low 350k print was revised upwards, but still looks like a statistical fluke. Separately, it looks like another round of job cuts is on the way in the banking sector.
In other economic data, existing home sales fell by 5.4% month-on-month to an annualized pace of 4.37MM units. The Street was expecting 4.62MM. The Leading Economic Indicators index posted a negative number in June, the second negative number in 3 months.
The Philly Fed survey reported weak business conditions. Ominously, they reported declines in employment and shorter work hours.
FHA is conducting another mass distressed loan sale. Buyers will not be permitted to initiate foreclosure proceedings for 6 months. The loans are concentrated in hard hit areas like Phoenix, Tampa, Chicago, and Newark.
The Fed is considering another measure to ease up credit – allowing banks to borrow from the Fed at even lower interest rates provided the money is used to lend, not buy Treasuries. The Fed is really scraping the bottom of the barrel at this point – I guess the next step would be to allow the banks to repo the water cooler and office furniture.
Chart: Initial Jobless Claims:

Filed under: Morning Report | 15 Comments »
Posted on July 18, 2012 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1354.8 |
-3.7 |
-0.27% |
| Eurostoxx Index |
2257.6 |
6.9 |
0.31% |
| Oil (WTI) |
88.99 |
-0.2 |
-0.26% |
| LIBOR |
0.455 |
0.000 |
0.00% |
| US Dollar Index (DXY) |
83.24 |
0.210 |
0.25% |
| 10 Year Govt Bond Yield |
1.48% |
-0.03% |
|
| RPX Composite Real Estate Index |
184.5 |
0.4 |
|
Markets are a little weaker on no real news. A slew of banks reported earnings this morning, and most were better than expected. Bond yields are back below 1.5% and MBS are up slightly. The Bernank’s testimony continues today.
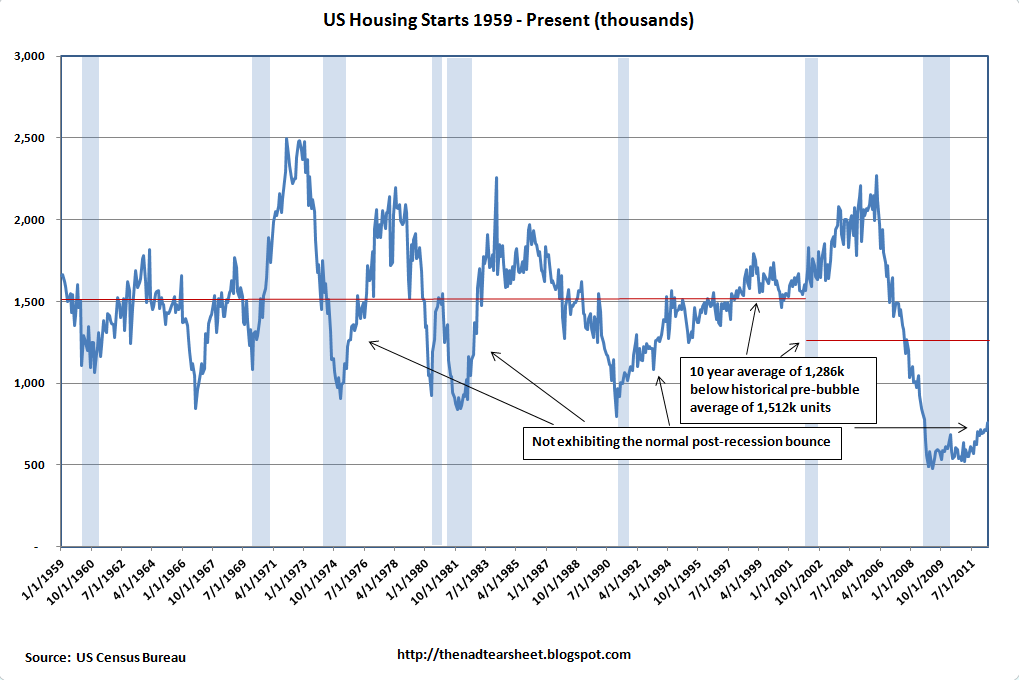
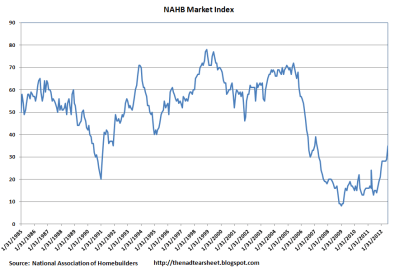
Housing starts came in at 760k in June, an increase from a revised 711k in May. While most other sectors in the economy are decelerating, the housing construction sector is accelerating. That said, housing starts are a long way from normalcy. Sentiment in the homebuilders has been improving as well, with the NAHB Builder Confidence Index rising smartly in July.
Housing Starts:

NAHB Housing Index
On the heels of San Bernardino’s eminent domain proposal, Georgetown Professor of Law lays out another avenue to deal with underwater equity – “quasi-voluntary” principal reductions. In his paper Clearing the Mortgage Market Through Principal Reduction, he makes the case that negative equity is the reason why the housing market hasn’t bottomed and we need a policy response to it. The solution – make the banks an offer they can’t refuse: Either reduce the principal on your underwater mortgages to home value or we’ll take away your ability to deal with the GSEs or FHA. Since this more or less is a “reduce principal or get out of the business” it isn’t much of a choice. While he mentions that there could be political consequences of these various actions (he looks at involuntary takings as well), he never mentions the possibility that lenders may in fact decide to adjust their risk calculations accordingly, thus drying up credit even more. What good is a new re-negotiated mortgage to the system if the existing homeowner can only sell to cash buyers or buyers that put up 40%? Amazingly, he doesn’t consider the knock-on effects to lender behavior at all. He assumes that things will just continue as before and lenders will write off this intervention as a necessary “one-off” that is really good for them and good for the country. If that is an indication of how liberal policy makers in general think – that the private sector will not react to their policy changes – that explains a lot.
Filed under: Morning Report | 10 Comments »
Posted on July 17, 2012 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1352.3 |
4.9 |
0.36% |
| Eurostoxx Index |
2266.2 |
14.3 |
0.63% |
| Oil (WTI) |
88.68 |
0.3 |
0.28% |
| LIBOR |
0.455 |
0.000 |
0.00% |
| US Dollar Index (DXY) |
83.12 |
0.021 |
0.03% |
| 10 Year Govt Bond Yield |
1.49% |
0.02% |
|
| RPX Composite Real Estate Index |
184.2 |
0.1 |
|
Markets are firmer this morning on an earnings “beat” out of Goldman. I put “beat” in quotation marks because the report was actually lousy as revenues are at a 7 year low. Expectations are way low going into this earnings season. As we approach August, the European newsflow should grind to a halt. Bonds are down a half a point, and MBS are down a tick or two. The Bernank is testifying in front of Congress at 10:00 this am. Expect a lot of newly-minted LIBOR experts to opine on the subject.
The CPI came in flat for June on falling energy prices. That is about to be offset by increased food prices as corn approaches $8.00 a bushel due to drought conditions in the Midwest. Industrial Production rose, while capacity utilization fell.
Bill Gross is warning of a recession “when measured by employment, retail sales, investment, and corporate profits.” Investment banks are taking down their economic forecasts in a large steps – Jan Hatzius of Goldman took his 2Q estimate to 1.1% from 1.3%, while Deutsche Bank’s Joe LaVorgna took down his forecast to 1% from 1.4%. These estimates would put the economy firmly in the “stall speed” range.
The WSJ notes that asking prices are rising as supply decreases. Asking prices are up 2.7%, while the number of homes listed for sale is down 19.4% from a year ago. Banks are holding back foreclosures from the market, and are often times finding bids on the courthouse steps from professional investors looking for rental properties. Median age has been falling as well.
Filed under: Morning Report | 12 Comments »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt