Morning Report 11/2/12

Vital Statistics: 

  Last Change Percent
S&P Futures  1428.8 5.6 0.39%
Eurostoxx Index 2554.3 20.4 0.81%
Oil (WTI) 86.74 -0.4 -0.40%
LIBOR 0.313 0.000 0.00%
US Dollar Index (DXY) 80.44 0.393 0.49%
10 Year Govt Bond Yield 1.76% 0.04%  
RPX Composite Real Estate Index 194.1 -0.3  

Futures are higher on the back of a better-than-expected October jobs report.  Bonds are MBS are down

Nonfarm payrolls increased 171k in Oct and the Sep number was revised upward from 114k to 148k.  The unemployment rate ticked up to 7.9% from 7.8% as the labor force participation rate increased to 63.8%. Weekly hours and pay fell. The report pretty much confirms the labor market is on the mend, albeit slowly.

The Northeast continues to pick up the storm damage, although gasoline shortages are becoming a problem as the lack of power in NJ means that gasoline can’t be pumped out of the large tanks into trucks. This will be an additional drag on the 4Q economic numbers as people stay home instead of shopping. 

We have another glimpse of how long the Fed thinks QE should last – until the unemployment rate falls below 7.25%. Boston Fed President Eric Rosengren cautioned that this was a threshold, not a specific target. Rosengren is one of the most dovish Fed members, but does not have a vote at the moment.  He went further to say that if the unemployment rate falls to 6.5%, it is time to start moving away from ZIRP.

Colony Capital won an auction for 970 Fannie Mae foreclosed homes in Arizona, California, and Nevada. It is a complicated partnership agreement and Colony plans to rent out the properties. It looks like they paid close to BPO $176MM for a portfolio that was appraised at $157MM in Feb.  Since Feb, prices have shot up in Arizona.  Colony will get 20% of the rents as a management fee, and will take 10% of the profits up to $136MM, and then their take grows to 50%.  It looks like they only have to put up something like $34 million.  Fannie was unable to sell the Atlanta portfolio.

The MR will be spotty next week as I am traveling to the Left Coast.

Morning Report 11/1/12

Vital Statistics:


Last

Change

Percent

S&P Futures 

1409.0

2.2

0.16%

Eurostoxx Index

2523.4

19.8

0.79%

Oil (WTI)

86.5

0.3

0.30%

LIBOR

0.313

0.000

0.00%

US Dollar Index (DXY)

79.9

-0.015

-0.02%

10 Year Govt Bond Yield

1.71%

0.02%


RPX Composite Real Estate Index

194.1

-0.3


Markets are up slightly as we recover from Sandy.  Transportation into NYC is still spotty, so expect lower-than-normal liquidity.  Bonds are down 1/2 a point and MBS are down small.

The US markets were closed Monday and Tuesday.  The last time the US markets were closed two consecutive days for a weather-related reason?  The Blizzard of 1888.

Can FEMA cover the losses from Sandy?  With the expected flood insurance claims, maybe not. 

We have a slew of economic data this morning, starting with ADP Employment Change.  This is supposed to mirror the payroll survey the government puts out.  It showed nonfarm private employment rose 158k in Oct, while Sep was revised downward from 162k to 114k.  ADP has made some changes to their methodology, so this number will be hard to predict / volatile for the near term.

Challenger and Gray reported announced job cuts increased 41% in Oct, largely a result of lackluster earnings reports so far. C&G don’t differentiate between domestic and overseas job cuts, so the impact on the US will be less.  The Markit Final PMI fell to a 37 month low.

Nonfarm productivity came in better than forecast, while unit labor costs unexpectedly fell. Initial Jobless claims came in at 363k.  Consumer Confidence, ISM, and construction spending will be released at 10:00.

Today is the first Thursday of the month, and that means retailers are reporting same store sales.  Generally, they are up across the board, which was pretty much to be expected.  Apparel did the best, while department and drug stores were generally down.

What will be the economic effect of Sandy? According to IHS Global, it could take 1.5% of 4Q GDP. But what about all of the construction workers that will be hired to rebuild?  More of a Q1 event, though overall, not enough to offset the balance sheet effects. Refer to the Broken Window Fallacy.  This will undoubtedly be motivation to prevent the fiscal cliff from occurring, although there seems to be a consensus that everything should be kicked down the road with the exception of the entirely symbolic tax cuts for incomes over 250k.


Morning Report 10/26/12

Vital Statistics:

  Last Change Percent
S&P Futures  1403.7 -4.5 -0.32%
Eurostoxx Index 2481.1 -2.3 -0.09%
Oil (WTI) 86.11 0.1 0.07%
LIBOR 0.313 0.000 0.00%
US Dollar Index (DXY) 80.18 0.138 0.17%
10 Year Govt Bond Yield 1.78% -0.04%  
RPX Composite Real Estate Index 193.9 -0.1  

Markets are flat after a better than expected GDP report offset the earnings miss from Apple. Surprisingly, bonds and MBS are rallying on the GDP number. Not sure what to make of that.

3Q GDP came in at +2%, higher than the +1.8% expectation.  This is the “advance estimate,” which means the source data are still incomplete, so the number will be subject to two revisions.  Increases in consumption and government spending were offset by a drop in nonresidential fixed investment. 

The NAR is forecasting that home prices will increase by 3.25% in 2013 based on its survey of 50,000 real estate practitioners.  

If Obama wins re-election, Ed DeMarco’s days at FHFA are probably numbered. To overcome Republican opposition, he will probably be fired and replaced while Congress is in recess. He has continued to butt heads with the Administration over principal reductions for GSE loans.

The MR may be a casualty of Sandy next week.  Hopefully not.


Morning Report 10/25/12

Vital Statistics:

  Last Change Percent
S&P Futures  1413.5 8.2 0.58%
Eurostoxx Index 2500.1 9.5 0.38%
Oil (WTI) 86.63 0.9 1.05%
LIBOR 0.313 -0.001 -0.32%
US Dollar Index (DXY) 79.82 -0.091 -0.11%
10 Year Govt Bond Yield 1.84% 0.05%  
RPX Composite Real Estate Index 194.1 -0.1  

Markets are stronger this morning after a strong durable goods report and a good UK GDP number. Initial Jobless Claims came in at 369k and last week was revised upward to 392k.  Capital Goods orders were flat. We had a slew of decent earnings reports this morning, and Apple will report after the close. Bonds are getting clocked on the durable goods number, with the 10 year down a point and mortgages down 10 ticks.

The Chicago Fed National Activity Index came in flat, but the 3 month moving average is still negative, indicating the economy is growing below trend.  

The FOMC statement yesterday was more or less a rehash of the prior statement.  Bond Traders who were looking for the Fed to add Treasuries to the QE mix were disappointed. The Fed noted that household spending has been advancing, while growth in fixed business investment has slowed.  Today’s durable goods and capital goods reports bear that out.  

The global slowdown is causing another round of job cuts.  This time, it is more than just Wall Street as Ford, Dow Chemical, Colgate Palmolive, AMD, and HP are all cutting staff.  The number of announced job cuts in the last 2 months is the highest since 2010.

The government is going after Bank of America for the sins of Countrywide. Needless to say, the consumer groups are delighted.  Lenders warn that credit will become even tighter. Certainly the litigation risk will get passed onto borrowers through higher rates and fees. Barney Frank believes the government should lay off JP Morgan for the sins of Bear, and claims that the government asked BOA to buy Merrill, but not Countrywide.

Whatever happened to the San Bernardino eminent domain idea?  This was the plan that involved the county taking performing underwater mortgages from the banks and forgiving principal. It appears the firestorm of criticism has caused the county to quietly table the idea.

Speaking of foreclosures, ABC News has a depressing photo essay of the foreclosure crisis.

Morning Report 10/24/12

Vital Statistics:

Last Change Percent
S&P Futures 1411.8 5.0 0.36%
Eurostoxx Index 2489.5 11.6 0.47%
Oil (WTI) 86.67 0.0 0.00%
LIBOR 0.314 -0.001 -0.32%
US Dollar Index (DXY) 80.02 0.041 0.05%
10 Year Govt Bond Yield 1.77% 0.01%
RPX Composite Real Estate Index 194.1 0.3

Stock index futures are stronger this morning after yesterday’s rout. Dow Chemical reported better than expected earnings in spite of a leaked memo that said the company was considering laying off 5% of its workforce. Facebook surprised to the upside by cracking the code on monetizing mobile. Mortgage aps dropped 12% last week.  The Markit PMI (a predictor of the ISM PMI) came in light, but still improved from Sep. Bonds and MBS are down small.

The FOMC rate decision is scheduled for 2:15 EST.  Historically the Fed has tried to stay out of the way this close to the election – in fact, the last announcement on QE (Infinity) was pushing it.  Which means the smart bet is going to be that this is a non-event.  That said, the Street is expecting some change – where the Fed adds Treasuries to its QE mix – so there is the possibility of market movement, especially MBS versus Treasuries. I wouldn’t want to be floating going into that announcement.

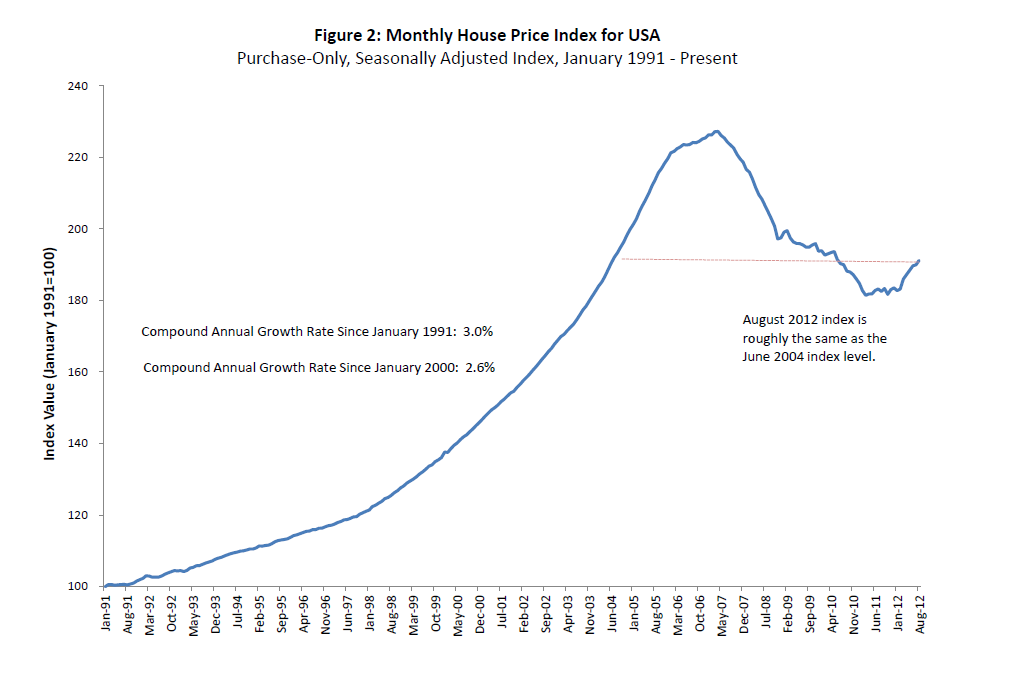
The FHFA House Price Index rose .7% in August, and is up 4.7% YOY.  This index covers only conforming mortgages, so it is less noisy than Case-Schiller or Radar Logic.

Freddie Mac’s latest US Economic and Housing Market Outlook expects QEIII to spark a further pick-up in housing activity, noting that housing has turned from a headwind to a tailwind for the economy. They are forecasting $2 trillion in originations this year, followed by a 15-20 percent contraction in 2013 as the refi boom plays out. They do worry about the fiscal cliff taking 2 percentage points out of GDP, although Obama is playing cat and mouse with the defense budget cuts, as he says one thing in the debates “cuts will not happen” and his advisers walk back the comments afterward. Elmer Fudd is quite concerned about the fiscal cliff as well.

Finally, Rob Chrisman gives you the data dump from the MBA Conference in Chicago.  Originators are adding capacity, the CFPB wants a flat fee for all mortgage originations, and the Street gets ticked when clients have the gall to check multiple dealers in order to get the best price on their TBA transactions.

Morning Report 10/23/12

Vital Statistics: 

  Last Change Percent
S&P Futures  1413.9 -16.2 -1.13%
Eurostoxx Index 2496.3 -34.9 -1.38%
Oil (WTI) 87.39 -1.3 -1.42%
LIBOR 0.315 -0.001 -0.16%
US Dollar Index (DXY) 79.85 0.202 0.25%
10 Year Govt Bond Yield 1.77% -0.04%  
RPX Composite Real Estate Index 193.9 -0.1  

Markets are lower this morning on earnings misses.  DuPont is down 5% pre-open after missing estimates badly.  Economic bulls will note that when late cyclicals like Dupont start reporting declines, that is usually an ominous sign for the expansion. UPS noted “uncertainty around the magnitude of the holiday shopping season.” Commodities are weaker as well.  Unsurprisingly, bonds and MBS are benefiting from the “risk off” trade. 

Today is another light day, economics wise, but tomorrow we get the FOMC announcement. The Street is looking for the Fed to broaden QEIII to include Treasuries.  Federal Reserve Bank of New York President William Dudley acknowledged in a recent speech that current policy “could distort asset allocations and lead to renewed financial asset bubbles. To date, there is little evidence of problems or excesses” Okay.  The 10-year is yielding 1.76%, below your stated inflation target of 2%. It makes you wonder where he would consider the 10-year to be in bubble territory.

Ever heard of “flopping?” It is the new scam where an underwater homeowner sabotages the resale value of a house in a short sale, which gets the bank to lower the asking price. The homeowner partners with a speculator who buys the property on the cheap, cleans it up, and flips it. The homeowner supposedly gets a piece of the action.

The Atlantic surveys the carnage of the lending industry from 2006 to the present.  3/4 of the biggest home lenders in 2006 no longer exist. I always thought the Super Bowl ad distribution is a tell – in the 2000 Super Bowl, the ads were dominated by dot coms.  In 2006, it was dominated by lenders. Hubris before the fall. Employment in the mortgage industry is roughly half of what it was at the height of the boom. Of course, now we have the opposite problem, with capacity constraints in the banking industry.  Of course regulatory uncertainty is playing a role, as Douglas Lebda of Lending Tree notes.

Is it really all just about price?  Financial and tech consulting firm Carlisle and Gallagher conducted a survey which revealed 34% of consumers are willing to pay more for a mortgage if it comes with superior customer service.  52% said they were willing to pay more to complete the mortgage process more easily. Note to Washington, only 23% of US consumers believe regulatory changes will have a positive impact on their next mortgage. 

Morning Report 10/22/12

Vital Statistics: 

  Last Change Percent
S&P Futures  1426.5 2.5 0.18%
Eurostoxx Index 2544.6 2.4 0.09%
Oil (WTI) 90.51 0.5 0.51%
LIBOR 0.316 -0.002 -0.47%
US Dollar Index (DXY) 79.54 -0.083 -0.10%
10 Year Govt Bond Yield 1.81% 0.04%  
RPX Composite Real Estate Index 193.9 0.1  

Markets are up slightly in spite of weak guidance out of Caterpillar. CAT is forecasting a 5% decline in next year’s sales based on the weak global economy. This week is heavy with earnings reports with Dupont, Facebook, 3M, Coca Cola, Conoco, and Amazon.com. On the economic front, we will have the FOMC rate decision tomorrow and the first estimate of 3Q GDP on Thursday.  Bonds are down 25 ticks and MBS are down 6 or 7.

Mark Zandi of Moody’s is endorsing the the qualified mortgage rule. This rule should provide lenders some relief from litigation as long as the mortgage was underwritten in accordance with CFPB guidelines. As far as loans outside those guidelines?  They “will remain toxic water for most lenders.”

Many market participants are expecting the Fed to announce that treasuries will be included in future QE.  The Fed has already committed to buy $40 billion of MBS a month until unemployment is down and it surprised many observers by not including Treasuries in that statement. This caused MBS to rally way in excess of what the moves in the 10-year would predict.  In some ways, this would offset the buying that would be lost when Operation Twist ends this year.  Bank of America is predicting the Fed will buy $45 – $60 billion of Treasuries in addition to the $40 billion in MBS. 

Still, banks are understaffed as the volume of mortgage applications swells, where timelines are being stretched from the typical 45-days to 90. Banks undoubtedly believe that the current volume is being driven by refis, which they view as temporary.  The article goes on to say that mortgage rates to the consumer should be lower, but they do note the increase in guarantee fees. 

Ocwen and Walter Investment are teaming up to out-bid Nationstar for Rescap.  

The Bipartisan Policy Center is launching a Dodd-Frank initiative, where they try and do a “cost-benefits” analysis to Dodd-Frank. They frame it as a “stability vs growth” issue.

Morning Report 10/19/12

Vital Statistics:

Last Change Percent
S&P Futures 1448.5 -3.0 -0.21%
Eurostoxx Index 2548.0 -26.2 -1.02%
Oil (WTI) 92.29 0.2 0.21%
LIBOR 0.317 -0.002 -0.47%
US Dollar Index (DXY) 79.52 0.151 0.19%
10 Year Govt Bond Yield 1.81% -0.02%
RPX Composite Real Estate Index 193.8 0.1

Markets are weaker this morning after earnings misses from bellwethers Google, Microsoft, McDonalds, and GE.  Euro sovereign yields continue to decrease.  Bonds and MBS are up about 1/4 of a point.

The CFPB is starting to put some more meat on the bones with respect to a qualifying mortgage. Lenders would be protected from penalties if the borrower is given a prime rate and the back-end debt ratio doesn’t exceed 43%. The NAR has already weighed in saying that “any partial safe harbor would need to go much further to avoid harm to the mortgage market.”

The Mortgage Bankers Association has sent a letter regarding proposed Basel III rules. They correctly note that the penalties on mortgage servicing rights are going to create a problem. Add the proposed new servicing standards out of the CFPB, and you may in fact turn mortgage servicing into a business nobody wants to perform.

While institutional investors are raising money to get into the REO-to-rental businesses, one of the pioneers, hedge fund Och Ziff, is looking to cash out.  Turns out that renting properties on such a vast scale isn’t as profitable as it initially appears.

Today is the 25th anniversary of the Crash of 87. I think in some ways, we can trace the origins of the financial crisis to this event. During the crash, newly appointed Fed Chairman Alan Greenspan pledged the Federal Reserve would provide liquidity to anyone who needed it. At the time, it was probably the right thing to do, as it prevented the stock market crash from ballooning into something bigger.  I think the Chairman recognized its success and used it every time the financial markets had a hiccup – from the Mexican Peso Crisis, to Long Term Capital, to the Asian Crisis. This behavior became affectionately known as the “Greenspan Put,” which means that even if you screw up, the Fed will come to the rescue. This created a underpricing of risk, which laid the groundwork for the real estate bubble.  Real estate prices became unmoored from their traditional relationship with incomes around the year 2000, just as the stock market bubble was going critical, and continued to inflate as the Fed flooded the system with liquidity in the aftermath. And since the Fed is still doing the same thing in response to the burst real estate bubble, this time on steroids, the game continues..


Morning Report 10/18/12

Vital Statistics:

  Last Change Percent
S&P Futures  1453.1 -4.0 -0.27%
Eurostoxx Index 2561.6 -8.2 -0.32%
Oil (WTI) 91.7 -0.4 -0.46%
LIBOR 0.319 -0.002 -0.62%
US Dollar Index (DXY) 79.14 0.120 0.15%
10 Year Govt Bond Yield 1.80% -0.02%  
RPX Composite Real Estate Index 193.7 0.5  

Markets are weaker on a weaker this morning ahead of the EU summit in Brussels. Euro sovereign yields continue to drop, which means the benign backdrop to the markets continues.  Earnings reports continue to exceed expectations, though the bar is set very low this quarter. Bonds and MBS are slightly higher. 

It turns out that last week’s dramatic drop in initial jobless claims was due to technical problems with seasonal adjustments in one state, as reported by CNBC.  Initial Jobless Claims increased to 388k from a revised 342k last week.

The Leading Economic Indicators had a big jump, up from -.4 to + .6,  We still seem to be oscillating around 0, with a positive reading followed by a negative one. This is indicative of a slow growth trend. 

Similarly, the Philly Fed Business Outlook Survey noted that conditions in the manufacturing sector remain weak. Labor conditions dropped as 22% of all firms reported decreases in employment and 11% reported increases. The average workweek dropped as well.  In terms of the mix of employees, more firms decreased the number of full-time employees and increased the number of temp workers. 

Prepare for a battle over the fiscal cliff. No tax hikes on the wealthy, no deal. Of course Obama has said that before.

The WSJ discusses yesterday’s big housing starts number. As the inventory of foreclosures declines and underwater sellers sense a turnaround in pricing, more and more buyers are looking to new construction.  Foreclosures as a percent of sales dropped to 14% in September, and are down from 50% a couple of years ago.

Morning Report 10/17/12

Vital Statistics:

  Last Change Percent
S&P Futures  1453.8 4.6 0.32%
Eurostoxx Index 2557.0 9.1 0.36%
Oil (WTI) 92.48 0.4 0.42%
LIBOR 0.321 -0.004 -1.23%
US Dollar Index (DXY) 78.96 -0.444 -0.56%
10 Year Govt Bond Yield 1.77% 0.06%  
RPX Composite Real Estate Index 193.3 -0.1  

Markets are higher after a strong report on housing starts. The banks reported good numbers while the techs disappointed. Mortgage applications fell, while building permits came in well above expectations.  Signs of strength in housing are pushing yields higher on Treasuries and MBS

Housing starts were 872k in September a rise of 15% MOM and 35% YOY.  Proportionally, multi-family had the biggest increase, which speaks to the strength in the rental market. While this level is a 4 year high, it still is just about the same level as the nadirs following the 82-82 and 91-92 recessions.  So we have a long way to go to get back to “normalcy” which is around 1.5 million, but things seem to be picking up in the housing sector, which has been a major drag on the economy.

Will investors do the heavy lifting of shrinking the TBTF banks? Given languishing stock prices and large discounts to book value, shareholders will be pressuring the banks to exit marginal businesses and either sell them or spin them off to shareholders. For example, Citi’s investment banking division is about the size of Goldman Sachs. Goldman trades at an 11 multiple, while Morgan Stanley trades at a 30 multiple. It would make sense for Citi, which trades at a 9.7 P/E to spin off the investment bank, which should unlock shareholder value.  Maybe they could resurrect the old Salomon Brothers.

The WSJ was out with a story last night which said the CFPB is considering giving lenders safe harbor if they originate a qualified mortgage.  It sounds like this safe harbor wouldn’t insulate the banks from buyback risk, but it would insulate them from lawsuits and penalties from the government. If there isn’t any protection from buyback risk, I am not sure how much this would end up mattering in the end.