Morning Report – QM Day 01/10/13

Vital Statistics:

  Last Change Percent
S&P Futures  1464.7 8.9 0.61%
Eurostoxx Index 2712.4 6.0 0.22%
Oil (WTI) 94.4 1.3 1.40%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.35 -0.206 -0.26%
10 Year Govt Bond Yield 1.90% 0.04%  
RPX Composite Real Estate Index 191.7 -0.3  

Markets are higher this morning after positive news out of Ford and Nokia.  Initial Jobless Claims increased 4k to 371k, higher than the 365k estimate.  The ECB left rates steady and predicted a gradual recovery for the Eurozone this year.  Bonds and MBS are down.

WaPo has a write-up of the new QM rules expected to be released today by Richard Cordray in Baltimore.  You can watch the speech here. Expected changes:  Upfront fees will be capped at 3%, though exceptions will be made for loans under 100k, and IO mortgages will be banned.  Ability to repay will be based not on the teaser rate, but on the expected rate later on.   DTI ratios must be below 43%.  The rules will be phased in over the next 7 years. The CFPB estimates that 75% of the mortgages issued in 2011 would have met the standards. If the banks follow these rules, they will be protected from many homeowner lawsuits, but not necessarily buy-back risk. Jumbos will probably the area most affected by the new rules. MND has the gory details here.

What does the appointment of Jack Lew as Treasury Secretary mean?  That the Administration will be focusing its energy on budget battles going forward. He is not considered (at least by the Left) to be the sort of guy that will be addressing unemployment, or pushing for Keynsian stimulus. As such, he probably isn’t going to be tremendously dollar-negative, although in an era of competitive devaluations, it is hard to be a dollar bear anyway. The tight relationship between the Fed and Treasury will end. He is probably going to be a tough negotiator for the WH’s budget priorities – higher taxes on the rich no no non-defense spending cuts. He also has an unusual signature, (OoooooO) which will be gracing your dollar bills soon enough. 

Acccording to NAR, 2012 will go down as a record year for housing affordability. The index came in at 198.2, which means the median borrower had 198% of the minimum income required to purchase the median price existing family home, assuming 20% down and 25% of income going to P&I payments. Tight credit standards remain the sticking point.

Thinking outside the box:  Instead of paying the unemployed, pay their employers to keep them on. Through the work-sharing plan, employees get a shortened work week, with unemployment benefits partially compensating them for lost wages. 

The hits keep coming:  Morgan Stanley is laying off 1,600 workers.

Battle Royale:  Ackman vs Loeb in Herbalife.

Morning Report – Settlements, Settlements 01/09/13

Vital Statistics:

 
  Last Change Percent
S&P Futures  1454.2 1.9 0.13%
Eurostoxx Index 2697.2 5.8 0.21%
Oil (WTI) 93.08 -0.1 -0.08%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.53 0.180 0.22%
10 Year Govt Bond Yield 1.86% -0.01%  
RPX Composite Real Estate Index 192 -0.2  
Markets are firmer this morning after Alcoa kicked off earnings season with better than expected revenues. Mortgage applications rose 11.7% in the first week of Jan.  The Japanese yen continues its slide that started with the elections last month, which means the entire planet is now playing the currency devaluation game. Bonds and MBS are up small.
 
Looks like Jack Lew is the new nominee for Treasury Secretary.
 
Blackstone has been accelerating its rental strategy, buying $2.5 billion or 16,000 homes last year.  In the 4th quarter alone, they bought $1.5 billion worth on homes.  Their plan is to turn residential properties into a new  $1.5 trillion institutional asset class. J.P. Morgan estimates that the market could total 12 million homes and be double the institutional multi-fam market.  Blackstone is concentrating on the 9 hardest-hit cities – places like Phoenix and Miami.  Scalability will be the key determinant here. Still, it is an interesting idea, and is another reason why the rebound in house prices could be stronger than people are forecasting.  
 
Another settlement seems to be in the works – Goldman, HSBC, Ally, and Morgan Stanley are close to reaching a $1.5 billion settlement with the Feds for alleged servicing sins. For consumer activists and lawyers, these settlements are never enough.
 
Marketwatch is reporting that we will finally get the new QM rules this week. It is expected that implementation could take up to a year.  The ABA has said that “Banks are not likely to operate outside the legal guarantees offered by the qualified mortgage protections, meaning that the safe harbor rules will largely determine the scope of all future mortgage lending.”  The CFPB is expected to finalized rules on servicing, LO comp and appraisals by Jan 21.
 
Tony Crescenzi of PIMCO asserts there is no bubble in bonds. Between demographics and the Fed, he believes we will not see a collapse in the bond market. Needless to say, PIMCO has a habit of talking its book, so take what he says with a grain of salt. But he may in fact be correct that the baby boom’s investing habits will mirror the ones of the jazz age generation which lost everything in the Great Depression.  

Morning Report – NFIB Pessimism 01/08/2013

Vital Statistics:

  Last Change Percent
S&P Futures  1454.8 -1.0 -0.07%
Eurostoxx Index 2703.9 8.4 0.31%
Oil (WTI) 93.5 0.3 0.33%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.37 0.113 0.14%
10 Year Govt Bond Yield 1.89% -0.01%  
RPX Composite Real Estate Index 192.2 -0.2  

Markets are lower this morning as we kick off 4Q earnings season. Alcoa officially begins the parade after the close. Bonds and MBS are up small. 

The NFIB Small Business Survey for January ticked up slightly in December after falling off a cliff in November.  The current level of 88 is a recession-level reading.  Capital Spending is still in maintenance mode. Employment growth is flat. Housing, energy, and autos (the average age of a car is over 10 years) look to be the drivers of growth in 2013. But, overall, it was a glum report.

Chart:  NFIB Small Business Optimism:

The National Association of Home Builders Improving Market Index rose to 242 (out of 361 MSAs total) in January from 201 in December. This strength during a seasonally weak period bodes well for the summer selling season and confirms our view that housing bottomed about a year ago. Rentals are still booming as rents increased 3.8% YOY last quarter.  The vacancy rate dropped to 8%.

Could the East Coast get a break in gasoline prices?  Currently, the East Coast refineries use North Sea Brent crude oil, which trades at a premium to West Texas Intermediate, which is the source for West. Burlington Northern will boost crude oil shipments by 40% this year (primarily Bakken shale oil), and is looking to ship east to supply refineries on the Eastern Seaboard.  As coal shipments decline, oil is taking their place. Since railroads have more flexibility than pipelines, the continental US energy market will become more equalized.  Good news for the East Coast.

A new study shows that we may hit the debt ceiling sooner than expected, around Valentine’s Day (how romantic). Obama has said that the debt ceiling is non-negotiable. My sense is that Republicans will cede the debt ceiling point and use the sequestration or the expiration of the government’s operating budget to push through spending cuts.  As a plan B, the trillion dollar coin is still being bandied about, particularly by the Krug Man and Greg Sargent (who talks to NYPD hostage negotiators, instead of economists, apparently).

Morning Report – Basel III 01/07/2013

Vital Statistics:

  Last Change Percent
S&P Futures  1455.6 -2.1 -0.14%
Eurostoxx Index 2697.9 -11.4 -0.42%
Oil (WTI) 92.64 -0.5 -0.48%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.56 0.061 0.08%
10 Year Govt Bond Yield 1.90% 0.00%  
RPX Composite Real Estate Index 192.4 0.3  

Markets are slightly lower this morning after last week’s big rally.  This week looks to be relatively light data-wise.  4Q earnings season kicks off tomorrow with Alcoa announcing after the close. Bonds are up small after last week’s sell-off and MBS are flat. 

Basel has relaxed some of the requirements for the liquidity coverage ratio, and delayed the implementation in response to requests from the ECB. The ECB feared that the new requirements would lead to a credit crunch and would require banks to be over-invested in sovereign debt. Now banks will be allowed to count corporate debt, residential MBS, and even equities as liquid assets.  While MBS and bond price behavior is dominated by the Fed and QE, the net effect will push banks to hold MBS and sell Treasuries, so you should be aware that the 10-year could sell off and MBS could rally. 

On the other side of the coin, last week’s sell off in bonds and MBS has fueled fears that the housing recovery may stall as rates rise. Much of the boom in prices last year was in areas hit hard by distressed sales, as professional investors snapped up properties in places like Phoenix, Las Vegas and Detroit.  The 20% price increases there have probably run their course.  Rising rates would certainly end the refi boom that banks have feasted on for the past year, meaning originators will have to go back to the ground game of building relationships with realtors and focusing on purchase activity.

The worst merger in history continues to plague BOA.  They agreed to pay Fannie Mae $3.6 billion to settle repurchase claims and to repurchase another $6.75 billion of bad mortgages. Worst merger since Steve Case sold Ted Turner a bill of goods just as the internet bubble was bursting. Separately, Nationstar purchased a $215 billion servicing portfolio from BOA as well. Half is GSE / Govvie and half is private label. They paid $1.3 billion.

Republicans have declared tax increases off the table for the upcoming negotiations on the debt ceiling and the sequestration. Obama has already said that cutting spending has to go “hand-in-hand with tax law changes so that the wealthiest corporations and individuals can’t take advantage of loopholes and deductions that aren’t available to most Americans.” My guess is that he is talking about carried interest and oil “subsidies” and not about further increases in marginal tax rates or further limiting the mortgage interest deduction. Oh, and we need a clever name for the upcoming negotiations on the sequestration and debt ceiling. 

Morning Report – Jobs Day 01/04/13

Vital Statistics: 

  Last Change Percent
S&P Futures  1453.4 -0.2 -0.01%
Eurostoxx Index 2696.4 -4.8 -0.18%
Oil (WTI) 92.08 -0.8 -0.90%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.84 0.460 0.57%
10 Year Govt Bond Yield 1.92% 0.01%  
RPX Composite Real Estate Index 192.1 0.1  

Markets are slightly higher after the economy added 155k jobs in December.  The unemployment rate came in at 7.8%, flat vs the revised upward Nov number.  The labor force participation rate was flat at 63.6%. Bonds and commodities have been getting hit since the release of the FOMC minutes yesterday, which indicated QE’s days are numbered.  The 10-year yield has broken out of its 6 month trading range, and MBS are down about 1/4 of a point. 

The minutes of the FOMC meeting revealed that the Fed will probably end QE some time this year. This has put pressure on Treasuries, as well as commodities like gold.  The Fed is predicting 2.3% – 3% GDP growth this year, which is above most other forecasts.  They debated whether to purchase Treasuries or MBS, noting that they haven’t been getting the “spill-over effect” in MBS that they had hoped for by buying Treasuries.  They also said that they do not want to give the impression that they are setting monetary policy solely on two variables – the unemployment rate and the inflation rate. 

The minutes explain why Treasuries refused to rally on the debt ceiling brinkmanship last year – the market knew the Fed was planning to end QE some time this year.  And the differing reactions of the stock and bond market is explained because stocks were paying attention to the machinations in Washington, while bonds were watching the Fed. So this was not the typical “bonds are right, stocks are wrong” dynamic you usually see.

Tim Geithner plans to leave the Administration by the end of the month, and won’t stick around for the debt ceiling debate.  White House Chief of Staff Lack Lew is the favorite to replace him. Lew worked for Citi from ’06-’08, but other than that has spent his career in government.  This will be the first non Wall Street / Fed Treasury secretary in a while, since the disastrous reigns of industry guys like the Paul (The Tin Man) O’Neill and John Snow in the Bush Administration.

The Fed examines why lending rates have not fallen in lockstep with QE in a new paper which asks why isn’t the 30 year fixed rate mortgage at 2.6%.  It does try and provide some reasonable explanations, for example, it does cite the increase in G-fees.  It also cites (a) increased put-back risk, (b) the declining value of MSR’s, and (c) higher origination costs due to increased regulatory scrutiny. That said, the academics tested the hypothesis that each of these individual items were driving the increased margins for lenders, but nothing was significant by itself. So they reject that hypothesis.  Since the t-stat is below 2, it doesn’t count, I guess, so price-gouging must be the explanation, and not these other reasons, which are 100% controlled by the government.  Sigh.

Morning Report – Money for Nothing. 01/03/13

Vital Statistics:

  Last Change Percent
S&P Futures  1455.0 -2.1 -0.14%
Eurostoxx Index 2690.8 -20.4 -0.75%
Oil (WTI) 92.82 -0.3 -0.32%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.16 0.317 0.40%
10 Year Govt Bond Yield 1.84% 0.01%  
RPX Composite Real Estate Index 192 0.2  

Stock markets are giving back a little after yesterday’s relief rally on the fiscal cliff deal.  Mortgage Applications fell 10.4% last week.  2013 forecasts are starting to trickle in from strategists – suffice it to say 1H13 looks rough, with the economy basically at stall speed. 

There is quite a bit of economic data this morning.  ADP forecast that 215k private sector jobs were created in December.  Challenger and Gray reported that announced job cuts fell in December to 32,556. Initial Jobless Claims came in at 215k. The NY ISM came in at 54.3, indicating the outlook is barely positive.  Later this afternoon, we will get the minutes from the Dec FOMC meeting.

Corelogic reported that shadow inventory – properties that are seriously delinquent, in foreclosure, or are REO that are not listed for sale – fell 12% in October to 2.3 million units, representing 7 month’s supply.  Almost half of the properties are delinquent and not foreclosed.  The real question is how much this inventory will depress prices.  Given that many of these units are in judicial states, the supply will be dripped out slowly. Also, if a home has been vacant for several years, it develops problems that make the repairs more than the property is worth.  So, while it is in inventory, it is probably worth very little and isn’t competing with the homes that most normal homebuyers are focused on. 

So now that we have the fiscal cliff uncertainty out of the way, the markets should continue to rally, right?  We, according to business leaders, no.  And since the deal does not reduce debt, we are in danger of a downgrade, according to Moody’s. The debt ceiling also was a taste of what is to come, with 3 gating items in the near future – the debt ceiling, the continuing resolution, and the sequestration.  Obama has already laid a marker down saying that it can’t be “all spending cuts.”  Given that Republicans have already made the tax hike concession, they are likely to take a tough negotiating stance on these items. So it could get ugly.

How did Obama get Boehner on board for tax increases?  A simple warning.  Stop opposing higher taxes for top earners or I will dedicate my second term to blaming Republicans for the global recession. And, blame is one of Obama’s many talents.

Latest investment outlook from Bill Gross – Money for Nothin’ Writing Checks for Free.  The basic idea is that right now, the government is financing its deficit more or less for free.  Why?  Because the Fed is buying the treasuries (or at least 80%) through QE, and by statute, it gives its profit or losses back to the government.  So the government is basically (in a roundabout way) paying interest to itself. Bill goes on to point out that this has been done before, and it has always ended badly. In the long run, inflation will rear its ugly head.  Of course Paul Krugman would echo Keynes and say “in the long run, we are all dead.”  Bill also makes the good Austrian point – that Krugman has no answer for – that the unintended consequences of QE include mal-investments that will sow the seeds for the next bust.  You can view this debate here.

Morning Report: Happy New Year 01/02/13

Vital Statistics:

  Last Change Percent
S&P Futures  1445.5 25.4 1.79%
Eurostoxx Index 2705.2 69.3 2.63%
Oil (WTI) 93.3 1.5 1.61%
LIBOR 0.305 -0.001 -0.33%
US Dollar Index (DXY) 79.45 -0.282 -0.35%
10 Year Govt Bond Yield 1.84% 0.09%  
RPX Composite Real Estate Index 191.8 -0.5  

Markets are higher this morning after the government reached a compromise on the fiscal cliff.  It turned out the bond market (which was refusing to rally in spite of the setbacks along the way) was correct in its forecast.  When stocks and bonds are telling you different things, listen to the bond market –  it is usually right.  The 10-year is at the top of its recent 1.55 – 1.85 trading range.  MBS are down.

The House passed the Senate compromise on the fiscal cliff late last night, taking income tax hikes for most people off the table (although taxes are going up for everyone with a job).  Here are the main effects:

  • Tax rates will increase to the Clinton level rates for incomes over 450k
  • Limits on itemized deductions kick in at incomes > 300k
  • Capital Gains and Dividends rise to 20% for incomes over that threshold
  • Estate tax set at 40%, with a $5 million threshold that will be indexed to inflation
  • The sequester will be delayed for 2 months
  • the AMT will be permanently patched and indexed for inflation.
  • Extended unemployment benefits continue
The debt ceiling was not addressed in this deal.  The end deal is more or less a tax hike with no spending cuts. It looks like they extended the tax relief for principal mods / short sales as well.  So, unless you make over $300k, you are fine, right?  Nope.  77% of all households will see their taxes increase because the payroll tax holiday expired.
 
On to the debt ceiling, where Obama has already said he won’t accept spending cuts without further tax increases. That will be a contentious debate, since Republicans already walked the plank with their base and voted for tax hikes without Democrats giving up a thing.  Given that Republicans have voted for tax hikes already, the “Republicans are unreasonable” arguments will lose some of their sting.  They will be emboldened to push for more spending cuts, which the White House will refuse. While the WH had the benefit of circumstance in the fiscal cliff negotiations, where the default outcome was a big tax hike, now Republicans have the benefit of circumstance where the default outcome is where spending gets cut (as the sequester was merely delayed, not eliminated).  Punch line, things will get ugly again in Washington, so look to fade this rally.
 
Bob Schiller is not convinced we are off to the races in the housing recovery.  Basically, he believes housing has hit “fair value” and isn’t going anywhere for a while. He may be correct, and that house price inflation will go back to its old relationship with incomes.


Morning Report – On the Waterfront Edition 12-28-12

Vital Statistics:

  Last Change Percent
S&P Futures  1401.8 -8.9 -0.63%
Eurostoxx Index 2633.2 -26.8 -1.01%
Oil (WTI) 91.01 0.1 0.15%
LIBOR 0.308 -0.003 -0.96%
US Dollar Index (DXY) 79.81 0.188 0.24%
10 Year Govt Bond Yield 1.70% -0.03%  
RPX Composite Real Estate Index 192.3 0.0  

Stock index futures are lower on pessimism about a budget deal. Obama will meet with Congressional leaders today to see if they can hammer out a deal. The House will meet on Sunday night. The same story remains – stocks are worried about going over the cliff, while the bond market seems skeptical.  For a laugh, check out Rick Santelli’s rant about the way the markets are handicapping it. 

One other possible headwind for the economy in Q1 – a longshoreman’s strike that would close cargo ports on the Eastern Seaboard and the Gulf Coast. This would not only limit raw material supplies to US factories, it would also push many logistics workers, truck drivers, etc on to the unemployment rolls. Some economists estimate that a strike could cost the US economy $1 billion a day. Will Obama risk alienating his labor base to intervene?  Fun fact:  the average compensation for a longshoreman in $124k.

Yesterday’s consumer confidence numbers took a step downward, and seem to back up reports that this year’s holiday sales were weak.The outlook for business conditions and labor markets fell. 

Chart:  Conference Board Consumer Confidence:

 In spite of the pessimism over the fiscal cliff, luxury homes priced over $1 million are making a comeback. Sales have risen by 9% for the first 9 months of 2012.  Strong foreign demand has been driving up prices in Manhattan and the Hamptons. In terms of foreclosures over $1 million, the NYC suburbs hold 4 out of the top 10 zip codes, with New Canaan taking the lead.  This is still the wreckage from the bust, where lots of $1 million a year guys lost their jobs in 2007 and haven’t worked since.

Morning Report – the Mod Squad 12-27-12

Vital Statistics:

Last Change Percent
S&P Futures 1416.2 2.7 0.19%
Eurostoxx Index 2665.1 16.6 0.62%
Oil (WTI) 91.18 0.2 0.22%
LIBOR 0.311 0.001 0.32%
US Dollar Index (DXY) 79.44 -0.182 -0.23%
10 Year Govt Bond Yield 1.77% 0.01%
RPX Composite Real Estate Index 192.3 0.5

Markets are quiet again as desks are understaffed both in Europe and the US. Initial Jobless Claims fell to 350k, back to the bottom end of our 350k – 390k range. Bonds and MBS are down small and continue to dismiss the possibility of a cliff-induced recession.

President Obama heads back to Washington to try and craft a deal to avert the fiscal cliff. The WH seems to have backed off its proposal to increase taxes at 400k and has moved back to 250k. It is looking more and more like we will go over the cliff on Jan 1 and then pass some sort of tax cut package soon thereafter.  Treasury informed Congress that we will hit the debt limit on Monday, but they can play some games to keep the government funded through Feb.

Of course, once we climb the fiscal cliff, we will go right into the battle of the debt ceiling. Moody’s has already fired a shot across the bow, saying that they expect the government to raise the limit, but they may downgrade the U.S.’s credit rating unless we get a decrease in the debt / GDP ratio.

Yesterday’s WSJ report on possible new initiatives to mitigate the effects of the housing bust have already been met with skepticism. The first plan involved allowing deeply underwater non-agency loans to refi into Fan and Fred loans.  James Pethokousis of the American Enterprise Institute points out that allowing the GSEs to refi underwater non-agency mortgages is a non-starter with virtually all Republicans and many Democrats as it shifts risk from the private sector to the public sector.  Plus, you have to get the originators on board, and they won’t make 125%+ LTV loans without some sort of safe harbor against buyback risk.

A second plan would further expand HAMP, by changing the definition of “in danger of imminent default” to include anyone who is has a LTV over 125%, even if they are current on their mortgage. Such a move would not require Congressional approval. The American Securitization Forum is against the idea, given that these loans are worth their weight in gold.  They are current, have above-market coupons, and have virtually no chance of being prepaid for years. If enacted, investors would take an income hit (although Treasury would pay them the coupon difference for 5 years), and would see a capital loss as well. My sense is that ASF’s argument will be met with very little sympathy in the Administration, although state and federal pension funds will be quietly making the same argument as well. Still another hurdle would be servicers, who would have to buy off on the idea that modding a current loan is somehow good for the investor.

Morning Report – Case-Schiller 12/26/12

Vital Statistics:

  Last Change Percent
S&P Futures  1422.7 2.9 0.20%
Eurostoxx Index 2648.5 -2.6 -0.10%
Oil (WTI) 89.09 0.5 0.54%
LIBOR 0.31 0.000 0.00%
US Dollar Index (DXY) 79.66 -0.015 -0.02%
10 Year Govt Bond Yield 1.78% 0.00%  
RPX Composite Real Estate Index 191.8 0.1  

Markets are quiet this morning, as most of Europe is shut for Boxing Day. Bonds and MBS are flat.

Not much is happening on the fiscal cliff front, although Obama plans to cut his vacation short and return to Washington to try and hammer out a deal. Chances of any sort of grand bargain are virtually nil; all that could be accomplished at this point is some sort of fig leaf. In spite of the political and economic uncertainty, and the early indications of a weak Christmas, the bond market still refuses to price in the possibility of a recession. 

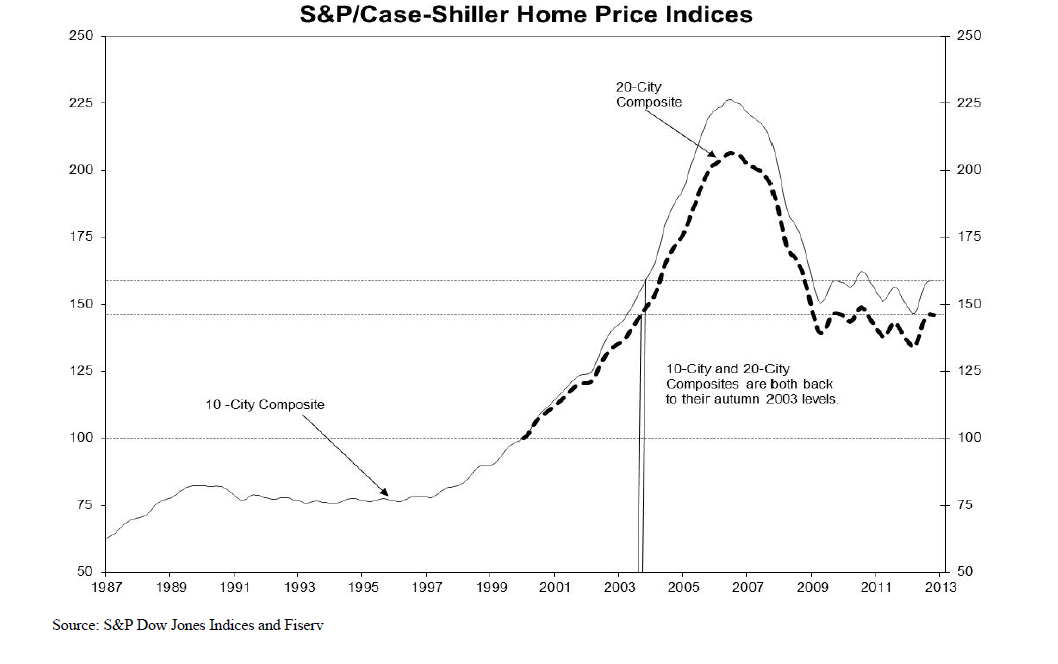
The S&P / Case-Schiller index of home values came in at  145.93 for the month of October, up 4.3% year-over-year and up 66 basis points month-over-month. The hardest-hit MSAs continued to show the biggest gains, with prices up 22% in Phoenix and 10% in Detroit. The Northeast MSAs (Boston and NY) are showing the smallest increases.

Chart:  S&P / Case-Schiller:

The Obama administration is considering expanding its mortgage-refinancing program to include underwater borrowers with non government loans.  Such a move would require legislation to change Fannie and Fred’s charters and would also involve a bump in the guarantee fee to price in the additional risk. It will also require the blessing of FHFA, which has indicated general support for the program.  Finally, it will require some sort of immunity from buy-back risk in order to get originators on board. 

A new study confirms what many have thought about high-frequency trading:  It is highly profitable and adds no value to the system as a whole. Aggressive, liquidity-taking high frequency trading (in other words, front-running) does the best. The profitability of HFT seems to be persistent – new entrants are less likely to be profitable and are more likely to exit. Speed matters above all, and that is why James Simons is so consistently profitable.