Morning Report – What is going on with mortgage rates? 6/5/13

Vital Statistics:

  Last Change Percent
S&P Futures  1625.1 -6.1 -0.37%
Eurostoxx Index 2723.4 -32.3 -1.17%
Oil (WTI) 93.76 0.5 0.48%
LIBOR 0.274 0.001 0.18%
US Dollar Index (DXY) 82.58 -0.192 -0.23%
10 Year Govt Bond Yield 2.12% -0.02%  
Current Coupon Ginnie Mae TBA 101.8 0.0  
Current Coupon Fannie Mae TBA 100.3 -0.8  
RPX Composite Real Estate Index 201.8 0.4  
BankRate 30 Year Fixed Rate Mortgage 4.16    


Markets are weaker after a disappointing ADP report. Nonfarm productivity was revised downward to .5% while unit labor costs fell. The Fed will release its Beige Book later on this afternoon. Mortgage applications fell 11.5% last week. Bonds and MBS are up small on the data.
 
The ADP report is supposed to foreshadow Friday’s all-important jobs report, albeit only the private sector portion. Basically take the jobs report, subtract out public sector workers, and you have ADP. The ADP employment change report came in at 135,000 vs expectations of 165,000. Friday’s payroll report is expected to be 178,000, with an unchanged unemployment rate of 7.5%. Bonds spiked on the ADP number and have pretty much given it all back. I am struggling to come up with a scenario where bonds rally big on Friday. My guess is that it will take an increase in the unemployment rate (like 7.7%) and a lousy payroll number, like 50k. The bond market increases so grudgingly, it feels like it won’t take much of an upside surprise to send it lower.
 
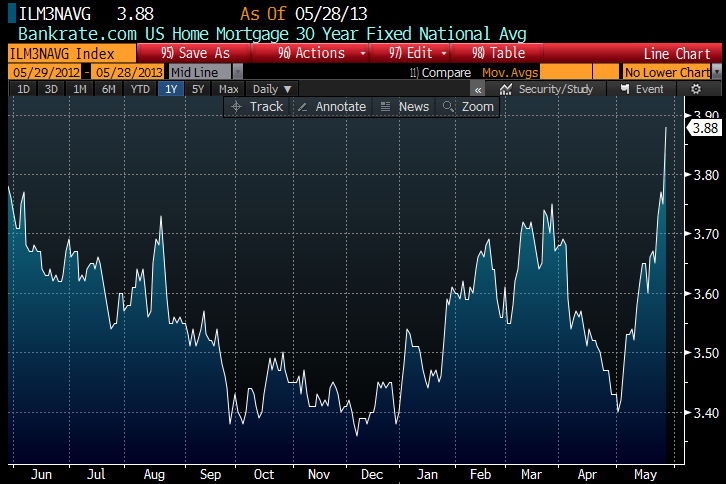
I first thought it was a data error, or a misprint. On Friday, the Bankrate US Home Mortgage 30 year Fixed National Average spiked from 3.9% to 4.1%. But it increased again on Monday and Tuesday and now is sitting at 4.16%. Over that period, the 10 year is unchanged, but the FNCL 3.5 TBA is down a point, which corresponds to a 22 bp increase in yield. The GNSF 3.5 is down 14 ticks, which corresponds to a 10 basis point increase in yield. So how do we get a 26 basis point increase in mortgage rates when Fannies are up 22bps and Ginnies are up 10?  And no, its not jumbos, which only increased 4 basis points. Strange things are afoot at the Circle K. 


Morning Report – Progress on the GSEs 6/4/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1638.5

2.3

0.14%

Eurostoxx Index

2765.3

17.5

0.64%

Oil (WTI)

93.19

-0.3

-0.28%

LIBOR

0.274

0.001

0.26%

US Dollar Index (DXY)

82.81

0.149

0.18%

10 Year Govt Bond Yield

2.13%

0.01%


Current Coupon Ginnie Mae TBA

101.9

-0.2


Current Coupon Fannie Mae TBA

100.4

-0.1


RPX Composite Real Estate Index

201.5

0.6


BankRate 30 Year Fixed Rate Mortgage

4.11


Markets are up small after a 2% rally in Japan’s Nikkei 225 index last night. Bonds and MBS are down small.

Yesterday’s ISM report showed the manufacturing sector contracted slightly in May. New Orders and Production fell, while inventories rose. Employment was flat. The index level of 49 corresponds to a GDP growth rate of just about 2%.

The Senate is close to establishing a plan to abolish Fannie Mae and Freddie Mac and replace them with a government re-insurer that would backstop private mortgage insurance. F&F would be wound down and the US Treasury would assume responsibility for existing conforming loans. A new entity – the Federal Mortgage Insurance Corporation (FMIC) would provide re-insurance, which means they would only step in if the private mortgage insurer was unable to cover the losses. For holders of the junior preferreds, which includes a lot of big hedge funds, this doesn’t look like anything good for them.

And for those keeping track at home, here is Fannie Mae’s recent chart:

Image

Morning Report – John Williams confirms QE could end this year 6/3/13

Vital Statistics:

  Last Change Percent
S&P Futures  1634.2 5.2 0.32%
Eurostoxx Index 2772.8 3.1 0.11%
Oil (WTI) 92.68 0.7 0.77%
LIBOR 0.273 -0.002 -0.73%
US Dollar Index (DXY) 83.15 -0.228 -0.27%
10 Year Govt Bond Yield 2.16% 0.03%  
Current Coupon Ginnie Mae TBA 101.8 -0.1  
Current Coupon Fannie Mae TBA 100.4 -0.3  
RPX Composite Real Estate Index 200.8 0.3  
BankRate 30 Year Fixed Rate Mortgage 4.1    


Markets are higher on no real news. We will get an important manufacturing report at 10:00 am est with the ISM Manufacturing Report. Bonds and MBS are down small.
 
Lots of data this week, with the ISM Manufacturing Survey later this morning, Unit labor costs and productivity on Wed and the jobs report on Friday. The jobs report will obviously be the biggest report of the week. The Street is expecting an increase of 177 jobs and a 7.5% unemployment rate. 177,000 jobs is on the low side of recent history. 
 
Federal Reserve Bank of San Francisco President John Williams confirmed the conventional wisdom in the bond market – that the Fed may start reducing asset purchases with an eye towards ending QE by year end. “With continued good signs on jobs and confidence in a substantial improvement, I could see as early as this summer, some adjustment, maybe modest adjustment downward in our bond purchase program.” The program is doing this great job of helping the economy gain momentum and I would want to see that continue well into the second half of the year, but if things, again iff they go well, you could imagine ending the program by the end of the year.”
 
The sell-off in bonds has been painful for PIMCO: Bill Gross’s Total Return Fund lost 2.2% last month.
 
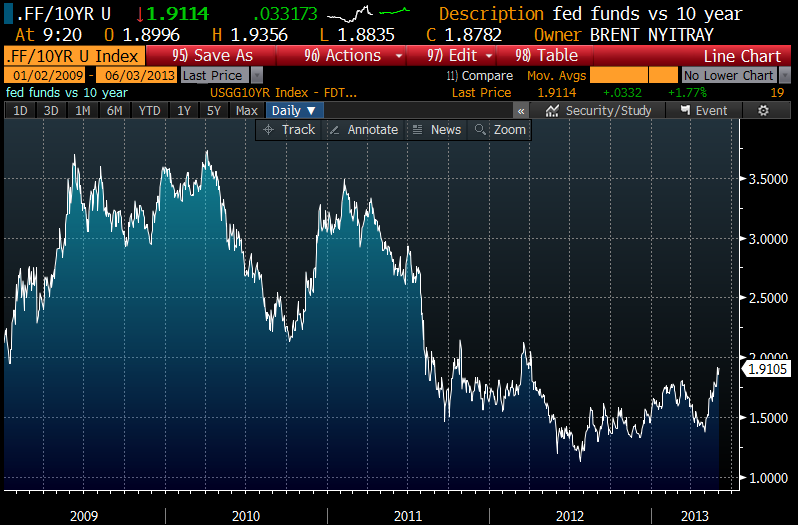
If the Fed ends QE, how high can we expect 10 year yields to go? Actually, a lot higher. The following chart shows the difference between the 10 year bond and the Fed Funds rate since it was set at 25 basis points in early 2009. Since we know the Fed is probably going to wait until unemployment gets closer to 6% before making any moves with the Fed Funds rate, we can assume that stays constant for the near term. But this chart shows we have gotten used to a flat yield curve over the past year. And that may be about to change.
 
Chart: 10 year bond yield minus the Fed Funds Rate
 

Morning Report – the beginning of a secular bear market in bonds? 5/31/13

Vital Statistics:

  Last Change Percent
S&P Futures  1645.7 -7.9 -0.48%
Eurostoxx Index 2781.4 -17.8 -0.64%
Oil (WTI) 92.79 -0.8 -0.88%
LIBOR 0.275 0.001 0.22%
US Dollar Index (DXY) 83.15 0.108 0.13%
10 Year Govt Bond Yield 2.10% -0.01%  
Current Coupon Ginnie Mae TBA 102.6 0.4  
Current Coupon Fannie Mae TBA 101.1 0.1  
RPX Composite Real Estate Index 200.6 0.4  
BankRate 30 Year Fixed Rate Mortgage 3.9    


Markets are weaker this morning after personal income and personal spending came in weaker than expected. Bonds and MBS are up small.
 
University of Michigan Consumer Confidence increased to 84.5 from 83.7 the week before.  
 
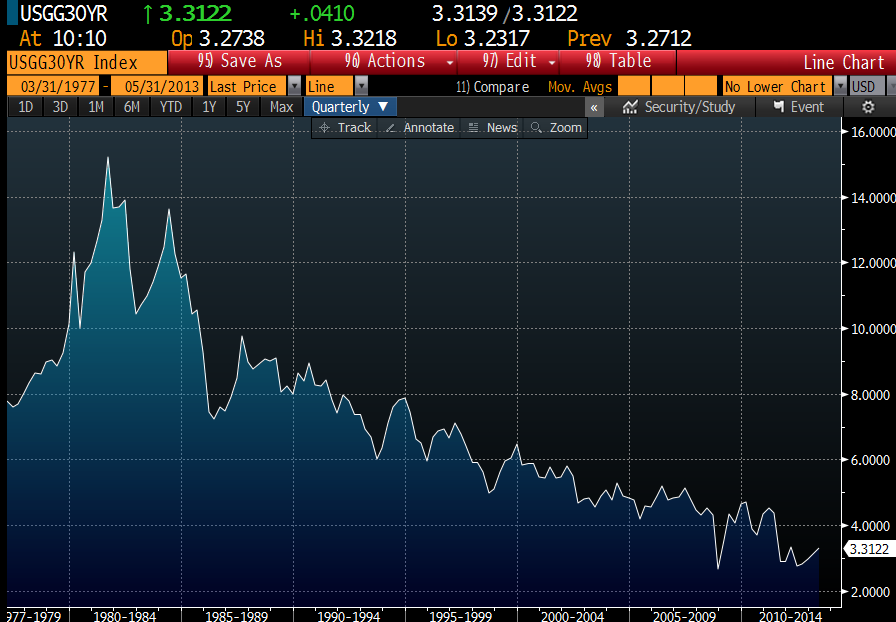
Goldman believes the bond market sell-off is for real. They are forecasting a 2.5% 10 year by the end of the year. The sell-off has been global, as Japanese Government Bonds, UK Gilts, German Bunds have also been hit. FWIW, Bill Gross of PIMCO called it 3 weeks ago when he tweeted “The secular 30-yr bull market in bonds likely ended 4/29/13” 


Morning Report – Fannie Mae comes back to earth 5/30/13

Vital Statistics

  Last Change Percent
S&P Futures  1652.6 5.6 0.34%
Eurostoxx Index 2807.2 20.6 0.74%
Oil (WTI) 92.59 -0.5 -0.58%
LIBOR 0.275 -0.001 -0.40%
US Dollar Index (DXY) 83.7 0.037 0.04%
10 Year Govt Bond Yield 2.14% 0.02%  
Current Coupon Ginnie Mae TBA 101.8 0.4  
Current Coupon Fannie Mae TBA 100.8 -0.2  
RPX Composite Real Estate Index 200.6 0.4  
BankRate 30 Year Fixed Rate Mortgage 3.94    


Markets are higher this morning in spite of a 5.2% sell-off in the Nikkei 225 last night. Q1 GDP was revised downward to 2.4% from 2.5%. Initial Jobless Claims rose to 354,000. Bonds and MBS are down small.
 
Yesterday was the first relatively stable day in the Treasury markets in quite some time, notwithstanding the major sell-off in early Asian trading yesterday morning. Today we are more or less in the same place. 
 
The CFPB has tweaked the Ability to Repay rule a tad, with new guidance for mortgage broker compensation and exempting small lenders that focus on low-income lending. These amendments will take effect Jan 1, 2014.
 
It is tempting to think the the U.S. Treasury yield is being driven by differing interpretations of Bernake’s words. And maybe some of it is. But we are seeing a global sell-off in G7 sovereign debt that started at about the same time.  The US Treasury yield is up 54 basis points since May 1. UK Bonds are up 26 basis points. Japanese Government bond yields are up 31 basis points. That is in spite of a new quantitative easing program by the Bank of Japan – think about that! German Bund yields are up 30 basis points. Everyone started selling off more or less on May 1. My point is that there seems to be more going on in US Treasuries than a simple question over when the Fed is going to start tapering QE. Given the move in world stock markets, it feels like a very big investor (probably a sovereign wealth fund) is doing an asset allocation trade out of G7 debt and into stocks. 
 
Remember Fannie Mae, which was more or less given up for dead? Well, it has rallied about fourteenfold since mid March. It sold off had yesterday, but you can’t deny the move. 30 cents to an intraday high of $5.44. This has been one big speculative toy for the past couple of months, while the big hedge funds are in the prefs. If Fannie Mae survives in some way, shape, or form those bets could pay off. However Fannie Mae is simply sending all of its profits to the government, which is not counting them against money it owes. (They changed the rule last Fall, right before Fannie Mae started turning a profit – what a coincidence). Oh, and before you dismiss it as just another “penny stock” – it sports a market cap of $16.7 billion. Anyway, play in this sandbox at your own risk.
 
Chart:  Fannie Mae (FNMA)


Morning Report – Foreclosures drop again 5/29/13

Vital Statistics:

  Last Change Percent
S&P Futures  1646.2 -8.4 -0.51%
Eurostoxx Index 2794.0 -41.9 -1.48%
Oil (WTI) 94.43 -0.6 -0.61%
LIBOR 0.276 0.003 1.10%
US Dollar Index (DXY) 83.58 -0.516 -0.61%
10 Year Govt Bond Yield 2.14% -0.03%  
Current Coupon Ginnie Mae TBA 101.7 0.3  
Current Coupon Fannie Mae TBA 100.6 0.3  
RPX Composite Real Estate Index 200.2 0.0  
BankRate 30 Year Fixed Rate Mortgage 3.88    


Bond market volatility is the theme of the day (yet again). The 10-year bond yield jumped to 2.23% this morning in late Asian hours. No real news drove the decline, just the general fear that the Fed will start paring back QE sometime this fall.
 
Lender Processing Services reported that home prices are up 1.4% month-over-month and 7.6% year over year. It does appear that the rally is becoming more broad, as states other than the usual suspects are showing the biggest gains. This time around, Georgia leads the way as Atlanta prices increased 2.6% MOM. Arizona was actually in the bottom 10, indicating that perhaps the big professional-driven rally off the bottom has been played out.
 
CoreLogic reported that foreclosures are down 16% YOY and 1% MOM. 52,000 foreclosures were completed in April 2013. In states like Arizona and California, the year-over-year decline is over 50%. The shadow inventory of homes in some state of foreclosure is 1.1 million, compared to 1.5 million a year ago. The judicial states of FL, IL, NJ, NY, and CT still have some work to do, but the rest of the states have largely completed their foreclosures.
 
The sell-off in bonds has created a massive jump in mortgage rates. Now, as the mortgage REITs hedge their books, we are approaching another wave of selling in TBAs as MBS investors hedge their convexity and REITs de-lever. This is going to push mortgage rates even higher. If rates stay here, we should be best-exing into a 3.5% coupon pretty soon.
 

Morning Report: Case-Schiller Home Price Index up 10.9% 5/28/13

Vital Statistics:


  Last Change Percent
S&P Futures  1664.4 13.8 0.84%
Eurostoxx Index 2832.8 37.8 1.35%
Oil (WTI) 95.11 1.0 1.02%
LIBOR 0.273 0.000 0.00%
US Dollar Index (DXY) 83.75 0.045 0.05%
10 Year Govt Bond Yield 2.05% 0.04%  
Current Coupon Ginnie Mae TBA 102.8 -0.3  
Current Coupon Fannie Mae TBA 101.4 -0.3  
RPX Composite Real Estate Index 200.2 0.3  
BankRate 30 Year Fixed Rate Mortgage 3.75    


Markets are higher after equity markets rally worldwide. Bonds and MBS are down again.
 
The S&P Case-Schiller House Price Index rose 1.12% MOM and 10.87% YOY in March. This is the biggest gain since April 2006. Gains were widely distributed, with Phoenix rising 22.5% and New York rising 2.6%. 
 
Chart:  S&P / Case-Schiller Home Price Index:


Jon Hilsenrath of WSJ discusses the Fed’s expectations management issue. The latest FOMC statement inserted language stating that the Fed was ready to increase or decrease purchases as conditions change. During Bernake’s testimony, he refused to rule out tapering QE by Labor Day. It feels as if the market expectations and the Fed are not in sync at the moment, which leads to interest rate volatility.
 
Investors are rotating out of bonds and into balanced funds. Balanced funds will allocate between stocks and bonds and can trade tactically. This could explain some of the “risk on / risk off” behavior we have been seeing. The net result of this could be greater interest rate volatility going forward. After Ben Bernake’s comments last week about ending QE this fall, we saw massive selling in the Treasury futures market (something like 250 contracts being sold in a couple minutes) as stocks rallied. If interest rate volatility is the theme of the market going forward, it makes sense to lock and not float. 
 
Title Insurer Fidelity National Financial (FNF) is buying outsourcing / data firm Lender Processing Services (LPS) in a $2.9 billion cash and stock deal. 

Morning Report – New Home Sales 5/24/13

Vital Statistics:


  Last Change Percent
S&P Futures  1641.0 -9.0 -0.55%
Eurostoxx Index 2765.2 -11.6 -0.42%
Oil (WTI) 93.17 -1.1 -1.15%
LIBOR 0.273 0.000 0.00%
US Dollar Index (DXY) 83.71 -0.094 -0.11%
10 Year Govt Bond Yield 2.01% -0.01%  
Current Coupon Ginnie Mae TBA 103.1 0.1  
Current Coupon Fannie Mae TBA 101.9 0.1  
RPX Composite Real Estate Index 200.2 0.3  
BankRate 30 Year Fixed Rate Mortgage 3.77    


Markets are lower on no real news. Today will be basically a throw-away as the bond market closes at 1:00 pm and most of the Street will be on the LIE by noon. Bonds and MBS are up small
 
Durable Goods orders increased 3.3% in April. Ex transportation, they increased 1.3%. Good numbers.  That said, the manufacturing sentiment reports out of the various Fed banks have been subdued, to say the least. 
 
New Home Sales jumped to a seasonally adjusted annual rate of 454,000. This is 2.3% above the revised March rate and 29% above last year. The median sales price was $271,600 and the average sales price was $330,800, both big increases, indicating more activity is happening at the high end. Strangely, McMansion builder Toll Brothers’ earnings report was on the weaker side compared to its competitors. 
 
So far, the narrative regarding Bernake’s statements in front of Congress has been that the Fed is considering   tapering QE sometime this summer. My take is that is wrong, but we are seeing bear market behavior in bonds right now. Rallies are brief and quickly sold, while sell-offs seem to gather steam. 

Morning Report – The Bernank inadvertently whacks the bond market 5/23/13

Vital Statistics:

  Last Change Percent
S&P Futures  1639.5 -16.1 -0.97%
Eurostoxx Index 2766.1 -68.9 -2.43%
Oil (WTI) 92.66 -1.6 -1.72%
LIBOR 0.273 -0.001 -0.37%
US Dollar Index (DXY) 83.92 -0.433 -0.51%
10 Year Govt Bond Yield 2.00% -0.04%  
Current Coupon Ginnie Mae TBA 103.2 0.2  
Current Coupon Fannie Mae TBA 101.8 0.1  
RPX Composite Real Estate Index 199.5 0.5  
BankRate 30 Year Fixed Rate Mortgage 3.73    


Markets are lower again after yesterday’s massive reversal. Initial Jobless Claims came in at 340,000 down 23k from the week before and 5k below street estimates. Bonds are up about six ticks, which is surprising given that the SPUs are down 16.
 
Yesterday’s moves in the stock and bond markets have a lot of people scratching their heads. I’ll give you my explanation:  Yesterday’s reversal came during Bernake’s testimony, which I was listening to in the background. Bernake started his prepared remarks basically saying that the Fed would be guided by data, and noted that they feel like in hindsight, that they stopped QEI and QEII a little too early. As long as inflation remained below their target rate they felt like they had no reason to stop asset purchases. Bonds rallied early and the yield dropped to 1.89%. Then, during the Q&A, one of the questioners tried to pin down Bernake on when they would slow or stop asset purchases. Bernake repeated that the Fed would be guided by the data. When they see a materially better employment market, they will think about tapering. The questioner then asked if that could be before Labor Day. Bernake replied that if the data improves materially, then sure. Bernake’s body language was “well, it is a theoretical possibility that the labor market could improve dramatically over the summer and I am not going to rule anything out.” The bond market however focused on the statement that the Fed could end QE by Labor Day and sold off. Apparently a big asset allocation trade went through right about the same time where someone sold Treasury futures to buy stocks and that exacerbated the move. The S&P 500 turned on a dime about the same time and did a 40 point intraday swing. 
 
The bond market is just heavy, as it has been since it turned on a dime in the first week of May. Any rally is sold. This is traditional bear market behavior, and I don’t know how long it lasts, but until the market feels different, your borrowers are rolling the dice if they are floating. Note Bene: Bear market rallies are fast and furious, so you should expect increased volatility in rates. In both directions. 
 
The National Association of Realtors reported that existing home sales rose to an annualized pace of 4.97 million in April. Total Housing Inventory rose 11.9% at the end of April to 2.16 million units, a 5.2 month supply. Six months’ inventory is considered “balanced.”  The median existing home price increased to 192,800 in April, up 11% from a year ago. One thing to note is that the outsized activity on the West Coast and places like Phoenix is distorting the median price indices. Most of the activity is concentrated in a handful of hot market where prices are rising rapidly after bottoming last year. The rest of the country is not experiencing that at all. Home prices are up in the low / mid single digits elsewhere. 
 
In contrast to the NAR report, the FHFA released its monthly home price index report, which shows prices rose 1.9% in Q1 and are up 6.7% year over year. The FHFA report looks at the prices of houses with mortgages backed by Fannie Mae and Freddie Mac, which means that a lot of the activity on the West Coast is excluded, because it ignores cash transactions. The FHFA report is more of a “central tendency” report.
 

Morning Report – The Bernank speaks at 10:00 EST 05/22/13

Vital Statistics:

  Last Change Percent
S&P Futures  1669.5 3.9 0.23%
Eurostoxx Index 2817.3 -4.3 -0.15%
Oil (WTI) 95.92 -0.3 -0.27%
LIBOR 0.274 0.000 -0.13%
US Dollar Index (DXY) 83.91 0.044 0.05%
10 Year Govt Bond Yield 1.93% 0.01%  
Current Coupon Ginnie Mae TBA 104.2 0.1  
Current Coupon Fannie Mae TBA 102.8 0.0  
RPX Composite Real Estate Index 199 0.2  
BankRate 30 Year Fixed Rate Mortgage 3.65    


Markets are up again on no real news. Bonds and MBS are more or less flat
 
Mortgage Applications fell 10% last week as the recent rise in interest rates has taken its toll. The refi index was down 12% while the purchase index was down 3%. It appears that the 10 year has found a level here, at least for the short term.
 
McMansion builder Toll Brothers (TOL) reported better than expected earnings this morning. Revenues increased 38%.  Contracts increased 57%. ASPs were up huge – 16%. Backlog was up 69%. Toll’s results more or less mirror what the other homebuilders have reported, although the growth was larger in the builders that focus on starter homes and first move-up buyers. 
 
We had a lot of Fed-speak over the past couple of days. New York Fed President William Dudley said that it will take 3 to 4 months to make a determination over whether the economy is strong enough to stand an end to QE. St. Louis Fed Head James Bullard also said that purchases should continue. The Fed is concerned about the sequester’s effect on the economy, which will mainly be felt over the summer. Finally, the Bernank is scheduled to testify before Congress at 10:00. The minutes of the April 30 meeting will also be released today. 
 
The New York Fed released its mortgage backed securities purchase advice recently. In spite of the hike in interest rates, the MBS purchases stayed the same:  3 million MBS a day, of which the lion’s share is conforming (something like 80%). You would think the Fed would be more aggressive when rates increase and back off when they fall, but that isn’t what they are doing. 
 
It looks like Mel Watt faces an uphill climb to confirmation. The choice is seen as 100% political, while most Republicans think we need a technocrat who understands finance. The fear is that the partisan wrangling and posturing over Watt will poison the well so much that any sort of bipartisan housing bill will be more or less impossible. Principal mods aside, that would probably mean the end of HARP 3.0 which would extend HARP eligibility to late 2009 and 2010 vintages.