Morning Report – breakdown of the government shutdown 09/27/13

Vital Statistics:

Last Change Percent
S&P Futures 1685.0 -7.5 -0.44%
Eurostoxx Index 2913.5 -9.5 -0.32%
Oil (WTI) 102.8 -0.2 -0.21%
LIBOR 0.248 0.000 0.10%
US Dollar Index (DXY) 80.22 -0.307 -0.38%
10 Year Govt Bond Yield 2.63% -0.02%
Current Coupon Ginnie Mae TBA 105.4 -0.3
Current Coupon Fannie Mae TBA 104.7 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.28
Markets are lower ahead of Continuing Resolution Weekend. Personal income rose .4% in August, while personal spending rose .3%. The prior months were revised upward. Bonds and MBS are up.
The government’s new fiscal year begins on Tuesday, and unless Congress comes up with a way to keep the lights on the government will shut down. You have all-out war between Democrats and Republicans and a civil war in the Republican party. Here is the state of play: The House passed a continuing resolution that funds the government through the end of the year, but it contains language that de-funds obamacare. The Senate passed a continuing resolution that funds the government through the end of the year, but it removed the obamacare language and sent it back to the House. So that leaves Boehner with 3 possible outcomes: 1) He can convince the Tea Party Republicans to go along with a clean continuing resolution, 2) He passes a bill with primarily Democratic party support (and that support won’t be free, plus it will probably cost him the Speakership), or 3) He attempts to pass a clean CR and it fails, which shuts down the government. Democrats are confident that any shutdown will be a replay of 1995, where the public sided with Clinton. How to handicap it:  I think the fact that the Republican leadership is so vocal against the rebellious Tea Party republicans is important and it brings them on board. #1 is the most likely scenario, followed by #2. If we do have a shutdown, it will be short.
If the government shuts down, what does that mean for the mortgage markets? Ginnie Mae will be open for business, according to HUD’s contingency plan from 2011, which supposedly would be used in this case. I have yet to see what FHA will do. Bottom line, I don’t foresee any major disruptions to the financial markets. Macroeconomic Advisers estimates that a 2 week shutdown will lop .3% off of 4Q GDP. Mark Zandi of Moody’s estimates that number to be 1.4% if it goes 3 – 4 weeks. (Mark, you didn’t get the Treasury Secretary gig – you don’t need to keep carrying water for the Administration).
Pending Home sales fell 1.6% in August, according to the National Association of Realtors. The NAR blames the drop on an acceleration of home sales in early summer, as buyers accelerated purchase decisions as interest rates began to rise. The NAR is anticipating 2014 sales to be flat with 2013 and median existing home sale prices to increase 5% – 6%. Note that almost half of all home sales right now are all-cash transactions and that number is usually close to 20%. So even if existing home sales are flat next year, year over year, the mortgage business could still improve markedly as distressed / cash sales run their course.
The number of loans in the process of of foreclosure at the end of the second quarter decreased 40% to 744k. This is an interesting statistic, MBA estimates the shadow inventory of homes to be 3.3 million. I know MBA also includes 90 day DQs, which may account for some of the difference – 90 day DQs in judicial states which haven’t been permitted to move to the foreclosure process yet. Other tidibits – the overall percent of loans that were seriously delinquent fell from 15% a year ago to 3.8%. Almost 91% of all loans in the report were current and performing.
Does the high shadow inventory number necessarily mean that cash sales will continue to be half of all existing home sales? Probably not. Professional investors who bought property for rentals are noting the increase in prices, and will certainly think about ringing the register. They won’t be selling to other professional investors, so that inventory will be coming soon. Plus, as we have seen in the D, many of these homes will be bulldozed, not sold.

Morning Report – Distressed sales and cash percentages 09/26/13

Vital Statistics:

Last Change Percent
S&P Futures 1690.2 4.4 0.26%
Eurostoxx Index 2921.3 -6.1 -0.21%
Oil (WTI) 103.1 0.4 0.40%
LIBOR 0.248 0.001 0.20%
US Dollar Index (DXY) 80.51 0.179 0.22%
10 Year Govt Bond Yield 2.65% 0.02%
Current Coupon Ginnie Mae TBA 105.6 0.0
Current Coupon Fannie Mae TBA 104.7 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.29
Markets are higher after initial jobless claims came in at 305k, better than expected and second quarter QDP was revised downward to 2.5%. Personal Consumption Expenditures increased 1.8%. Bonds and MBS are down small.
New Home Sales increased at a 421k pace in August, in line with expectations. This is an increase from July but still on the low side for 2013. Household net worth increased by 1.3 trillion in the second quarter and is now 6 times disposable personal income.
The RealtyTrac August Residential and foreclosure sales report reports that the national medial sales price rose 3% to $175,000, which is a 6 pct increase from a year ago. The median distressed price was $116,000, up 1 percent from a month ago, but down 3% from a year ago. This decline in the price of distressed properties is relatively new and bears watching. All cash purchases represented 45% of all residential sales in August, up from 39% in July and 30% a year ago. No wonder the mortgage banking business is struggling – the refi boom is over, and the percent of puchase business with a mortgage is falling as well.

Morning Report – Bank Rejection Rates 09/25/13

Vital Statistics:

Last Change Percent
S&P Futures 1690.7 -1.8 -0.11%
Eurostoxx Index 2918.0 -4.9 -0.17%
Oil (WTI) 103.9 0.7 0.70%
LIBOR 0.248 -0.003 -1.04%
US Dollar Index (DXY) 80.44 -0.120 -0.15%
10 Year Govt Bond Yield 2.64% -0.01%
Current Coupon Ginnie Mae TBA 105.4 0.0
Current Coupon Fannie Mae TBA 104.5 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.32
Markets are slightly weaker this morning as durable goods orders came in better than expected, but still weak. Ted Cruz continues to tell bedtime stories. Mortgage applications rose 5% as rates fell.
CFPB Director Richard Cordray spoke to the American Banker Regulatory Symposium yesterday. He lamented that consumers cannot sever ties with certain entities, namely debt collectors and mortgage servicers. They will also use the disparate impact theory when determining whether discrimination is taking place, which unfortunately means that FICO is all that matters, and if the value of the underlying collateral in one area is likely to be more volatile than another, tough cookies, you have to lend to both borrowers at the same rate, assuming all other risk factors are the same. The volatility of the underlying collateral is an important issue that the regulators conveniently ignore because it negates the validity of their argument. The speech is basically a shot at mortgage bankers, payday lenders, servicers, debt collectors and other unsavory financial services folks.
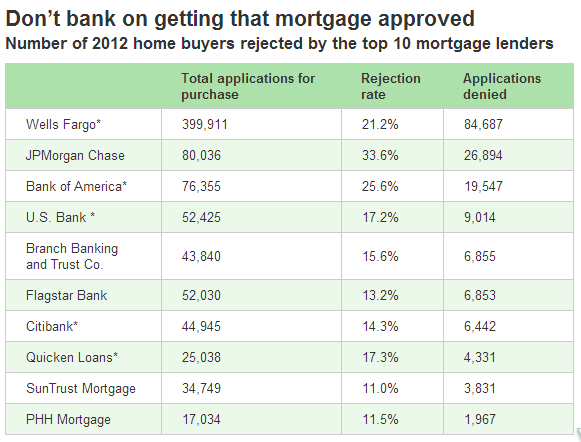
Ever wonder how much banks differ in their loan approval percentages? It turns out that there is a bit of a spread between the big ones and the smaller ones. The biggest banks – Wells, JPM, BOA – have the highest rejection rates, in fact JPM rejects 1/3 of its applications!

So, LOs the next time a borrower says that “Wells or JP Morgan is quoting me X% with so many points, tell them that unless they have a commitment, they are taking a risk going with a big bank. It would be a shame to go all the way through the process, only to get rejected at the last minute.

Moody’s is warning that a government shutdown may slow economic activity and would damage the nation’s credit quality. I suspect Ted Cruz knows that we aren’t going to shut down the government over obamacare, and this “filibuster” – is his last stand on the issue. Once he sits down, we’ll get a continuing resolution and a debt ceiling increase in short order. Certainly the stock market, the bond market, and the US dollar are taking that view. The risk: Democrats demand an end to the sequester and try and stick in tax hikes. I don’t think they do that because Republicans will reject that and then a government shutdown becomes a case of “he said, she said” where Democrats take some risk of getting dirty with the Republicans. Here is a list of cuts that can avert a government shutdown.

Morning Report – Homebuilder earnings 09/24/13

Vital Statistics:

Last Change Percent
S&P Futures 1692.0 -0.7 -0.04%
Eurostoxx Index 2923.4 17.0 0.59%
Oil (WTI) 102.8 -0.8 -0.79%
LIBOR 0.25 0.000 -0.16%
US Dollar Index (DXY) 80.59 0.140 0.17%
10 Year Govt Bond Yield 2.68% -0.02%
Current Coupon Ginnie Mae TBA 105 0.2
Current Coupon Fannie Mae TBA 104.4 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.39
Markets are flattish amidst a couple of big transactions – Applied Materials is buying Tokyo Electron (yes a Japanese company is being bought by an American firm) and there is a possibility of an “IPO” for Chrysler as Fiat and the UAW pension fund debate the value of the company. Bonds continue their post FOMC rally.
We have a couple real estate indices this morning – Case-Shiller increased 12.4% YOY, pretty much in line with forecasts, while the FHFA House Price Index increased 1.0% MOM. The FHFA index is more of a central tendency index because it focuses on homes with conforming mortgages attached to it – in other words, it ignores the jumbo space and cash transaction which are often distressed sales.
We have earnings from a couple of homebuilders today: Lennar (LEN) and KB Home (KBH). Orders dropped 9% on a unit basis, but increased 7% on a dollar basis. Their cancellation rate was 33%.  Revenues increased 29% and average selling prices rose 22% to 299k. KB’s increase in ASPs is due to a strategic shift on their part. The stock is down small premarket. Lennar reported ASPs of 291k, with new orders up 14% on a unit basis and 32% on a dollar basis. Cancellation rate was 18%. The stock is up 1.5% preopen.
Jeffrey Metzger, CEO of KB Home said “The fundamentals of the current housing recovery are firmly in place, supported by low inventory levels, an improving economy, and positive demographic trends. Given these factors, we believe that the recent slower pace of recovery caused by an uptick in mortgage interest rates is a temporary effect and we expect to see steady upward demand for housing as consumers adjust to both higher rates and pricing.”
Stuart Miller, CEO of Lennar said: “We continue to see long-term fundamental demand in the housing market driven by the significant shortfall of new single family and multi family homes built over the last five years. While there may be bumps along the road that may impact the short-term pace of the recovery, the long-term outlook for our business remains extremely bright.”

Morning Report – People don’t understand HARP 09/23/13

Vital Statistics:

Last Change Percent
S&P Futures 1699.3 -3.1 -0.18%
Eurostoxx Index 2914.4 -12.8 -0.44%
Oil (WTI) 104.5 -0.3 -0.24%
LIBOR 0.251 0.001 0.40%
US Dollar Index (DXY) 80.39 -0.038 -0.05%
10 Year Govt Bond Yield 2.73% 0.00%
Current Coupon Ginnie Mae TBA 104.8 0.1
Current Coupon Fannie Mae TBA 103.9 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.42
Markets are lower as they start to worry about the machinations over the debt ceiling and the continuing resolution. Bonds and MBS are more or less flat.
We will have lots of relevant data this week, with Case-Shiller and the FHFA Home Price Index on Tuesday, Lennar and KB Home earnings on Tuesday as well, and the third revision to 2Q GDP on Thursday. Note the Fed took down 2013 GDP projections by 30 basis points in its economic forecast, so maybe they know the revision is going to be bad. The Street is at 2.6%. Don’t forget Q1 GDP started at something like 2.5% and was revised downward to 1.1%.
The tea party wing of the Republican Party is demanding that obamacare be delayed or de-funded as a condition to raising the debt ceiling. Needless to say, this is going nowhere in a Democratically controlled Senate and won’t be signed by the author either. The continuing resolution will be the first hurdle, and Republicans do have something to protect in that it keeps sequestration-level spending in place. The debt ceiling is a messier affair, but Republican leadership is dead-set against defaulting on the debt, so this will get passed one way or the other, but it may cost Boehner his speakership if he passes an increase in the debt ceiling by relying on Democratic votes.
The FHFA is trying to figure out why eligible borrowers are not taking advantage of HARP. There seems to be this perception that you have to be delinquent to take advantage of it, which is false. LO’s take note.

Morning Report – Fed may move in October 09/20/13

Vital Statistics:

Last Change Percent
S&P Futures 1715.4 -2.0 -0.12%
Eurostoxx Index 2927.8 -8.4 -0.28%
Oil (WTI) 105.7 -0.7 -0.64%
LIBOR 0.25 -0.001 -0.24%
US Dollar Index (DXY) 80.46 0.083 0.10%
10 Year Govt Bond Yield 2.75% 0.00%
Current Coupon Ginnie Mae TBA 104.8 -0.2
Current Coupon Fannie Mae TBA 103.8 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.37
Slow news day. Markets are taking a breather after a tumultuous week. There are no economic data this morning, and bonds / MBS are flat.
Federal Reserve Bank of St. Louis President James Bullard told Bloomberg TV that Wednesday’s decision not to slow bond buying was a “close call” and and a “small” tapering is possible next month. Given that there is no press conference scheduled after the Oct Fed meeting and no economic forecasts, this is a bit of a surprise. That said, if the Fed is in fact contemplating moving at the next meeting, then this rally in bonds will probably prove to be very short-lived. LOs, is you have customers on the fence, get ’em locked.
Wells is out with a bearish call on the S&P 500. Their end of year call on the S&P? 1440, down 16% from here. The thesis:  the market growth has been all multiple expansion and earnings are going to disappoint. Gina Adams is trying to become the next Elaine Gazarelli.
Speaking of earnings, we are now in the “oh crap” season, where companies who are going to miss their quarterly estimates begin to fess up. Earnings season officially starts in 3 weeks with Alcoa on 10/8. Last Wed, Oracle took advantage of the FOMC distractions to announce they were going to miss.
Warren Buffett called the Fed the “greatest hedge fund in history.” It is generating 80 and 90 billion a year in revenue for the US government.  I bet Ben is thinking “hey, can I get 2 and 20?”

Morning Report – Party at the Fed 09/19/13

Vital Statistics:

Last Change Percent
S&P Futures 1721.8 4.0 0.23%
Eurostoxx Index 2940.7 31.7 1.09%
Oil (WTI) 108.2 0.1 0.07%
LIBOR 0.25 -0.002 -0.89%
US Dollar Index (DXY) 80.2 -0.042 -0.05%
10 Year Govt Bond Yield 2.70% 0.01%
Current Coupon Ginnie Mae TBA 105 1.3
Current Coupon Fannie Mae TBA 104.2 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.42
Markets are higher this morning after yesterday’s furious rally on the Fed’s decision to keep asset purchases in place. The 10 year had a trading range of over 30 basis points in yield yesterday. Initial Jobless Claims increased to 309,000. Bonds and MBS are up small.
The FOMC statement was obviously a surprise, and it is clear from the reaction in the markets that a LOT of people were leaning short heading into the announcement. What does that mean for rates going forward? The markets will now begin to fret about the December meeting, which isn’t going to be bond bullish. I think if you are considering locking right now, you do it. 2.7% seems to be resistance on the 10 year, and we could be looking at a 2.7% – 3.0% trading range. At these levels, take the money and run.
The Fed’s decision certainly provides support for the theory that the Fed was really targeting leverage with its announcement last Spring. The economic data has never supported a reduction of stimulus, and the Fed has been consistently too high with its economic forecasts. The thing is, they can’t un-ring the bell – so people are not going to be piling into levered curve flattening trades. REITs have significantly de-leveraged. Mission Accomplished.
The Fed took down its forecasts again, with the 2013 GDP range now 2.0% – 2.3% from 2.3% – 2.6% in June. Unemployment’s forecast ticked down as well, from a range of 7.2% – 7.3% to 7.1% to 7.3%. Ben Bernanke was asked in the press conference about the labor force participation rate and how it seemed to be driving unemployment. Bernanke acknowledged that there is more to the labor picture than simply the headline unemployment number, and also stressed that these are guideposts, not thresholds. In other words, if unemployment gets to their 7% target, but it is due to the wrong reasons (a drop in the participation rate), then the Fed may decide to remain accomodative.
The beatdown goes on… Wells Fargo is cutting 1,800 jobs in its mortgage unit, in addition to the 3,000 announced earlier this year.

Morning Report – Taper Day 09/18/13

Vital Statistics:

Last Change Percent
S&P Futures 1698.8 0.5 0.03%
Eurostoxx Index 2907.4 16.4 0.57%
Oil (WTI) 105.8 0.4 0.39%
LIBOR 0.252 0.001 0.20%
US Dollar Index (DXY) 81.14 0.001 0.00%
10 Year Govt Bond Yield 2.86% 0.01%
Current Coupon Ginnie Mae TBA 103.7 0.0
Current Coupon Fannie Mae TBA 102.8 -0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.48
Markets are flattish ahead of the FOMC meeting this afternoon. The announcement is expected around 2:00pm, so don’t try and lock anything around that time period. Bonds and MBS are down small.
Mortgage applications rose 11.2% last week, which was a big increase after a depressed short Labor Day week. The refi index jumped 18% as rates ticked down a little. The purchase index was up 2.5%.
Housing starts and building permits came in lower than expected, with housing starts at an annualized 891k and permits at an annualized 918k. SFR continued to increase while multi-fam dipped. Sub – 1 million levels in housing starts is still a highly depressed level. After touching 1 million units in March, activity has been slowing. You can see from the chart we have been underbuilding for a long time. I guess you won’t see a major increase in starts until the first time homebuyer returns to the market and that is going to be jobs-driven. In related news, the National Association of Homebuilder Confidence Index was flat last month, but still at post-crisis highs. The builders are also noting that momentum seems to have stalled for the moment.

Certainly the Fed is noticing the drop-off in housing sector activity as rates have risen. This will probably make them want to maintain current purchases of MBS and cause them to lower Treasury purchases only. The consensus seems to be the “tiny taper” scenario, where the Fed cuts Treasury purchases by $10 billion a month starting in October.
The SEC is going to force companies to disclose the ratio of CEO pay to the median pay of employees at the firm. Glad to see the SEC is on class warfare beat – much more important than, say, doing something about high frequency trading  /sarc.

Morning Report – Inventory still tight in CA 09/17/13

Vital Statistics:

Last Change Percent
S&P Futures 1692.1 0.9 0.05%
Eurostoxx Index 2888.0 -6.7 -0.23%
Oil (WTI) 105.9 -0.7 -0.64%
LIBOR 0.252 0.000 0.04%
US Dollar Index (DXY) 81.15 -0.146 -0.18%
10 Year Govt Bond Yield 2.83% -0.03%
Current Coupon Ginnie Mae TBA 104.1 0.1
Current Coupon Fannie Mae TBA 103.1 0.2
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.53
Markets are flattish as we head into Day 1 of the FOMC meeting. We should get the actual announcement tomorrow around 2:15 pm. Bonds and MBS are rallying as the market continues to digest the fact that Summers won’t be the next Fed Chairman.
The Consumer Price Index came in at .1% month-over-month, below expectations, and frankly below what the Fed would like to see. As long as (a) there are no bubbles and (b) there is no inflation, the Fed will likely try and err on the side of accommodation.
That said, I believe this reprieve we have been given in rates will be short-lived. Don’t lose the forest for the trees – rates are going up, and if you have any borrowers who have been on the fence or who were floating, now is a good time to lock.
The California Association of Realtors reported that increasing mortgage rates are starting to bite as activity slipped 2%. Prices are still increasing though, as the median home price hit $441k, the highest since Dec 2007. Inventory is improving in the sub 750k bucket, although month’s supply is still extremely low at just about 3 months.

Morning Report – Larry Summers is out, ushering in the third term of Alan Greenspan 09/16/13

Vital Statistics


Last Change Percent
S&P Futures  1688.6 3.7 0.22%
Eurostoxx Index 2893.2 26.1 0.91%
Oil (WTI) 106.2 -2.0 -1.86%
LIBOR 0.252 -0.002 -0.81%
US Dollar Index (DXY) 81 -0.449 -0.55%
10 Year Govt Bond Yield 2.79% -0.10%  
Current Coupon Ginnie Mae TBA 103.8 0.0
Current Coupon Fannie Mae TBA 103.3 0.7
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.57


Markets are higher after Larry Summers withdrew his name from consideration for the Fed Chairmanship. Bonds and MBS are rallying hard, with the 10 year yield down 10 basis points.
 
Janet Yellen is a Greenspan clone, as is Bernanke. Summers would have ended QE a bit earlier than Yellen would have. I have to say I am skeptical of the 10 year here at 2.79%. If you wanted to refi and missed the boat, the market just let you back in. I would take advantage of it, because the secular story on bonds is unchanged. LO’s should go back and contact their borrowers who are on the fence and let them know they just got a gift that won’t last forever.
 
Does this change what the Fed will do on Tuesday and Wed?  Probably not. The consensus seems to be a taper of $10 billion a month, which will be Treasuries and not MBS. 
 
We have some industrial numbers today, with the Empire State Manufacturing Index, Industrial Production, Capacity Utilization, and Manufacturing Production. Later this week, we will get housing starts, building permits, and existing home sales. All important data for us.
 
The CFPB made some changes to the QM rule.  Here is a summary.