Morning Report: James Bullard explains his dissent

Vital Statistics:


Last Change
S&P futures 3012.25 5.25
Oil (WTI) 58.67 0.54
10 year government bond yield 1.78%
30 year fixed rate mortgage 4.00%


Stocks are up this morning on no real news. Bonds and MBS are flat.


Existing home sales rose 1.3% in August, according to NAR. Sales are up 2.6% from a year ago to a seasonally adjusted annual rate of 5.49 million units. The median existing home price rose to $278,200, which was up 4.7%. “Sales are up, but inventory numbers remain low and are thereby pushing up home prices,” said Yun. “Homebuilders need to ramp up new housing, as the failure to increase construction will put home prices in danger of increasing at a faster pace than income.” Inventory did fall to 1.86 million units, which represents a 4.1 month supply. In the “every dog has its day” category, the Northeast led the pack with a 7.6% increase in sales although the median home prices was flat. The Northeast still has a glut of higher priced inventory it needs to work through.


In other economic news, the index of leading economic indicators was flat in August, and initial jobless claims came in at 205,000. The Fed’s balance sheet increased to $3.845 trillion in assets.


St. Louis Fed President James Bullard explained his dissent on Wednesday’s FOMC vote. While the Committee ended up easing by 25 basis points, Bullard wanted to cut rates by 50 basis points.


First, there are signs that U.S. economic growth is expected to slow in the near horizon. Trade policy uncertainty remains elevated, U.S. manufacturing already appears in recession, and many estimates of recession probabilities have risen from low to moderate levels. Moreover, the yield curve is inverted, and our policy rate remains above government bond yields for nearly every country in the G-7.

Second, core and headline personal consumption expenditures (PCE) inflation measures continue to run some 40 to 60 basis points, respectively, below the FOMC’s 2% inflation target. Market-based measures of inflation expectations continue to indicate expected longer-term inflation rates substantially below the Committee’s target. This is occurring despite the 25 basis point cut in July and the 25 basis point cut that was expected for the September meeting. While the unemployment rate is low by historical standards, there is little evidence that low unemployment poses a significant inflation risk in the current environment.


The quote about manufacturing is interesting. Industrial production rose 60 basis points last month and manufacturing production was up 50 bps. Capacity utilization rose 40 basis points as well. We had one reading on the ISM that came in at 49.1, which was technically below 50, where manufacturing is neither contracting nor expanding. For all intents and purposes, it was flat given the inherent error built into these sentiment surveys. Historically, a manufacturing ISM reading of 42 corresponds with an overall recession. FWIW, the ISM reading of 49.1 usually corresponds with a GDP growth rate of 1.8%. In other words, hardly recessionary, and manufacturing represents only about 13% of the US economy to begin with. The statement about G7 rates is probably what is driving things – the Fed is simply following the markets.


Home equity rose 4.8% in the second quarter, or about 428 billion. Negative equity fell by 9%, or about 151,000 homes. The home equity number is a new record, and home equity has doubled since the depths of the housing recession. You can see below which parts of the country still have a negative equity issue to work through.


corelogic home equity

Morning Report: The Fed cuts rates.

Vital Statistics:


Last Change
S&P futures 3007.75 0.25
Oil (WTI) 59.37 1.24
10 year government bond yield 1.77%
30 year fixed rate mortgage 4.00%


Stocks are flat after the Fed cut rates yesterday. Bonds and MBS are up small.


As expected, the Fed cut rates 25 basis points amidst concerns about capital expenditures and investment. The decision was 7 to 3, with one dissenter (Bullard) who wanted a 50 basis point cut and two dissenters (George and Rosengren) preferring to maintain current policy. The economic projections were largely unchanged, with a few upward tweaks to 2019 and 2021 GDP estimates, and a slight change to unemployment. Inflation measures were unchanged. The Fed Funds estimates were revised downward anywhere from 25 – 37 basis points compared to the June dot plot.


Sep-June dot plot comparison


Powell was noncommittal on future moves: “There will come a time, I suspect, when we think we’ve done enough. But there may also come a time when the economy worsens and we would then have to cut more aggressively. We don’t know.” In other words, we are data-dependent. The German Bund has sold off a touch, with the yield moving from negative 70 basis points a couple of weeks ago to negative 50 basis points now. FWIW, the Bund seems to be leading the dance.


Bonds initially sold off on the move, with the 10 year rising 4 basis points to 1.8%. This morning, we are back down to where we started. The December Fed Funds futures are predicting a 14% chance of another 50 basis points in cuts, a 49% of a 25 bp cut and a 37% probability of no further changes. Trump weighed in on the cut as well tweeting: “A terrible communicator. Jay Powell and the Federal Reserve Fail Again. No ‘guts,’ no sense, no vision!”


The spike in overnight repo rates (which got as high as 10% at one point) has raised an interesting question: The overnight repo rate is supposed to be the index that replaces LIBOR. While the complaint about LIBOR was the presence of some jiggery-pokery by the big banks, is the the cure (an index that can spike 800 bps in a day) really better than the disease? Note this flows through the whole mortgage ecosystem, with MBS repo rates, ARM pricing, warehouse line pricing, etc. It might not yet be ready for prime time.

Morning Report: Housing is coming back

Vital Statistics:


Last Change
S&P futures 3003.75 4.25
Oil (WTI) 58.37 -0.94
10 year government bond yield 1.78%
30 year fixed rate mortgage 4.00%


Stocks are flattish as we await the FOMC decision at 2:00 pm EST today. Bonds and MBS are up.


Housing starts increased 12.3% MOM and 6.6% YOY to a seasonally adjusted annual rate of 1.36 million. This is the highest in 12 years. July was revised upward as well. Building Permits rose 7.7% MOM and 12% YOY to 1.4 million, which is close to historical levels (non-population adjusted). This data seems to comport with the MBA’s 30% rise in purchase activity. Permit activity increased the most in the Northeast, while falling in the Midwest.


housing starts


Mortgage applications were flat last week despite a huge back up in rates. There was also an adjustment for Labor Day, so that will affect the numbers. Purchases rose 6%, while refis fell 4%. The average rate on a 30 year fixed rose 19 basis points to 4.01%, and government loans increased share.


CFPB Chair Kathy Kraninger believes her job security is unconstitutional and supports a Supreme Court review of a case pending before the 9th Circuit. Essentially, Dodd-Frank made the head of the CFPB basically untouchable – the President can only fire “for cause” and not at the discretion of the White House. “From the Bureau’s earliest days, many have used the uncertainty regarding this provision’s constitutionality to challenge legal actions taken by the Bureau in pursuit of our mission,” Kraninger wrote to staff. “Litigation over this question has caused significant delays to some of our enforcement and regulatory actions. I believe this dynamic will not change until the constitutional question is resolved either by Congress or the Supreme Court.” Given that the case is currently in front of the liberal 9th Circuit (aka the Nutty Ninth) the current structure will almost certainly be upheld and it will go to SCOTUS.


Some inside-baseball stuff: Despite the bet that the Fed will cut rates to a range of 175-200 basis points today, the Fed had to intervene yesterday to prevent the Fed Funds rate from breaching the top of the current 200-225 basis point range. The cause was a shortage of dollars in the money markets ahead of Q3 interim tax payments and a big Treasury bond issue. This caused overnight repo rates to surge to 500 basis points on Monday, and the punch line is that this problem might push the Fed to increase the size of its balance sheet, which means more QE. This stems from a change in how the Fed mechanically manages the Fed Funds rate in the immediate aftermath of the financial crisis. How will it affect mortgage markets? Not directly, however issues with financing / hedging and rate volatility will negatively impact mortgage rates, at least at the margin.


repo rates

Morning Report: New home activity up 33%

Vital Statistics:


Last Change
S&P futures 2995.5 -6.25
Oil (WTI) 62.07 -0.84
10 year government bond yield 1.83%
30 year fixed rate mortgage 4.03%


Stocks are lower this morning as the markets continue to digest the Saudi oil situation. Bonds and MBS are up.


The FOMC begins its two day meeting today. The Fed funds futures further discounted the chance of a rate cut announcement tomorrow to 63% from 73% a day earlier.


Industrial Production rose 0.6% in August, and manufacturing production rose 0.5%. Both estimates were well in excess of street expectations. Capacity utilization rose to 77.9%. Pretty healthy numbers, and certainly don’t demonstrate that trade wars are killing the manufacturing economy.


New home purchase activity was up 33% on a YOY basis in August. “New home purchase activity was robust in August, as both mortgage applications and estimated home sales increased from a year ago,” said Joel Kan, MBA Associate Vice President of Economic and Industry Forecasting. “Recent increases in new residential housing permits and housing starts, lower mortgage rates, and a still-strong job market all bode well for the new home sales outlook.” This is a bullish sign for the economy, as we have underbuilt for years. New Home Sales has been in the 600k – 700k range recently, which is at levels last seen in the mid 90s.


new home sales


That said, the population has grown, so mid-90s levels doesn’t really support the demand out there. Adjusting for population, the historical average would equate to about 900k new homes sold, or about 30% higher than here.


FHFA Director Mark Calabria was interviewed on Bloomberg TV on the GSEs. It looks like they will hit the market to raise capital by the end of 2020. The first order of business is to end the net worth sweep, which will allow them to build capital. FHFA and Treasury haven’t settled on a number for the capital increase yet. Fannie Mae stock was up a touch on the interview.

Morning Report: Oil markets and the Fed

Vital Statistics:


Last Change
S&P futures 3000.5 -9.25
Oil (WTI) 60.57 5.44
10 year government bond yield 1.85%
30 year fixed rate mortgage 3.98%


Stocks are lower this morning after an attack on a Saudi Aramco oil facility sent oil prices up nearly 20%. Bonds and MBS are up.


A Saudi Aramco facility that represents about 5% of global oil output was attacked, which caused the biggest spike in oil prices since the 1991 Gulf War. Saudi Aramco estimates that it will take months to bring that capacity back on line. A Yemeni movement aligned with Iran is claiming responsibility for the attack. President Trump has announced that the US Strategic Petroleum Reserve could be used to mitigate the effect on oil prices, and the US stands “locked and loaded” to prevent future attacks. While Iran has denied responsibility, cruise missiles may have been involved in the attack, which means Iranian technology. Iran and Saudi Arabia have been enemies for years and have been fighting a war by proxy.


A spike in oil prices has the potential to be inflationary, however it would more likely depress growth since it would act as a tax. This will probably push the Fed to cut rates as opposed to raise them to fight potential inflation. US consumers will be somewhat insulated, since most of the country gets its supply from US West Texas Intermediate which is a US-only market. Consumers on the East Coast will feel an effect since they get their oil from the North Sea Brent market, and many in the Northeast rely on heating oil. Front month heating oil contracts are up 8% pre-open.


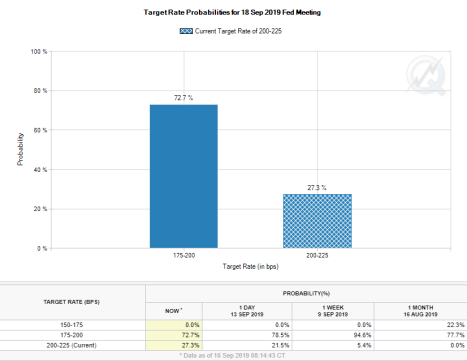
Aside from the issues in the energy space, the big even this week is the FOMC meeting on Tuesday and Wednesday. The Sep fed funds futures have made quite the reversal over the past month, going from a 100% chance of a rate cut (the only uncertainty was over whether it would be 25 or 50 basis points) to a roughly 25% chance they do nothing and a 75% chance they cut by 25 basis points.


fed funds futures


The action in the Fed announcement Wednesday will undoubtedly be in the dot plot (which is the Fed Funds forecast) and the GDP forecast. A potential war in the Middle East has got to affect the numbers, and it will be interesting to see whether they bump up the inflation numbers and / or take down the GDP estimates. Regardless, political uncertainty tends to be negative for business, so I would expect to see more dovishness in the Fed Funds futures.


Last week was brutal for mortgage rates, as the average rate on the 30 year fixed rate mortgage rose 20 basis points last week. It probably represents a technical reaction to the massive rally we have seen in rates this year already. “These sorts of bad performances are most often seen in the wake of stellar performances,” said Matthew Graham, chief operating officer of Mortgage News Daily. “August was the best month for mortgage rates, and 2019 has been the best year since 2011. And that’s precisely why this terrible week is possible: It’s largely a technical correction to the feverish strength in August.” In other words, markets don’t go straight up and they don’t go straight down. Volatility begets volatility and you will see massive rallies in the context of a bear market and vice versa. Remember that volatility in rates is bad for MBS investors in general and that will flow through to rates.

Morning Report: Bonds down on trade progress with China

Vital Statistics:


Last Change
S&P futures 3017.5 5.25
Oil (WTI) 55.37 0.44
10 year government bond yield 1.83%
30 year fixed rate mortgage 3.90%


Stocks are higher this morning after further progress on trade talks with China. Bonds and MBS are down.


China walked back some proposed tariffs on US agricultural products after Trump agreed to delay some additional tariffs. Commodities in general are up on the news.


Retail Sales rose 0.4% MOM in August, according to Census. July was revised upward to an increase of 0.8% from an increase of 0.7%. This was the back-to-school shopping season, so it gives a good indication that this year’s holiday shopping season will be strong as well. Given that consumption accounts for 70% of GDP, we might see some upward revisions in Q3 and Q4 estimates.


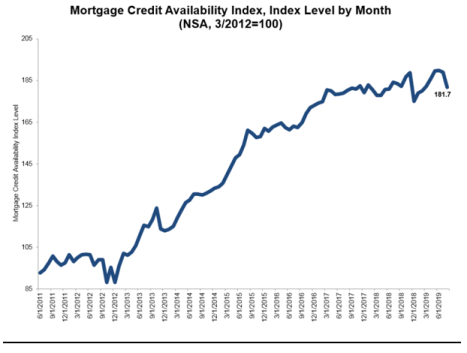
Mortgage credit availability declined in August, according to the MBA. “Credit supply declined across the board in August, even as mortgage rates fell and application activity picked up, particularly for refinances,” said Joel Kan, MBA’s associate vice president of economic and industry forecasting. “Last month’s decrease was the largest since December 2018, and also the first tightening we have seen for conventional loans all year. We anticipate some weakening of the job market in the year ahead as economic growth cools. It’s possible some lenders may be tightening credit in expectation of a slowdown.” Some contraction was expected for VA due to the new rules, but it is surprising to see it in the other buckets.


MCAI


The Trump Admin is working to end Fannie and Freddie’s net profits sweep in September. “We expect a deal prior to Sept. 30 in which Fannie and Freddie will stop paying a quarterly dividend to Treasury,” Cowen Managing Director Jaret Seiberg wrote in the note. “Instead, they will pay a commitment fee for the outstanding preferred capital line. This means they can retain the rest of their profits in order to rebuild capital.”

Morning Report: ECB cuts rates and bonds rally.

Vital Statistics:


Last Change
S&P futures 3009.5 5.25
Oil (WTI) 54.37 -1.44
10 year government bond yield 1.68%
30 year fixed rate mortgage 3.89%


Stocks are higher this morning after the European Central Bank cut rates and announced new stimulus measures. Bonds and MBS are up.


The European Central Bank cut its deposit rate to -50 basis points from -40 bps and re-instated bond purchases of 20 billion euros a month. This is sending down yields, with the German Bund now trading at -62 basis points. Separately, the Bank of Japan is also looking at measures to push their negative interest rates even lower.


Inflation remained under control with the consumer price index up 0.1% MOM / 1.7% YOY. The core rate, which strips out food and energy rose 0.3% MOM / 2.4% YOY. Medical care and shelter drove the increase in the index, while lower energy costs pushed it down.


Initial Jobless Claims fell to 204,000 in the holiday shortened week.


Treasury Secretary Steve Mnuchin said that the US is “seriously considering” issuing a 50 year bond. “We would do this in a way that if there is demand it’s something that we would meet. I personally think it would be a good thing to expand the U.S.′ borrowing capabilities,” Mnuchin said. “I would say it’s obviously quite attractive for us to extend and derisk the U.S. Treasury borrowing. So we’re also looking at extending the weighted average maturity of the Treasury borrowing to derisk this for the U.S. people.” Mnuchin also pushed back against Trump’s view that we need negative interest rates in the US, as negative interest rates wreak havoc on bank earnings, and a weak banking sector does not make a foundation for a strong economy.


Separately, Mnuchin said that the Trump Administration has approved the plan to reorganize the GSEs. “We are actively negotiating an amendment try to get it done by the end of the month” What “actively negotiating an amendment” means is unclear, but it probably refers to the net worth sweep of Fannie and Freddie’s profits to Treasury. Since that was done via executive order during the Obama administration, it should be able to be undone the same way. Full legislation is probably going to be impossible heading into an election year, judging by the way testimony went in the Senate.

Morning Report: Trump calls for negative interest rates

Vital Statistics:


Last Change
S&P futures 2983.5 5.25
Oil (WTI) 57.96 0.44
10 year government bond yield 1.73%
30 year fixed rate mortgage 3.85%


Stocks are up this morning on no real news. Bonds and MBS are flat.


We saw a big uptick in rates yesterday, with not much of a catalyst. It could just be position-squaring ahead of the expected stimulus announcements tomorrow from the ECB, although some pointed to the government bond auction. Regardless, these things happen. While the path of least resistance for interest rates clearly seems to be down, there will be inevitable retracements along the way – markets don’t go straight up or straight down.


Mortgage applications increased 2% last week as purchases rose 5% and refis increased about half a percent. “Mortgages rates continued to decline over the holiday-shortened week, with the 30-year fixed rate decreasing five basis points and remaining near three-year lows,” said Joel Kan, MBA Associate Vice President of Economic and Industry Forecasting. “Refinances were essentially unchanged, up just 0.4 percent, but August overall was the strongest month of activity so far in 2019.”


Steve Mnuchin, Mark Calabria, and Ben Carson appeared before the Senate yesterday to discuss GSE reform. The discussion fell predictably along partisan lines, with the left fretting about affordable housing while the right wanted to reduce the government’s footprint and risk in the system.


Meanwhile, Trump called on the “boneheads” at the Fed to cut interest rates, even below 0% if necessary. Trump is arguing that we should lower rates considerably in order to refinance our government debt into longer term loans, say 50 or 100 years. Note that cutting interest rates to 0% will wreak havoc on the banking system, as Europe is finding out. Check out the chart of Deutsche Bank, which has been annihilated by negative interest rates.


Deutsche Bank


Mortgage fraud decreased in the second quarter, according to CoreLogic.

Morning Report: Fannie Mae surges on reform optimism

Vital Statistics:


Last Change
S&P futures 2973.5 -5.25
Oil (WTI) 58.46 0.44
10 year government bond yield 1.64
30 year fixed rate mortgage 3.77%


Stocks are lower this morning on no real news. Bonds and MBS are flat.


Steve Mnuchin is scheduled to testify before the Senate Banking Committee this morning regarding housing reform and the role of Fannie and Freddie. Mark Calabria, who runs the FHFA and Ben Carson who runs HUD will also join him. Note that Fannie and Freddie surged 35% yesterday on a Compass Point piece that expressed optimism for a shareholder suit and Mnuchin said that they were closer to retaining their earnings. You might want to keep an eye on the screen this morning if you hold these stocks.


Fannie mae stock


Small Business Optimism fell in August as respondents tempered their optimism about the future. Much of this was due to the about-face at the Fed, and fears that they might know something everyone else does not. Despite the drop in expectations, the small business labor market improved, with firms hiring .19 workers on average, and many finding it difficult to hire qualified workers. Small business also increased capital spending, which indicates optimism about the future. So, despite the dip in optimism, firms are still spending like the expansion will continue. One other data point: credit availability remains a non-problem. Only 4% of small businesses reported that their borrowing needs were not met, which is more or less a historical record. So, don’t expect much additional juice from rate cuts, as there is already more than enough credit.


The Chinese government removed the foreign cap on investments, although this is largely a symbolic move, as the current limit presents no constraint. That said, it is hard to avoid the thought that the Chinese government is looking for some greater fools out there for their banking system to sell assets to. Despite the talk about the yuan becoming a reserve currency, the Chinese government probably won’t want to give up the amount of control required.


Delinquency rates continue to fall, according to CoreLogic. The 30 day delinquency rate fell 30 basis points to 4% in June. The foreclosure rate fell 10 bps to 0.4%. We did see an uptick in a few states that wasn’t natural disaster related: VT, NH, MN, and ND.


Corelogic delinquencies.


Morning Report: More GSE reform.

Vital Statistics:


Last Change
S&P futures 2990.5 9.25
Oil (WTI) 56.96 0.44
10 year government bond yield 1.59
30 year fixed rate mortgage 3.72%


Stocks are higher this morning on no real news. Bonds and MBS are down small.


No economic data today, and this week should be relatively data-light, with retail sales on Friday the only potential market-moving number. No Fed-speak as we are in the quiet period ahead of next week’s meeting.


Jerome Powell vowed to act “as appropriate” to maintain the current US expansion, which was largely taken as an admission the Fed will cut rates another quarter point at next week’s meeting. The Fed funds futures are pricing this in as a certainty, although there is disagreement within the Fed over whether it is necessary to cut rates given the strong consumer spending. He also threw cold water on political considerations affecting monetary policy. “Political factors play absolutely no role in our process, and my colleagues and I would not tolerate any attempt to include them in our decision-making or our discussions,” he said. “We are going to act as appropriate to sustain the expansion.” This was presumably in response to comments from ex-NY Fed president William Dudley to  “consider how their decisions will affect the political outcome in 2020.”


Interesting data point: Compass Point Analytics upped their price target for Fannie Mae stock to $7.75. which is almost 3x the current trading price of $2.71. Fannie Mae stock got hit last week on disappointment with the lack of specifics in the government’s housing reform plan.


Despite the disappointment from Fannie Mae stockholders and pref holders, the housing industry generally likes what the saw in the plan. “The reports recognize the need to better coordinate the roles of FHA and the GSEs,” Mortgage Bankers Association CEO Robert Broeksmit said. “Such coordination must preserve affordable financing options for a wide range of borrowers and reflect the vital role FHA plays in the larger housing finance system.” Talks about getting rid of the GSEs altogether seem to be over: “Both in the Obama administration and during periods of bipartisan negotiations the focus was on whiteboarding a totally new system,” said David M. Dworkin, who was a senior adviser in the Treasury Department on housing finance during the Obama and Trump administrations. “It is too hard. The current system is too embedded and the unintended consequences are too unpredictable.” The GSE affordable housing goals would also go away, to be replaced by a fee paid to HUD, who would then distribute the funds themselves. This is likely to be a non-starter with Democrats.


Mortgage interest deductions fell 62% last year as tax reform encouraged most people to take the standard deduction instead of itemizing.