Morning Report – Whither the GSEs

Vital Statistics:

  Last Change Percent
S&P Futures  1625.8 -2.9 -0.18%
Eurostoxx Index 2768.2 -16.5 -0.59%
Oil (WTI) 95.83 -0.8 -0.82%
LIBOR 0.275 0.000 0.00%
US Dollar Index (DXY) 82 0.103 0.13%
10 Year Govt Bond Yield 1.79% 0.02%  
Current Coupon Ginnie Mae TBA 105.9 0.2  
Current Coupon Fannie Mae TBA 104.1 0.1  
RPX Composite Real Estate Index 195 0.3  
BankRate 30 Year Fixed Rate Mortgage 3.54    


Markets are slightly weaker this morning.  Initial Jobless Claims came in at 323,000, better than expected. Bonds and MBS are up small.

I was surprised by the magnitude of last Friday’s reaction to the jobs report and the persistence. The jobs report was good, but not great. I do not see anything in the report to prompt the Fed to end QE early. Perhaps the strength in the equity market is causing people to rotate out of stocks and into bonds. If you believe in technicals, you might be looking for the 10 year yield to do a 50% retracement, hit 1.85% and then bounce back.

Tonight is the Fannie / Fred MBS roll as we go from May to June. MBS prices will look like they just fell tomorrow morning, but it is just the roll.

Freddie Mac reported $4.6 billion in earnings in the first quarter, its second-largest in history. They required no Treasury draw and paid $5.8 billion to the government in Q1. So far, they have paid $29.6 billion. This is after Fannie Mae reported $7.6 billion in Q4.  One almost certainty is that G-fees are going up. The government wants to “crowd in” private capital and price credit risk more in line with private mortgage insurers. The game for originators going forward may well be to stick with qualified mortgage (QM) loans and compete with the government on the guarantee fee. The other sense I got from the conference is that QM is not enough of a safe harbor to really encourage lending outside of the QM box. Which means that anyone with dinged credit is more or less stuck in the FHA box. 

The sense I got from the MBA Secondary Conference is that despite the Obama Administration’s white paper that claims they would like to replace Fannie and Fred with some private entity, they are slow-walking reform. Certainly Mel Watt was not nominated to preside over the orderly dissolution of the GSEs. After the Administration changed the terms of the deal, the GSEs now just distribute all of their profits to the government, which has created a slush fund for general government purposes. And $13 billion a quarter isn’t chump change. I think at the end of the day, Fan and Fred are going nowhere and will stay on as quasi-nationalized entities until they are fully re-capitalized and then they will be sold. 

The big questions regarding Mel Watt as the new FHFA Chairman concern principal mods and an extension of the HARP window (HARP 3.0). As of now, HARP eligibility does not extend to anything originated or refinanced after  May 31, 2009. There is talk that the window might be extended to allow people who took out conforming loans in 2009 and 2010 to be HARP eligible. Also, there is talk of allowing people to “re-HARP.” Anyway we could see another refi boom if Watt is confirmed. Regarding the principal mods, CBO gave FHFA the ammunition to permit mods. If Watt is rejected, expect Mark Zandi to be the next guy nominated and he fully supports principal mods.

60-day delinquencies dropped to 4.56% according to Transunion, which is the fastest drop since they started keeping records in 1992. This decrease was higher than expected.

Help! (Since We Don’t Have a MR Until Tomorrow)

I’m in the midst of forming an LLC and need a catchy name.  The focus of my business is scientific technical writing–papers and grants and such in the life sciences arena.

You guys are a clever bunch–what springs to mind?  Thanks in advance!

Morning Non-Report Open Thread 05/07/13

Brent’s away. Nothing else to say.

Morning Report – CBO assumes a can opener 05/03/13

Vital Statistics:

  Last Change Percent
S&P Futures  1603.4 11.1 0.70%
Eurostoxx Index 2736.0 17.1 0.63%
Oil (WTI) 95.21 1.2 1.30%
LIBOR 0.275 0.002 0.73%
US Dollar Index (DXY) 82.43 0.204 0.25%
10 Year Govt Bond Yield 1.70% 0.07%  
Current Coupon Ginnie Mae TBA 106 -0.5  
Current Coupon Fannie Mae TBA 104.2 -0.3  
RPX Composite Real Estate Index 193.8 0.5  
BankRate 30 Year Fixed Rate Mortgage 3.42    

Markets are higher this morning after a better-than-expected jobs report. Bonds and MBS got whacked on the number.

Payrolls increased by 165,000 in April and the unemployment rate fell to 7.5%. March was revised upward from 88k to 138k. The labor force participation rate remained at 63.3%, the lowest since the 70s. Retail and business services added jobs, while construction was surprisingly flat. The average workweek fell, while average hourly earnings ticked up by 4 cents. 

The CBO has come out with a study saying that principal mods on Fannie and Freddie mortgages could save the taxpayer money by reducing delinquency and foreclosure costs and increasing economic growth. As far as the moral hazard issue – they dismiss the costs of moral hazard as “relatively low,” provided the government requires sufficient evidence of financial hardship. The study basically assumes that the government will thread the needle with drafting rules to prevent strategic defaults. The study reminds me of the old joke where an engineer and an economist are stranded on a desert island with an unopened can of soup. The engineer proposes to use a rock to open the can. The economist says “assume a can opener.” 

Lloyd Blankfein sees the current environment as a parallel of 1994. Borrowers had become so used to low interest rates that they weren’t ready when the Fed started hiking rates. Old timers will remember that was when Orange County blew up as mortgage backed securities got clocked. 


Morning Report – More Mel 05/02/13

Vital Statistics:

Last Change Percent
S&P Futures 1582.8 5.5 0.35%
Eurostoxx Index 2729.8 18.1 0.67%
Oil (WTI) 91.37 0.3 0.37%
LIBOR 0.273 0.000 0.00%
US Dollar Index (DXY) 81.75 0.263 0.32%
10 Year Govt Bond Yield 1.64% 0.01%
Current Coupon Ginnie Mae TBA 106.4 -0.1
Current Coupon Fannie Mae TBA 104.6 -0.1
RPX Composite Real Estate Index 192.8 0.3
BankRate 30 Year Fixed Rate Mortgage 3.4

Markets are stronger this morning after the ECB cut rates and initial jobless claims came in lower than expected. Productivity increased as well. Bonds and MBS are flat.

Yesterday’s FOMC statement turned out to be a “steady as she goes” statement. They mention that they are ready to increase or decrease asset purchases in response to changing economic conditions. ZIRP (meaning rock bottom interest rates) will continue as long as unemployment is above 6.5% and inflation remains at 2.5% or lower.

People are still trying to understand the implications of Mel Watt as Chairman of the FHFA. The biggest one is that Mel Watt was not nominated to preside over the dissolution of the government’s role in housing finance. Fannie and Fred will survive in some fashion. The elephant in the room is principal mods for people with underwater conforming mortgages. That will undoubtedly come up in the confirmation hearings. In his announcement, obama continued to press the left-wing narrative that “reckless lending” caused the financial crisis while studiously ignoring the fact that we had a housing bubble that was caused (or at a minimum enabled) by activist government policies and extremely loose monetary policy. I do think it is ironic that he talks about reckless lending when the government bears 50% of the credit risk of the entire US mortgage market. While people have hoped that the government will extricate itself from the mortgage market, this appointment suggests otherwise.

Challenger and Gray job cuts fell to 28,121 in April, a drop of 6% year-over-year. This is the lowest level since December 2012. Despite the sturm and drang over the sequester, the massive expected layoffs have yet to appear. Aerospace and defense did announce 1,928 job cuts that were related to the sequester. This is a far cry from the 900,000 jobs that were forecast by some studies.

Morning Report – New FHFA Chairman 05/01/13

Vital Statistics:

  Last Change Percent
S&P Futures  1591.2 -1.0 -0.06%
Eurostoxx Index 2712.0 0.0 0.00%
Oil (WTI) 91.87 -1.6 -1.70%
LIBOR 0.273 0.000 0.00%
US Dollar Index (DXY) 81.38 -0.367 -0.45%
10 Year Govt Bond Yield 1.65% -0.02%  
Current Coupon Ginnie Mae TBA 106.5 0.0  
Current Coupon Fannie Mae TBA 104.7 0.1  
RPX Composite Real Estate Index 192.5 0.4  
BankRate 30 Year Fixed Rate Mortgage 3.43    

Markets are slightly weaker ahead of the FOMC announcement later today. MBA mortgage applications increased 1.8% last week. The Markit Flash Manufacturing Purchasing Managers Index came in at 52.1, indicating that business conditions for manufacturers are more or less in line with historical trends. Bonds and MBS are up.

The ADP employment change (which is a forecast for Friday’s jobs report) came in lower than expected at 119,000. March was revised downward as well. Lately the ADP employment change has not been all that great or a predictor of the official jobs report, but we’ll see. 

The FOMC’s rate decision is expected to be released at 2:00 pm EST. Nobody expects any change in interest rates – the big question will be regarding asset purchases or QE. Late last year, there appeared to be a consensus that QE would end sometime this year. Subsequent comments from Federal Reserve governors however seemed to contradict that view. Now, we have some that have mentioned the possibility of additional measures. If anything that probably points to a “steady as she goes” type of statement, but we’ll see. 

Looks like Ed DeMarco is out at FHFA and Mel Watt is in. This probably means principal mods for conforming mortgages are on the way. Interestingly, Watt represented the Charlotte district, the same district as Bank of America. Principal mods are not a slam dunk however – the biggest MBS holders are pension funds and they are struggling to meet their obligations in this low interest rate environment. Watt’s confirmation will not be a slam dunk by any means. 

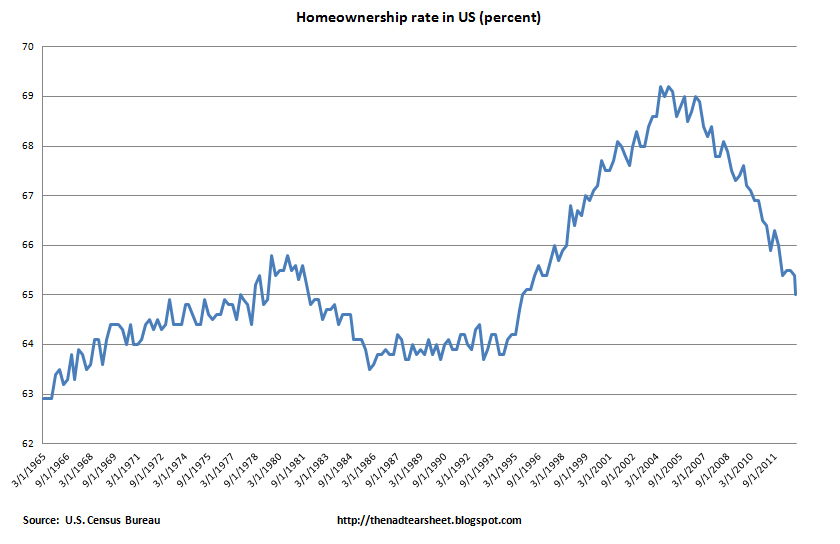
The homeownership rate declined to 65% in Q1, the lowest level since 1995. This speaks to the absolute dearth of household formation numbers in the last 5 years. While the number has dropped significantly from its peak in 2005, it is still more or less at historical averages. 

Chart:  Homeownership rate


Morning Report – Wanna lend some money to Apple? 04/30/13

Vital Statistics:

  Last Change Percent
S&P Futures  1587.3 -0.9 -0.06%
Eurostoxx Index 2720.1 2.7 0.10%
Oil (WTI) 93.73 -0.8 -0.81%
LIBOR 0.273 -0.001 -0.36%
US Dollar Index (DXY) 82.16 0.015 0.02%
10 Year Govt Bond Yield 1.65% -0.02%  
Current Coupon Ginnie Mae TBA 106.4 0.0  
Current Coupon Fannie Mae TBA 104.7 0.1  
RPX Composite Real Estate Index 192.1 1.1  
BankRate 30 Year Fixed Rate Mortgage 3.43    

Markets are lower this morning on no real news. The Employment Cost Index increased .3% in the first quarter and Q412 was revised down. Wages and salaries increased .5% while benefit costs dropped .1%. No inflationary pressures in the labor market. Today starts the two day FOMC meeting. Bonds and MBS are up slightly.

The S&P / Corelogic / Case-Schiller index of home values came in at + 9.32% year over year and + 1.24% month-over-month. This was the biggest increase since May 2006. Of course the real estate market is pretty bifurcated, with annual growth in the high teens out West and mid-to-high single digit growth elsewhere. They note that housing is now becoming a driver of GDP growth, although the mix still is skewed towards apartments and not single family residences.

Chart:  Case-Schiller indices

Apple is doing a massive bond issue – 6 different issues, including a 30 year bond. The proceeds will be used to fund dividends and buybacks and will help Apple avoid repatriation taxes on the over $100 billion in funds it holds overseas. The 30 year bond is supposedly going to be priced at a 115 basis point spread to Treasuries. That would be around 4%. The 5 year paper will be issued at 1.2%. Those are positively Japanese yields. Grandpa, tell me again about the days when companies would issue debt with yields lower than their dividend yield.


PIMCO’s Mohammed El-Arian thinks that the tone of the FOMC meeting will shift from “when do we end QE?” to maintaining it and possibly increasing stimulus. That would certainly be MBS bullish, which could start another refi wave, although prepay burnout has got to be pretty big at this point. He does note the risks of the record amount of stimulus: “The benefits of the Fed come with costs and risks. What I worry about is when you run a system at artificial price levels, you start creating damage, resources are misallocated, too much risk is taken.”  Exhibit (A):  Apple is borrowing money for 30 years at 4% to fund a stock buyback. 

Morning Report – Personal Spending up .2% 04/29/13

Vital Statistics:

  Last Change Percent
S&P Futures  1581.5 5.0 0.32%
Eurostoxx Index 2697.4 13.9 0.52%
Oil (WTI) 93.36 0.4 0.39%
LIBOR 0.274 -0.002 -0.54%
US Dollar Index (DXY) 82.12 -0.387 -0.47%
10 Year Govt Bond Yield 1.65% -0.01%  
Current Coupon Ginnie Mae TBA 106.3 0.1  
Current Coupon Fannie Mae TBA 104.6 0.1  
RPX Composite Real Estate Index 191 0.5  
BankRate 30 Year Fixed Rate Mortgage 3.43    

Markets are higher this morning after better-than-expected consumer spending data. Personal Income data was lower than expected. Bonds and MBS are up small

Personal Spending was projected to be flat, but actually rose .2%. The Bureau of Economic Analysis is claiming that it was primarily due to weather – a cooler than normal spring brought higher utility spending. Personal Income was forecast to rise .4%, and ended up at .2%. The PCE deflator showed inflation remains subdued.

Pending Home Sales increased 1.5% in March, according to the National Association of Realtors. Economists had forecast a 1% increase. Pending home sales are up 5.8% year-over-year.

Lender Processing Services reported that home prices increased 1% in February and rose 7.3% year-over-year. The West is experiencing the biggest gains, while the Northeast and Mid Atlantic continue to languish. This has been borne out by the earnings reports of the homebuilders as well – the ones primarily focused on California have knocked the cover off the ball, while those with an East-Coast / Midwest focus have reported gains, but nowhere near what the West Coast builders are reporting.

Lots of data this week, but the big driver will be the FOMC meeting. We will get the rate announcement on Wed. Investors will be looking for information concerning the end of QE. We will get the jobs report on Friday, which will have the biggest potential to move interest rates.

Lots of homebuilders reported earnings last week – pretty much everyone except NVR beat estimates. Anyone with exposure to the West Coast did well and backlog is up nicely at all of the builders. We will hear from Standard Pacific and Beazer Homes this week. The Homebuilder ETF (XHB) is on a tear and sitting right at resistance.

 U.S. News and World Report has a good piece on the state of the first time homebuyer.

An Aaron Sorkin Liberal Fantasy

Obama’s speech at the White House Correspondents’ Dinner:

Lots of really great one liners in there. Here is the full text for the YouTube impaired. He gets great writers for this event. The one item that seems to have gotten some news buzz was Antonio Scalia sitting at the Fox News table. Once you buy into the incestuous relationship between the press and the government this is a minor complaint.

Morning Report – disappointing GDP report 04/26/13

Vital Statistics:

  Last Change Percent
S&P Futures  1575.8 -5.9 -0.37%
Eurostoxx Index 2684.1 -20.3 -0.75%
Oil (WTI) 93.23 -0.4 -0.44%
LIBOR 0.276 0.000 0.00%
US Dollar Index (DXY) 82.61 -0.132 -0.16%
10 Year Govt Bond Yield 1.68% -0.03%  
Current Coupon Ginnie Mae TBA 106 0.0  
Current Coupon Fannie Mae TBA 104.5 0.2  
RPX Composite Real Estate Index 191 0.5  
BankRate 30 Year Fixed Rate Mortgage 3.47    

Markets are slightly weaker after Q1 GDP came in weaker than expected. D.R. Horton reported better than expected earnings. Bonds and MBS are stronger


Q1 GDP came in at + 2.5%. lower than the 3% estimate. This is the advance estimate – Q1 GDP will be revised twice in the next two months. Consumer spending increased at 3.2% and the savings rate declined. The back-to-back drop in defense spending was the biggest since 1954. Real disposable incomes fell 5.3% in Q1 on increased taxes. C = 3.2%, I = 3%, G = -4.1%. 

The Senate voted to end sequestration-related furloughs for air traffic controllers and the measure will be sent to the House today. President Obama has said he will consider whatever is sent to him. 

CoreLogic has acquired Case-Schiller.

The CFPB has proposed amendments to the QM rule.  The proposals are here.