Morning Report – the week ahead 2/17/15

Stocks are lower this morning as Greek talks break down. Bonds and MBS are up small.

The Empire Manufacturing Index fell in Feb and came in slightly light. There is almost certainly some weather-related noise in that report.

The NAHB Housing Market Index fell to 55 in February from 57 in January. The index increased in the Northeast and fell in the Midwest. The South and West were more or less unchanged.

We have a lot of data this week with housing starts tomorrow, industrial production / capacity utilization, and finally the FOMC minutes. The minutes should be the big event for the week. The focus will be on handicapping a June rate hike.

Speaking of rate hikes, wage inflation continues to be the missing piece of the puzzle for the economy. That said, Big Labor is waking up, with refinery strikes and a longshoreman’s strike on the West Coast. Strike activity is still well below where it was in the 70s and 80s, but it could be the start of wage inflation.

One in three FHA borrowers could save money by refinancing today. Of course many will find the savings to small to make it worthwhile, but the drop in annual MIP is a big deal. Certainly MBS investors think so as Ginnie Mae TBAs continue to underperform Fannie Mae TBAs.

Finally, I appeared on Capital Markets Today and did a deep dive into the economy and housing. You can listen to the podcast here.

Preliminary Injunction Against DAPA – USDC SD TX

—
Some excerpts from the 123 bloody paged opinion:
—
This case examines complex issues relating to immigration which necessarily involve questions of federalism, separation of powers, and the ability and advisability, if any, of the Judiciary to hear and resolve such a dispute.
—
Regardless of the fact that the Executive Branch has made public statements to the contrary, there are no executive orders or other presidential proclamations or communique that exist regarding DAPA. The DAPA Memorandum issued by Secretary Johnson is the focus in this suit.
—
Secretary Johnson supported the implementation of DAPA with two main justifications.  …limited resources …humanitarian concerns.
—
As Defendants concede, a direct and genuine injury to a State?s own proprietary interests may give rise to standing. Doc. No. 38 at 23; see also, e. g, Clinton v. City of N. Y., 524 US. 417, 430-31 (1998) (negative effects on the borrowing power, financial strength, and fiscal planning of a government entity are sufficient injuries to establish standing); Sch. Dist. of City of Pontiac, 584 F.3d 253, 261 (6th Cir. 2009) (school districts had standing based on their allegation that they must spend state and local funds to comply with federal law). Defendants in this case argue, however, that the projected costs to Plaintiffs drivers license programs are self-inflicted because the DHS Directive does not directly require states to provide any state benefits to deferred action recipients, and because states can adjust their benefit programs to avoid incurring these costs. Doc. No. 38 at 21-22. This assertion,
however, evaluates the DHS Directive in a vacuum. Further, this claim is, at best, disingenuous.  Although the terms of DAPA do not compel states to provide any benefits to deferred action recipients, it is clear that the DHS Directive will nonetheless affect state programs. Specifically,
in the wake of the Ninth Circuit’s decision in Arizona Dream Act Coalition v. Brewer, it is apparent that the federal government will compel compliance by all states regarding the issuance of drivers licenses to recipients of deferred action. 757 F.3d 1053 (9th Cir. 2014).
—
Also, it is not a defense to the Plaintiffs’ assertion of standing to argue that it is not the DAPA program causing the harm, but rather the Justice Department’s enforcement of the program.
—
…standing under Massachusetts v. E.P.A….
—
If the Court were to grant the requested relief, it would not change the presence of these individuals in this country, nor would it relieve the States of their obligations to pay for any associated costs. Thus, an injunction against DAPA would not redress the damages described above.
—
Three important factors separate those cases from the present one…Because of this announced policy of non-enforcement, the Plaintiffs’ claims are completely different from those based on mere ineffective enforcement. This
is abdication by any meaningful measure…Conversely, in the present case, Texas has shown that it will suffer millions of dollars in direct damages caused by the implementation of DAPA…Finally, … the above-cited cases pre-date the REAL ID Act of 2005.
—
To establish the second element necessary for abdication standing, the States assert that the Government has abandoned its duty to enforce the law. This assertion cannot be disputed…standing under a theory of abdication requires only that the Government declines to enforce the law. Here, it has.
—
… it is clear that Plaintiffs satisfy the standing requirements as prescribed by the APA.
—
Having concluded that at least one Plaintiff, the State of Texas, has standing, the Court now addresses the merits of the States’ claims regarding the DAPA program.
—
Absent abdication, decisions to not take enforcement action are rarely reviewable under the APA.
—
As there is no statute that authorizes the DHS to implement the DAPA program, there is certainly no statute that precludes judicial review under Section 701(a).
—
the Court finds that, in this case, to the extent that the DAPA Directive can be characterized as “non~enforcement”, it is actually affirmative action rather than inaction.  …the very statutes under which Defendants claim discretionary authority actually compel the opposite result. In particular, detailed and mandatory commands within the INA provisions applicable to Defendants’ action in this case circumscribe discretion.
—
After 123 pages of discussing “standing” under 3 theories and reviewability under APA, the trial court granted the Preliminary Injunction.
I do wonder about the discretion – abdication distinction.  I also wonder if a “non-enforcement” directive so sweeping and so rigidly constructed can avoid the strictures of APA.  I initially thought that DAPA and DACA before it were within the limits of executive authority and I still do as a constitutional matter, in a vacuum,  but as an Administrative Procedure Act violation, I can see this as an overreach based on the facts as recited in the Opinion.  Scott has pointed to the theory of abdication without calling it that, and I had not realized how iron bound the denial of individual discretion in DAPA was until I read all the footnotes in this case.  JNC – if you wade through the 123 pages I think you will be struck by the court’s stream of consciousness attempt to address the matter[s].

Morning Report – Bill Ackman’s Fannie Mae trade 2/13/15

Happy Friday the 13th.

Markets are higher this morning on optimism of a deal in Greece and encouraging economic data out of Germany. The Greek 10 year yield is down almost 100 basis points this morning and is approaching 9%. The market has a risk-on feel with stocks up and bonds / MBS down.

Import prices fell 2.8% MOM and 8% YOY. Consumer sentiment fell from 98.1 to 93.7.

Bloomberg has a good piece on Mel Watt and the issues surrounding principal mods for Fan and Fred loans. The biggest question remains: how can you help underwater homeowners without triggering a wave of strategic defaults? 85% – 90% of people whose mortgage is underwater are current on their payments. The last thing you want to do is encourage them to stop paying in order to get a principal mod. Luckily, time has been doing the heavy lifting here, as the number of homes with negative equity has fallen from 31% in 2012 to just about 17% today. Second, many of those homes are not Fan and Fred loans in the first place, and FHFA is only looking at cutting principal on Fan and Fred loans that it owns. The FHFA Home Price Index, which tracks the prices of homes with a conforming mortgage is within 5% of the peak.

Bob Shiller warns of a bond bubble. He is probably right, although it could last some time. Interest rate cycles are long: the current cycle began in 1981 or so. Note that in the 1950s, the bond market crashed and the generation that lost their shirts in the stock market crash of 1929 ended up blowing up in levered flattening trades. Persistently low interest rates can wreak all sorts of havoc, especially with pension funds and insurance companies. They have a return bogey they must meet, and the actuarial tables couldn’t care less that interest rates are zero. Note that Dr. Cowbell is copacetic with all of this. Note that the 4 most dangerous words in investing are: This Time Is Different.

Bill Ackman sees the common stock of Fannie Mae and Freddie Mac as “the best trade in capital markets” He is betting that Congress will eventually stop taking all of Fannie’s profits and allow them to recapitalize in private markets. The thing is, this is a litigation lottery ticket. It is either worth a lot, or worth nothing. If it actually had access to its profits – it doesn’t – all p/l goes to Treasury – it would have a P/E of 1. FWIW, the Administration is bound and determined to see that Fannie Mae common shareholders do not see a dime. But administrations could change, and Congress may decide that housing reform is simply too tough and we go back to the old F&F.

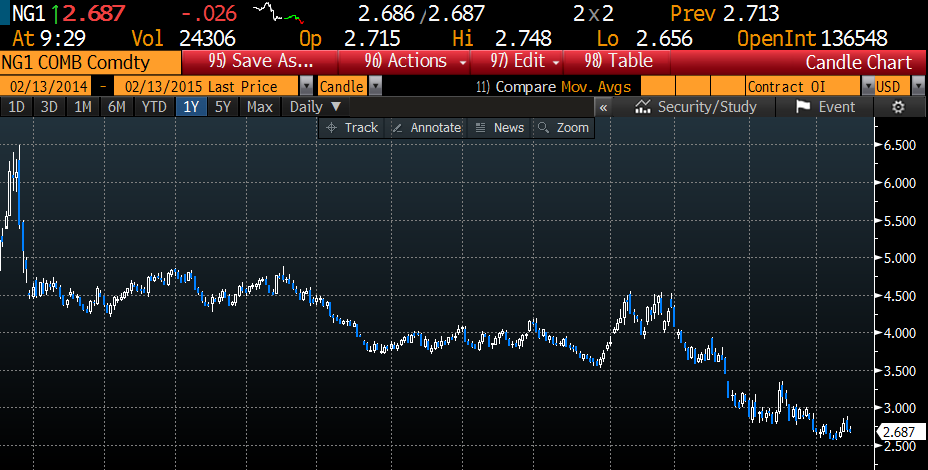
How bad are things in the energy patch? We have another arctic blast hitting the Eastern part of the country and natural gas cannot get out of its own way.  Kind of amazing, really.

Morning Report – Bad news in the energy patch could be good news for housing… 2/12/15

Markets are higher this morning on news of a cease-fire in Ukraine. Bonds and MBS are up.

Greek bonds are rallying with bonds globally. Unusual, as a rally in Greek debt has been triggering the risk-on trade lately.

Retail Sales disappointed in January. The headline number fell .8%, however falling gas prices were a big contributor (gas is measured in dollars, not gallons). However, the control group, which strips out volatile segments like autos, gas, and building materials only rose .1%, versus Street expectations of .4%. The strength appears to be in autos and food service. Bad weather in the Northeast may have played a role in the number, however.

Business Inventories rose .1% and the Bloomberg Consumer Comfort Index fell to 44.3.

Initial Jobless Claims rose to 304k last week. This is going to be a number to watch – falling energy prices are triggering layoffs in the energy patch. Interestingly, part of the reason why labor has been so tight in construction was due to workers moving from the construction sector to the energy sector after the housing bust. As energy prices fall and construction begins to ramp up, this could be good news for the housing sector and especially the homebuilders. The builders have been frustrated by an inability to find skilled labor, and a reversal of the migration from construction to the energy sector should help them.

Julian Castro appeared before the House Financial Services Committee yesterday. His prepared remarks are here. He was there to defend the cut in mortgage insurance and to rah-rah everything the Administration has done to get housing (and the economy) moving. It was basically a defense of an activist government role in the housing market.

Beyond SSM – Far-fetched and vacuous or tip of the iceberg?

Pretty interesting thing I just stumbled across (via The Federalist).

In our past debates about SSM, pointing out the obvious, logical implications of arguments for re-defining marriage to include same-sex couples was variously dismissed as “false equivalencies”, “vacuous”, “far-fetched”, and as possibilities that exist only in the “slippery slope” imaginations of those who object to SSM (to wit, “I understand that no defender of SSM would have raised the idea if it had not been first made an attack point by opponents of SSM”).

It turns out, however, that a document titled Beyond Same-Sex Marriage was produced way back in the dark ages of 2006 before it was politically expedient to support SSM, in which all of the fanciful, vacuous, far-fetched, slippery slope implications of SSM we fully laid out by the burgeoning SSM movement…as long term goals. A taste:

We, the undersigned – lesbian, gay, bisexual, and transgender (LGBT) and allied activists, scholars, educators, writers, artists, lawyers, journalists, and community organizers – seek to offer friends and colleagues everywhere a new vision for securing governmental and private institutional recognition of diverse kinds of partnerships, households, kinship relationships and families. In so doing, we hope to move beyond the narrow confines of marriage politics as they exist in the United States today.

…The struggle for same-sex marriage rights is only one part of a larger effort to strengthen the security and stability of diverse households and families. LGBT communities have ample reason to recognize that families and relationships know no borders and will never slot narrowly into a single existing template.

…Marriage is not the only worthy form of family or relationship, and it should not be legally and economically privileged above all others. While we honor those for whom marriage is the most meaningful personal ­– for some, also a deeply spiritual – choice, we believe that many other kinds of kinship relationship, households, and families must also be accorded recognition.

Among these relationships that should be granted the legal and cultural equivalence of marriage are:

Committed, loving households in which there is more than one conjugal partner

…and:

Close friends and siblings who live together in long-term, committed, non-conjugal relationships, serving as each other’s primary support and caregivers

…and:

Queer couples who decide to jointly create and raise a child with another queer person or couple, in two households

Perhaps what we who oppose court imposed SSM were saying all those many months ago was not quite so vacuous and far-fetched, after all.

BTW, if you want to peruse the hundreds of signatories to this document, representing ostensibly respectable institutions like Harvard, Georgetown, Columbia, University of Texas Austin, NYU, you can find them here.

Morning Report – Good early indications on the Spring Selling Season2/11/15

Stocks are lower worldwide as Greece and Germany continue to posture over future Greek bailouts. The Greek 10 year bond yield is up 33 basis points to 10.58%. Global bonds are up small, and MBS are flat.

Mortgage Applications fell 9% last week as rates backed up 32 basis points. Purchases were down 6.5% while refis were down 10.3%.

Hedge funds that bought distressed mortgage debt in 2008 and 2009 are unwinding their positions as spreads have tightened and real estate prices have risen. Probably next on the agenda is the unwind of the REO-to-Rental trade which has simply not lived up to the hype.

Homebuilder KB Home is doing a $250 million bond issue today. Separately, they announced new orders were up 25% so far this year. Key quote from CEO Jeffrey Metzger: “Based on our expanding community count and the strength of our recent net order results, we are optimistic about the spring selling season. We believe the momentum of these favorable trends, in combination with our solid backlog, support a positive revenue outlook for the remainder of the year, particularly in the third and fourth quarters.”

Lewie Ranieri’s Shellpoint Partners rolled out their non-QM credit repair product in October, and they hope to do their first securitization of these loans this year. They believe the agencies will demand 15% credit enhancement for AAA tranches with high quality non-QM loans, and credit enhancement of 34%-40% for the tougher stuff: 620 FICO, 50 DTI, 80 LTV loans. Shellpoint lends through its New Penn unit. Sounds like we are getting closer to non-QM securitization.

Morning Report – Consumers are becoming more constructive on housing 2/10/15

Markets are higher this morning as the Greek government offered a compromise on the bailout. Bonds and MBS are down worldwide, with the US 10 year yield flirting with a 2 handle.

Greek 10 year bond yields are down 68 basis points as the Greek government and international creditors hammer out a deal.  This is fueling a risk-on trade as stocks rise / bonds fall.

The NFIB Small Business Optimism Survey fell to 97.9 from 100.4 in January. Expectations were for a  101. The IBD / TIPP Economic Optimism Index fell in February from 51.1 to 47.5. Job Openings topped 5 million according to the JOLTS survey.

Consumers are feeling a little better about the housing market, according to the Fannie Mae National Housing Survey. Expectations of home price appreciation rose to 2.5% from 2.3% a month ago, and almost half of respondents thing prices will go up in the next year. Americans are still negative on the economy, but less so, with 49% believing we are on the wrong track and 44% believing we are on the right track.

Foreclosure Completions fell to 39,000 in December, a 4.9% drop month-over-month and a 13.7% drop year-over-year, according to CoreLogic. Current foreclosure inventory is 552k homes, a decrease of 34.3% from a year ago. New Jersey and New York continue to lead the US with the highest percentage of foreclosures.

Morning Report – Further look at the jobs report 2/9/15

Markets are lower this morning on European weakness. Bonds and MBS are up.

This week is going to be relatively data-light, with retail sales being the highlight.

Friday’s jobs report was undeniably strong, but I would keep in mind one thing in the back of my mind: We are in a sort of a sweet spot, where lower energy prices are helping things along, but the big layoffs in the energy sector have yet to materialize. If energy prices stay here, producers will cut production and staff. Also, the Fed will start hiking rates in June and then all bets are off.

Note that last week, Ginnie Mae TBAs underperformed Fannie Mae TBAs are rates shot up. I suspect this is still related to the new MI changes. The bottom line is that conforming pricing is getting more attractive relative to government pricing.

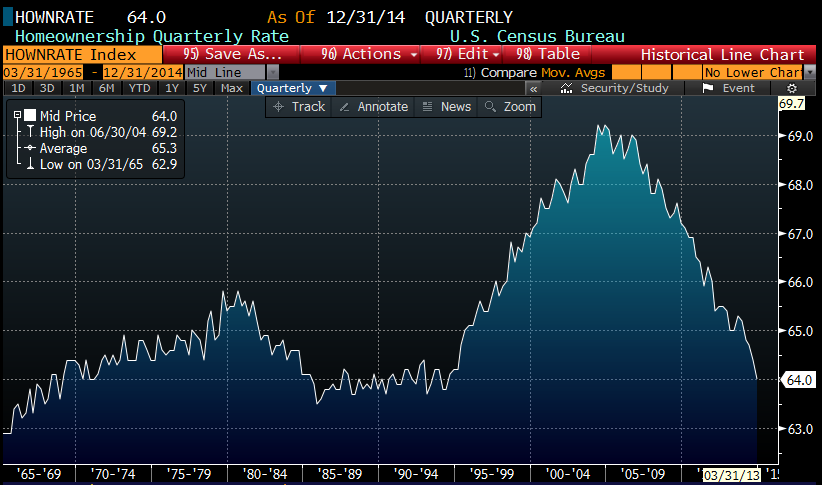
The NY Times comments on the social engineering aspects of the housing market. Note that one of Bill Clinton’s first acts was to prod Fan and Fred into increasing the homeownership percentage. That percentage is now back to 1994 levels more or less. Mel Watt is trying to push it up again, but really has limited tools given that he has to explicitly protect taxpayers and there is still not much of a private mortgage market.

Never one to ignore technical progress, NAR is urging Congress to allow people to use drones to market homes…

Morning Report – Strong jobs data 2/6/15

Markets are higher this morning after a very strong jobs report. Bonds and MBS are down.
Jobs report data dump:
  • Nonfarm payrolls + 257k
  • Two month payroll revision + 147k
  • Unemployment rate 5.7% (increase of .1%)
  • Average Hourly earnings +.5% MOM
  • Average Hourly earnings + 2.2% YOY
  • Average Weekly Hours 34.6
  • Labor Force Participation rate 62.9% (increase of .2%)
  • Underemployment rate 11.3% (increase of .1%)
Overall, a very strong report, especially with the two month revision and the increase in wages. Bonds sold off hard on the number, although Euro bonds are off as well, so the global backdrop is “risk-on.” BLS did the annual revision to the data series this month, so there may be some technical factors in the data. This report certainly adds weight to the hawks who want to see rates increase and worry that the Fed is behind the curve.
Notwithstanding the average hourly earnings increase, I still don’t see much in the way of wage inflation. I suspect some of the increase is due to people who have variable compensation – people on commissions, people who get production bonuses, etc. When the economy improves, they do better, however that increase can be temporary. Are “base wages” increasing? It certainly doesn’t fell like it is yet.
Final job report observation: the feared job losses in the energy patch have yet to materialize.
Grandpa, tell me again about what it was like when interest rates were set by people in colorful jackets shouting at each other in a big room… Goodbye pit traders..

Morning Report – Principal Mods on the horizon? Maybe 2/5/15

Markets are higher this morning as Greece and Germany spar over bailouts for the Greek banking system. Bonds and MBS are down.

In economic data, initial jobless claims rose to 278k, higher than expected, but still good. Productivity fell 1.8% while unit labor costs rose 2.7%. Finally the trade deficit increased by $8 billion, dashing hopes for a big upward revision in Q4 GDP.

Uber-dove Boston Fed President Eric Rosengren says they Fed can remain “patient” in terms of raising interest rates, given the deflationary winds from overseas. Rosengren is a non-voting member. Janet Yellen in the Dec FOMC press conference characterized “patient” as “more than two FOMC meetings away). So, if the Fed intends to move at the June meeting, that word will probably be gone in the March statement. Listen to the language of the different Fed heads going forward – if it starts disappearing from prepared statements, etc that fact is telling you something..

Grexit (the name for Greece leaving the Euro) will get a lot of discussion in the press, but it probably won’t happen. Voters in Germany and Greece both support Greece staying in the Euro. Exporters like Germany benefit from the drag Greece (and the rest of the PIIGS) put on the Euro. The issue is that Germany, Finland etc don’t trust the Greek government to make the necessary structural changes without the risk of being booted. In other words, much of what you will hear over the next few months will be posturing ahead of another bailout.

Mel Watt is considering principal mods for underwater borrowers with loans held by FHFA. However, any plan will be “narrow” and will have to be done without incurring costs to the taxpayer. Interestingly, by cutting MI premium and G-fees, he is effectively increasing costs to taxpayers by increasing the chance they have to bail out the fund. Given that we are within 5% of peak levels, according to the FHFA Home Price Index, Mel can probably make this problem disappear by running out the clock. Note that Mel says mass principal forgiveness would cost the government billions. The Congressional Budget Office disagrees that a mass principal forgiveness program would cost anything. Looks like not even the Administration buys that argument…

Standard and Poors agreed to pay $1.5 billion in fines, without admitting wrongdoing. They have been forced to stop saying the suit was in retaliation for their downgrade of US Treasuries. Moody’s – you’re next. Hopefully Mark Zandi said enough nice things about the Administration that you’ll get off easier…