Morning Report – The Secular Bear 01/29/13

Vital Statistics:

  Last Change Percent
S&P Futures  1492.9 -4.2 -0.28%
Eurostoxx Index 2736.0 -8.5 -0.31%
Oil (WTI) 96.55 0.1 0.11%
LIBOR 0.301 -0.001 -0.33%
US Dollar Index (DXY) 79.8 0.023 0.03%
10 Year Govt Bond Yield 1.96% -0.01%  
RPX Composite Real Estate Index 193.4 0.8  

Stock index futures are weaker as the Fed kicks off its January FOMC meeting. The markets will be parsing the press release looking for clues regarding the end of QE, specifically the timing and the economic variables that influence the decision. Today is a very heavy earnings day, with Danaher, Ford, EMC, International Paper, and Pfizer reporting. Bonds and MBS are up a tick or two.

The S&P Case-Schiller index of home values rose 5.5% YOY and .6% MOM in the month of November.   The hardest hit areas (Phoenix, Detroit, Las Vegas) showed the biggest YOY increases (Phoenix was up 23%!), while the New York declined 1.2% 

DR Horton reported a 39% increase in revenues and a 26% jump in homes closed from a year ago.  Orders were up 39% and backlog was up 62%. Like the other homebuilders, DHI is reporting general strength in their housing markets.  There was a shift towards larger houses as well, as the dollar increase in the value of homes built increased 60%, while the number of units increased 39%.  They are looking forward to the spring selling season with optimism.  The stock is up about 4% pre-open. 

Is the “risk on” trade we have been waiting for since 2007 finally on?  Trim Tabs is reporting that last month was a record month for inflows for stock mutual funds and ETFs – the last time we had inflows of this magnitude was the winter of 2000, right as the tech bubble was bursting.  Time to be cautious or time to break out the champagne?  Reason for optimism:  There are no, repeat no, signs of overheating in the economy.  If anything there is a tremendous amount of pent-up demand.  That is not recessionary, and should therefore be bullish for stocks.  Reason for pessimism:  Interest rates are going up. The great secular bull market in bonds that began with Paul Volcker’s tightening in 1981 is ending. The end of QE will mean long-term rates will rise, and short-term rates will soon follow. Also, we are in a secular bear market for stocks, and those rare animals typically last a lot longer than 12 years. 

This secular bear market in stocks resembles the bear market of the 1970s. with stocks trading in a large range that oscillates over a period of years, while going nowhere.  To put the 1970s in perspective, the Dow Jones Industrial Average was at roughly the same place when I graduated from high school as it was when I was born.  

Chart:  Dow Jones Industrial Average 1965 – 1983: 

Compare to the S&P 500 since 2000: 
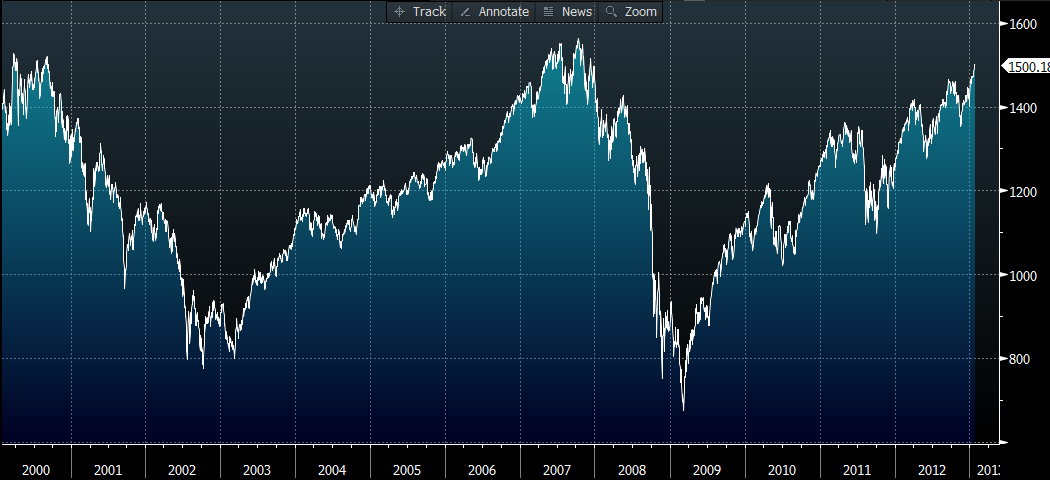
 

Similar oscillating pattern, with higher highs, and lower lows. If you believe in charts, they suggest a further run to eclipse the previous high and then a swoon lower. So, you might have another 8% – 10% left before the market heads back down again. 

Of course we have one other secular bear market to look at:  the granddaddy of them all:
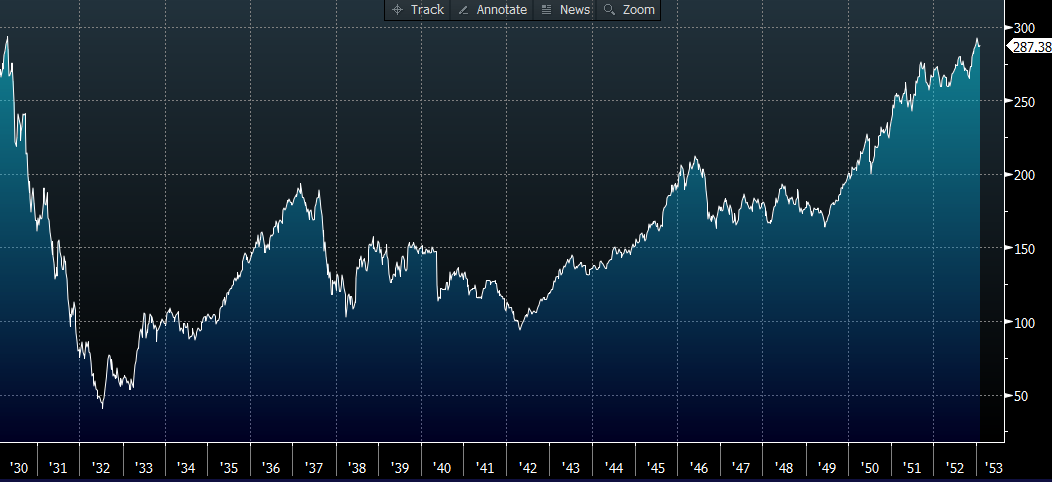
23 years of a secular bear – it took until 1953 to recover the losses from the 1929 crash.  Some stock market darlings – Radio Corporation of America (aka RCA) never regained its peak from the 1920s. The economic backdrop of deleveraging has a lot more in common with the Depression bear than the 1970s bear which was driven by commodity price shocks and inflation.

Of course as Wall Street loves to say, past performance is not indicative of future performance, and charts are just that – representations of history that may or may not be relevant. The market may not follow either pattern.  But, remember the great secular bull market in stocks from 1983 – 2000 was accompanied by a secular bull market in bonds that began at roughly the same time.  That will not be the case this time around. 

Morning Report – New Fannie Mae DIL program 01/28/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1497.4

1.7

0.11%

Eurostoxx Index

2747.9

3.7

0.13%

Oil (WTI)

96.17

0.3

0.30%

LIBOR

0.302

0.001

0.33%

US Dollar Index (DXY)

79.84

0.092

0.12%

10 Year Govt Bond Yield

1.96%

0.02%


RPX Composite Real Estate Index

192.6

0.0


Markets are slightly higher this morning after a strong earnings report from Caterpillar and strong durable goods numbers. Bonds continue their swoon, with the 10 year approaching 2%. Is the “risk on” trade we have been waiting for since 2008 finally at hand?  MBS are down as well.

Fannie Mae is offering deed-in-lieu options for underwater borrowers who are current on their mortgage and have experienced some sort of hardship like illness, job change, or other problems.  It effectively allows these homeowners to “toss the keys to the bank” and walk away from their underwater property with the underwater portion of their mortgage debt forgiven. The program does not address mortgages, so a second-lien holder could prevent a homeowner from walking away.

The Federal Appeals Court has rejected Obama’s recess appointments, specifically his appointments to the NLRB and the CFPB. Cordray’s appointment to head the CFPB was an interim appointment, and he will have to go through the process for his 5-year term.  Will it change anything for people in the industry?  Probably not.

Since we have kicked the debt ceiling can down the road for a few months, the next item is the sequestration – which is all of the automatic spending cuts that kick in.  Half will be in defense, and half will be in non-defense discretionary spending. Paul Ryan was on Meet the Press and said that he expects the sequestration cuts will happen.  Agencies are bracing for the cuts to happen as well.

Looks like the eminent domain idea is officially dead, at least in California.

Morning Report – Radar Logic Outlook 01/25/13

Vital Statistics:

  Last Change Percent
S&P Futures  1496.5 4.7 0.32%
Eurostoxx Index 2741.8 18.8 0.69%
Oil (WTI) 96.22 0.3 0.28%
LIBOR 0.301 0.000 0.00%
US Dollar Index (DXY) 79.73 -0.217 -0.27%
10 Year Govt Bond Yield 1.91% 0.07%  
RPX Composite Real Estate Index 192.5 0.4  

US stock index futures are higher this morning on the back of a sell-off in bond futures. The sell-off began around 4:00 am, and I don’t see any single economic story in Europe that would explain it. German confidence was higher than expected, and the Euro banks plan on paying off the ECB loans earlier than expected.  Could be a big asset allocation switch, but why do you do it at the opening of Europe?  Strange. The 10-year now yields 1.91%, and is flirting with resistance around the 1.91 – 1.92 level. MBS are weaker this morning as well. 

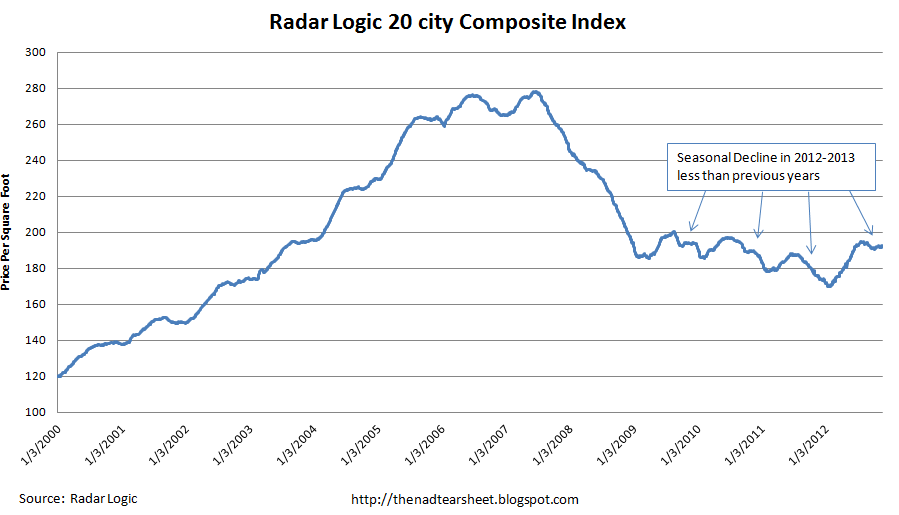
The theme of Radar Logic’s November 2012 monthly report is:  It is still too early to call a housing recovery.   Radar Logic has consistently been more bearish on the outlook for housing than Case-Schiller or the government.  In their view, the strength in 2012 was due more to easy comparables from a lousy 2011 than any true organic growth. The typical seasonal drop in prices this year has been much lower than in the past. In addition, the increase in house prices has been driven more by a drop in distressed sales than an increase in the value of individual properties. Finally, they note that housing demand has been driven primarily by institutional investors, who’s demand may be temporary.  

Chart:  Radar Logic 20 City Composite:

Another monetary milestone:  The Fed’s balance sheet breaks the $3 trillion barrier.

Its baaaack… The San Bernardino Eminent Domain debate returns with a public meeting.  The eminent domain route is fraught with legal roadblocks and will probably not work.  Yet Mortgage Resolution Partners is committed to covering the legal costs and would be willing to take the case to the Supreme Court. The payoff for them if it works is decent, but I don’t see how their limited partners are willing to accept this risk / reward.  

Is the “D” the new Phoenix?  Yes, house prices have gotten demolished, but the population of Detroit has been shrinking since the 1950s.  Completely opposite of the Southwest. I guess a $500 house is a $500 house and any investment becomes attractive if it gets cheap enough.

Will Jack Lew’s tenure at Citi cause problems for his nomination to Treasury Secretary?  Richard Cordray will undoubtedly have some opposition in the Senate.  I have not heard much in the way of opposition to Mary Jo White for SEC.

Carl Icahn has entered the Herbalife fray.  Let’s just say there is no love lost between Carl and Ackman.

Morning Report – Orders increase at KB Homes 01/24/13

Vital Statistics:

Last Change Percent
S&P Futures 1488.5 -1.8 -0.12%
Eurostoxx Index 2706.9 -1.4 -0.05%
Oil (WTI) 95.96 0.7 0.77%
LIBOR 0.301 -0.001 -0.17%
US Dollar Index (DXY) 80 0.083 0.10%
10 Year Govt Bond Yield 1.83% 0.01%
RPX Composite Real Estate Index 192.1 -0.1

Markets are lower after Apple stunk up the joint.  Initial Jobless Claims came in at 330k.  The Markit PMI came in at 56.1.  Bristol Myers and 3M beat expectations. Bonds and MBS are down small.

The IMF forecast world economic growth of 3.5% for 2013.  The US is forecast to grow 2%, with growth accelerating in 2H. The Euro area is expected to contract by .2%.

KB Homes reported that preliminary quarter-to-date net orders increased 54%.  Separately, they announced they are forming a home-loan company for its buyers with Nationstar. Concurrently, they are doing a $100MM secondary and a $200MM convertible bond issue priced at 1.375s up 50.

Obama is expected to name Mary Jo White as the new head of the SEC. A former prosecutor, she is expected to signal the importance of holding Wall Street accountable.

Bob Schiller is still cautious on housing.

The renovation boom continues.  As inventory remains small, many homeowners are choosing to upgrade current homes as opposed to buying new ones.  Are 203ks the next big thing?

Morning Report – FHFA House Price Index 01/23/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1487.3

-2.1

-0.14%

Eurostoxx Index

2711.0

-5.7

-0.21%

Oil (WTI)

96.78

0.1

0.10%

LIBOR

0.301

-0.001

-0.33%

US Dollar Index (DXY)

79.76

-0.117

-0.15%

10 Year Govt Bond Yield

1.83%

-0.02%


RPX Composite Real Estate Index

192.2

-0.6


Markets are slightly lower this morning in spite of good earnings reports out of IBM and Google.  After the close, we get Apple’s 4Q as well.  Mortgage Applications were up last week. Later on we will get the IMF world economic outlook.

The House will vote today to suspend enforcement of the debt limit through mid-May, in order to put pressure on the Democratically controlled Senate to pass a budget and to relieve the pressure on the debt ceiling crisis. Obama says he will go along with it. Which means the next subject will be the sequestration cuts.

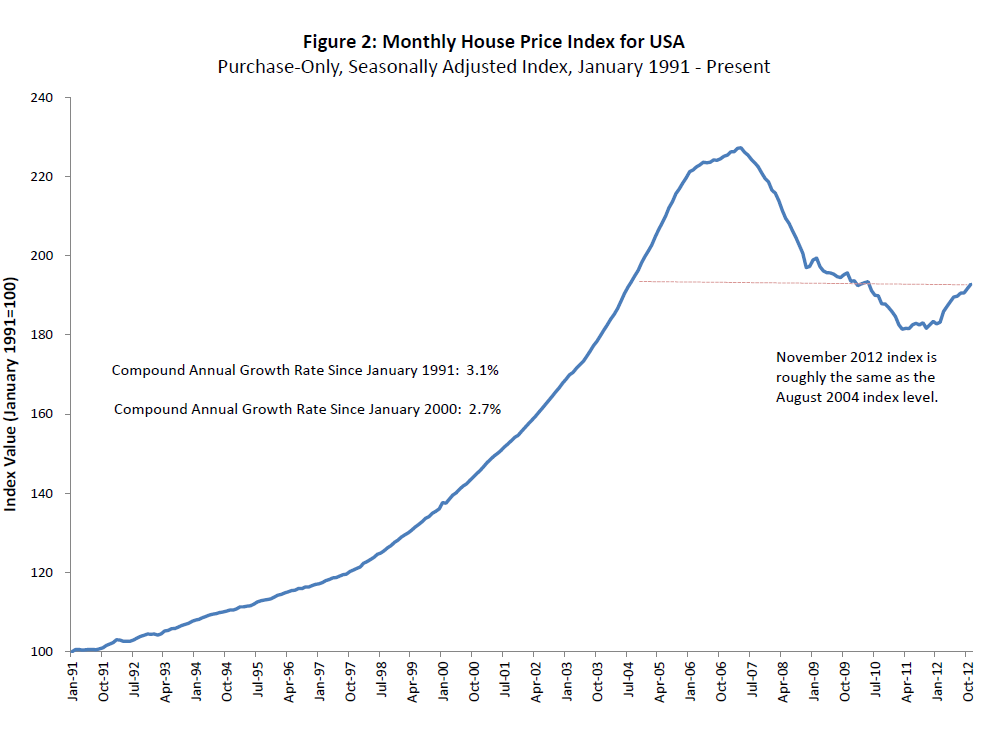
The FHFA House Price Index rose .6% in November.  On a YOY basis, prices are up 5.6%.  The FHFA index only looks at conforming mortgages, which is more stable than the broader indices.  Prices are back to August of 2004 levels.

 Is the roughly $1.7 trillion of foreign earnings stashed offshore by US companies something that is kept out of the US economy?  Turns out that a lot of it is in offshore accounts, invested in US dollar assets like Treasuries and MBS, which undermines the argument that all of this foreign cash could be circulated in the US economy if we changed the tax laws.  That said, this money is not available for expansion in the US or for distributions to shareholders.

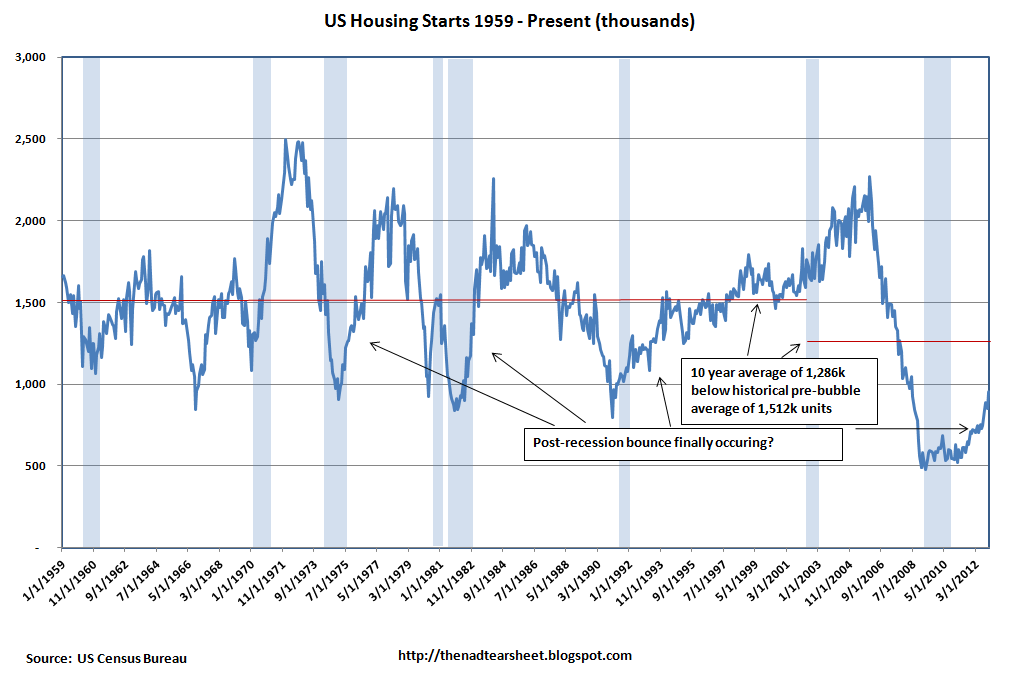
The NAHB expects the housing upturn that started last year to pick up momentum, in spite of headwinds coming out of tight mortgage lending and potential tax changes. Using 2000-2003 as a baseline, the single-family market was running at 44% of normal production.  The NAHB forecasts 949k total housing starts in 2013.  From 1959 through 2002, 1.5 million units a year was considered “normal”

Jamie Dimon had some words for regulators at Davos. Suffice it to say that bankers loved it, and the chattering classes / political classes did not. If obama’s inauguration speech was a full-throated defense of activist government, Dimon’s speech was a defense of the private sector.

Morning Report – S&P earnings 01/22/13

Vital Statistics:

  Last Change Percent
S&P Futures  1477.5 -1.4 -0.09%
Eurostoxx Index 2715.3 -11.3 -0.42%
Oil (WTI) 95.48 -0.1 -0.08%
LIBOR 0.302 0.000 0.00%
US Dollar Index (DXY) 79.92 -0.116 -0.14%
10 Year Govt Bond Yield 1.86% 0.02%  
RPX Composite Real Estate Index 192.8 1.0  

Markets are flattish on no real news.  Japan has announced a 2% inflation target, similar to what the Fed has been doing, in an attempt to weaken the yen.  The World Economic Forum meets in Davos this week. For once, there isn’t a major crisis to deal with.  We don’t have a lot of economic data this week, with the exception of leading economic indicators on the 24th.  Bonds are down half a point and MBS are down a tick or two.

We have decent earnings reports this morning from DuPont, Travelers, Johnny John, and Freeport.  This is one of the heaviest weeks for earnings reports, and erstwhile market darling Apple reports tomorrow after the close.

The WSJ is predicting that companies will increase share buy-backs this year as companies try and figure out what to do with excess cash. This will buoy the S&P 500 and mask the effect of flat earnings. Many strategists believe that US companies have pretty much wrung out all of the excess costs they can and any further earnings growth will have to come from revenue growth.  And if you can’t get revenue growth, how do you show increasing EPS?  You guessed it – buybacks. 

Is the financial system finally back on its feet?  We will see if Silver Lake is able to obtain financing for its planned $24 billion LBO of Dell. This is one of the side effects of the Fed’s QE efforts – in an era of rock-bottom interest rates, pension funds and insurance companies are starving for yield, which makes the splashy LBO possible again.

The Chicago Fed National Activity Index came in +.02 in December, down from +.27 in November. The 3 month moving average is still negative, indicating economic activity is below its historical trend. 

The House will vote on a 4-month extension of the debt ceiling, which seems to take the default issue off the table.  All eyes will then turn to the sequestration cuts and the continuing resolution. 

The CFPB has released a summary of the new broker / LO loan comp rules.  LO comp may not be based on any of the transaction’s terms of conditions. In other words, the interest rate does not matter, and LOs cannot be comped for steering a borrower to purchase title insurance from an affiliate. Pricing concessions are out as well. 

Finally, as a child of the 70s, I note with sadness the passing of Atari.  

Morning Report – Housing starts and bank earnings 01/17/13

Vital Statistics:

  Last Change Percent
S&P Futures  1471.6 6.0 0.41%
Eurostoxx Index 2710.7 8.2 0.30%
Oil (WTI) 94.8 0.6 0.59%
LIBOR 0.302 -0.001 -0.33%
US Dollar Index (DXY) 79.61 -0.198 -0.25%
10 Year Govt Bond Yield 1.87% 0.05%  
RPX Composite Real Estate Index 191.7 0.3  

Markets are higher after a good housing starts number and lower than expected unemployment claims. Bank of America and Citi both reported lower than expected 4Q earnings. Bonds and MBS are down.

Housing starts took a big jump upward in December, to an annualized pace of 954k, an annualized increase of over 100k. This is the highest level since June 2008. Multi-family starts accounted for about a third of the increase.  Building Permits increased at a 1.8% MOM and 29% YOY.  Remember, we have historically started 1.5 million units per year, and our 954k annual number basically represents the low points of all recessions since 1957 up to the post-bubble recession.

Chart:  Housing Starts


The CFPB is releasing new rules for servicers today.  It essentially eliminates the practice of “dual tracking” where a servicer works to mod a loan and simultaneously initiates foreclosure proceedings in case the mod doesn’t work out or the borrower fails to pay.  That might have the unintended consequence of less mods and more foreclosures.  Foreclosures cannot be initiated until the account is more than 120 days delinquent. This rule pre-empts state law, so timelines will get extended in non-judicial states. Servicers with less than 5,000 loans will be exempt.

Speaking of unintended consequences, the Fed is now worried about bubbles in farmland and junk bonds, the direct result of QE. Unwinding QE (it needs a name – Fed Exit – Fexit?) will be a touchy deal.  The buzzword for Fexit will be “convexity risk” Think Orange County in 1994 on steroids.  Not only will MBS bids fade because of interest rate volatility, they will also have to contend with the Fed dumping paper in an effort to shrink its balance sheet.  A 2014 recession is a distinct possibility. 

What it took to get a mortgage in 2012, according to Ellie Mae:  748 FICO, 23/34 DTI, 21% down.  Average interest rate 3.9%, average time to close, 48 days, 62% were refis. 

Morning Report – What a difference a year makes. 01/16/13

Vital Statistics:

  Last Change Percent
S&P Futures  1462.4 -2.8 -0.19%
Eurostoxx Index 2688.7 -12.9 -0.48%
Oil (WTI) 93.32 0.0 0.04%
LIBOR 0.303 0.000 0.00%
US Dollar Index (DXY) 79.86 0.085 0.11%
10 Year Govt Bond Yield 1.80% -0.03%  
RPX Composite Real Estate Index 191.7 0.3  

Markets are weaker this morning after the World Bank cut its global growth forecast.  Goldman and JP Morgan both reported better than expected earnings. Mortgage applications rose 15% last week and the CPI showed that inflation remains under control. Industrial production rose .3% and capacity utilization rose to 78.8%.  Bonds and MBS are up.

The National Association  Homebuilders Confidence index held at 47 in January, the highest level since April of 2006. A reading of 50 represents the point where builders view conditions as neutral. Conditions improved in all areas of the country, with the West performing the best, while the Midwest and Northeast performing the worst. This is the second sentiment report that has the “what a difference a year makes” theme.

The CoreLogic Home Price Index rose 7.4% YOY in Nov 2012. This is the largest gain since May of 2006.   Excluding distressed sales, home price increased nationally by 6.7%.  December’s gain is forecast to be down .5% MOM (reflecting the typical seasonal pattern) and will be up 8.4% YOY. Mark Fleming, the Chief Economist made a point about QM – “that the recently released Qualified Mortgage rules issued by the CFPB are not expected to significantly restrict credit availability relative to today.”  I am sure Cordray is breathing a sigh of relief on that one… the point of the QM rule was to expand credit.  

Bank of America is intent on growing the mortgage business again after a hasty retreat in 2011. Of course this meant they missed the mother of all refinancing booms. They exited the wholesale business and basically ceded the market leader position to Wells Fargo. It also signals that they believe the worst is behind them with respect to Countrywide. 

It is looking more and more like Republicans will not force a showdown on the debt ceiling (though “clean” debt ceiling increases have been rare in the past).  The polls aren’t with them and the politics aren’t there. Republicans will probably save spending cut demands for the sequester and the continuing resolution.

It looks like the case against Stevie Cohen has hit a wall.


Morning Report – The Debt Ceiling Dance 01/15/13

Vital Statistics:

  Last Change Percent
S&P Futures  1457.5 -6.8 -0.46%
Eurostoxx Index 2701.4 -13.7 -0.51%
Oil (WTI) 93.67 -0.5 -0.50%
LIBOR 0.303 -0.001 -0.33%
US Dollar Index (DXY) 79.65 0.158 0.20%
10 Year Govt Bond Yield 1.82% -0.02%  
RPX Composite Real Estate Index 191.9 0.0  

Futures are deteriorating on fears that Congress won’t find a way to raise the debt ceiling. Fitch ratings said that it would put the US credit rating under review for a downgrade if there is a delay in raising the debt ceiling. The Bernank weighed in on the debt ceiling at the University of Michigan yesterday. The producer price index showed inflation remains under control at the wholesale level and Dec retail sales were better than expected.  Bonds and MBS are up.

The Empire State Manufacturing Survey indicated that conditions for New York State manufacturers continued to decline at a modest pace. Roughly 20% of businesses surveyed expected to increase payroll, while the same number expect to decrease payroll. Capital Expenditures dropped again to its lowest level since 2009. That said, the outlook for 2013 remained mildly positive.

Lennar reported a profit of 56 cents a share for the 4th quarter and FY12 EPS of $3.11 a share.  Revenues were up 42% in Q4, and backlog was up 32%. Margins also increased.  The CEO noted that the housing recovery seemed to accelerate in Q4 as low mortgage rates, affordable home prices, lower foreclosures and a compelling rent vs own comparison drove the recovery.  

The CoreLogic Market Pulse showed that 2012 was better than expected for the housing market. They raise a good point though, that 2012 had no major economic shocks – no Japanese tsunami, no debt ceiling debate / downgrades, no major blow-ups of big financial entities. They characterize 2012 as “a year in recovery, but not one in which the country has actually recovered.”  They foresee further recovery next year, but note that supply has been constrained as many move-up buyers have been underwater.  As prices rise, those properties will be put back on the market. As the economy recovers, the first-time homebuyer will become in a better position to purchase these properties, which will provide the increased demand to meet the increased supply. 

The debt ceiling debate has been getting more confrontational, with the President using hostage-taking metaphors during his speech yesterday. Sen Pat Toomey (R-PA) has introduced a bill to avert default by requiring Treasury to prioritize payments (with interest, SS, and active duty military pay taking precedence) and allowing them to borrow just enough to cover those expenses if revenues aren’t enough. My personal belief is that Republicans know the politics aren’t there for a debt ceiling standoff, but they will accept the full sequestration cuts. The sequestration cuts were designed to never happen – the cuts were supposed to be unpalatable to both sides.  Much to the surprise of Democrats, Republicans are more comfortable with cutting defense than they thought, which means that the roughly $109 billion of spending in 2013 will get left on the cutting room floor. 

To put the sequestration into perspective:  the 2012 budget was $3.729 trillion.  The 2013 budget is $3.803 trillion.  The increase is roughly $74 billion.  In other words, the actual cut to government spending is $109 billion – $74 billion or about $35 billion.  $35 billion is 22 basis points of GDP. We are currently spending 24% of GDP, while the highest taxes as a percent of GDP have ever gotten in a touch over 20%, primarily during the equity bubble when capital gains tax receipts were huge. To get spending down to where we are able to balance the budget under the best of conditions, we would need to lop off $567B from 2012, or about 4% of GDP.  Republicans would be wise to give Obama what he wants on the debt ceiling and then force the Administration to explain why cutting spending by 22 basis points of GDP is somehow intolerable. Of course, the Administration has already telegraphed how it will fight this battle (terrorists will run wild, pollution will increase, airplane accidents will happen, we won’t be able to deal with natural disasters) so Republicans will be well advised to separate out the necessary functions of the government (basic safety net, FAA, FBI, FDA, etc) from the “nice-to-haves” like foreign aid to places like Egypt, agricultural subsidies, green energy subsidies, etc.

Morning Report – The week ahead 01/14/13

Vital Statistics:

  Last Change Percent
S&P Futures  1466.5 -0.7 -0.05%
Eurostoxx Index 2720.1 2.3 0.08%
Oil (WTI) 93.97 0.4 0.44%
LIBOR 0.304 0.000 0.00%
US Dollar Index (DXY) 79.6 0.041 0.05%
10 Year Govt Bond Yield 1.84% -0.02%  
RPX Composite Real Estate Index 191.9 0.4  

Markets are down small after disappointing iPhone data out of Apple. There is no economic data this morning, although the Bernank speaks at the University of Michigan after the close. This week will be heavy with bank earnings, with US Bancorp, JP Morgan, Goldman, Bank of America all reporting 4Q / full year.  Wed and Thurs are the most interesting economically, with Housing starts and Capacity utilization / Industrial Production.  Bonds are up 1/2 a point while MBS are up small.


David Blitzer of S&P discusses the outlook for housing in 2013. He thinks (a) housing is going to be an outsized contributor to GDP next year and (b) shadow inventory fears are overblown.


Different industry groups weigh in on the QM from the CFPB:


  • The MBA notes that cap on points is moronic when you are comparing different note rates
  • The Center for Responsible Lending complains that prime mortgages are protected under QM
  • The National Association of Federal Credit unions loves the special dispensation for them