Morning Report – Hedge funds betting on Fannie Mae 04/08/13

Vital Statistics:

  Last Change Percent
S&P Futures  1550.9 4.9 0.32%
Eurostoxx Index 2600.8 15.6 0.60%
Oil (WTI) 93.27 0.6 0.61%
LIBOR 0.279 0.000 0.00%
US Dollar Index (DXY) 82.61 0.111 0.13%
10 Year Govt Bond Yield 1.72% 0.01%  
Current Coupon Ginnie Mae TBA 106 0.1  
Current Coupon Fannie Mae TBA 104.3 0.0  
RPX Composite Real Estate Index 190.1 0.4  
BankRate 30 Year Fixed Rate Mortgage 3.54    

Markets are higher this morning on no real news. The Japanese Yen continues to fall, and is now approaching 100 yen to the dollar. The new program of quantitative easing in Japan is re-igniting the yen carry trade, except now the Japanese are borrowing yen to invest in US dollar assets. In case you missed it, Japan’s Nikkei 225 stock market index is up 52% since November. Incredible move. Japan’s QE program will mean incrementally lower rates on US long-dated Treasuries and MBS. Bonds and MBS are flat this morning.

Alcoa kicks off Q1 earnings season after the close today. We will get JP Morgan and Wells Fargo earnings on Thursday before the open.

Friday’s lousy jobs report probably means that any talk of ending QE this summer is probably over. After 3 consecutive economic slumps over the summer months, the Fed is going to stay aggressive. Chicago Fed President Charles Evans said “I’m going to have a lot more confidence if I begin to see indications that growth is well above trend and its going to be sustainable.” The Fed is going to be wary of reducing stimulus given that the fiscal policy has tightened a little bit.

Fannie Mae’s surprise profit has investors re-thinking the theory that they will be euthanized. Hedge funds are jumping into the preferred stock, which was issued in spring of 2008 as Fannie Mae was circling the drain before becoming nationalized. The 8.25% prefs have a $25 face value and were trading at $4.81 on Friday. All of this is predicated on the idea that Fannie Mae will be able to pay back the government. Once that happens, Fannie will restructure, and the bet is that there will be a place in the capital structure for the prefs. Risky bet, obviously, but big upside too.

Morning Report – Dismal Jobs Report 04/05/13

Vital Statistics:

  Last Change Percent
S&P Futures  1537.5 -17.0 -1.09%
Eurostoxx Index 2590.5 -30.9 -1.18%
Oil (WTI) 92.26 -1.0 -1.07%
LIBOR 0.279 -0.001 -0.36%
US Dollar Index (DXY) 82.43 -0.245 -0.30%
10 Year Govt Bond Yield 1.70% -0.06%  
Current Coupon Ginnie Mae TBA 105.8 0.5  
Current Coupon Fannie Mae TBA 104.4 0.4  
RPX Composite Real Estate Index 189.7 0.3  
BankRate 30 Year Fixed Rate Mortgage 3.59    

They’re beating the tape with the ugly stick after a dismal jobs report. The S&P 500 futures dropped from -4 to -16 on the report. The 10-year jumped on the news and is now yielding 1.7%.  It is hard to believe the 10 year was above 2% three weeks ago. MBS are rallying as well, but not as much as the 10-year. 

The March Employment Situation showed the economy added 88,000 jobs in March, well below the 190,000 estimate. February was revised upward to 268,000 from 236,000.  The unemployment rate ticked down to 7.6% from 7.7%, but that was due to a drop in the labor force participation rate, which dropped .2% from 63.5% to 63.3%. This means that the size of the labor pool dropped as more workers simply stopped looking for a job.  Long-term unemployed workers who are not actively looking for a job are not counted as part of the labor force. Wages were flat month-over-month and increased 2% year-over-year. 

The recent rally in bonds pours cold water on the “great rotation” theory –  the idea that 2013 would be the year when investors, particularly big institutional investors, change their target asset allocation and sell bonds to buy equities. So far, it seems like that investors are allocating money equally to both sectors – stock funds have taken in $79 billion while taxable bond funds have taken in $76 billion. Between the Bank of Japan’s QE program, which is driving funds to the US, the Fed’s QE program, and continued investor purchases of bonds, the expected 2013 bloodbath in the bond market may be held off for a while. Meanwhile, mortgage bankers are licking their chops thinking about another refi wave.  

Chart:  US Unemployment rate 1949-Present 


Morning Report – Return of the Yen Carry Trade 04/04/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1550.7

2.2

0.14%

Eurostoxx Index

2661.8

22.8

0.86%

Oil (WTI)

93.96

-0.5

-0.52%

LIBOR

0.28

-0.001

-0.25%

US Dollar Index (DXY)

83.19

0.469

0.57%

10 Year Govt Bond Yield

1.77%

-0.04%


Current Coupon Ginnie Mae TBA

104.9

0.1


Current Coupon Fannie Mae TBA

103.7

0.2


RPX Composite Real Estate Index

189.4

0.1


BankRate 30 Year Fixed Rate Mortgage

3.68


Markets are giving back some Japan-led gains after Initial Jobless Claims spiked to 385k from 357k. This was the holiday-shortened Easter week, so there is a seasonality adjustment there.  On a non-seasonally adjusted basis, they fell. Bonds and MBS are rallying, with the 10 year yield down to 1.77%.

The Bank of Japan outlined more aggressive monetary actions last night with their own version of quantitative easing. This pushed the Nikkei 225 stock market index up 2%, and caused a sizeable drop in the yen.  This explains the rally in US bonds as Japanese investors flee for the “high yielding” US treasury market.  Don’t laugh – the Japanese 40 year bond (the 2’s of 52) yields 1.34%.  The US 10-year at 1.77%, in the context of a depreciating yen, is reviving the yen carry trade. The Yen Carry Trade is when Japanese investors borrow funds at yen rates and invest in high-yielding sovereign debt. They benefit from the pickup in yield and any favorable currency movements. With the high quality Euro sovereigns yielding even lower than the US, we are the only game in town. Punch line – this will put downward pressure on mortgage rates in the US, at least at the margin.

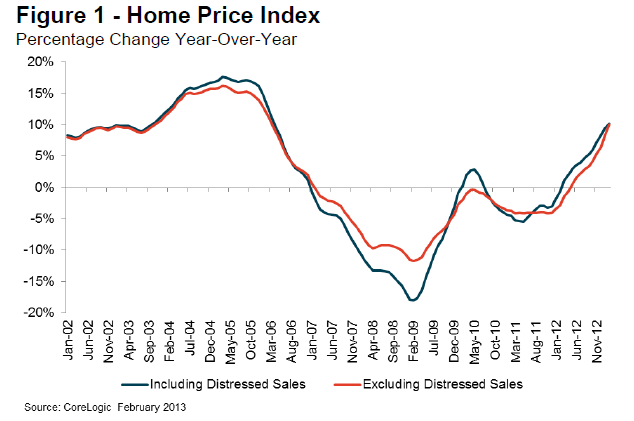
The CoreLogic Home Price Index increased 10.2% on a year-over-year basis in February, the highest increase since March of 2006.  It is the 12th consecutive monthly increase.  The gains were broad based, with 96% of their MSAs reporting gains.  California, Arizona, and Nevada all showed gains in the high teens.   They are forecasting a 2% month over month increase in March, or 12% year over year.

Chart:  CoreLogic Home Price Index 

Image

Hank Paulson, George Bush’s Secretary of Treasury, says that Fannie Mae’s new profitability shouldn’t deter the government from establishing a new platform for mortgage finance. He mentioned the Washington Post article that says the Administration is pushing banks to make home loans to people with weaker credit. Nominated to take over as Treasury Secretary just as the housing bubble was peaking, he can be forgiven for being a little gun-shy on re-inflating the bubble.

San Francisco Fed President John Williams said he is hopeful that “the economy has shifted into high gear” and that the Fed could begin slowing the purchases of Treasuries and MBS this summer, with a full exit by the end of the year.

Finally, you can hear my latest interview on Capital Markets Today, where I discuss real estate pricing, politics, and the economy.

Morning Report – the future of Fannie Mae 04/03/13

Vital Statistics:

S&P Futures  1564.7 0.3 0.02%
Eurostoxx Index 2665.2 -14.6 -0.54%
Oil (WTI) 96.64 -0.5 -0.57%
LIBOR 0.281 -0.001 -0.35%
US Dollar Index (DXY) 82.81 -0.117 -0.14%
10 Year Govt Bond Yield 1.85% -0.01%  
Current Coupon Ginnie Mae TBA 104.6 0.0  
Current Coupon Fannie Mae TBA 103.3 0.0  
RPX Composite Real Estate Index 189.3 -0.2  
BankRate 30 Year Fixed Rate Mortgage 3.69    

Markets are flat after a mixed ADP Employment report.  They forecast that the private sector added 158k jobs in March, below the 200k estimate.  February was revised upward, however to 237k. Mortgage Applications fell 4%.  Bonds and MBS are flat

The Obama administration is pushing banks to lend to borrowers with weaker credit, encouraging them to use FHA loans and to use more subjective judgment in determining whether to offer a loan. Of course the CFPB has already drawn a line in the sand with DTI. Housing officials are urging the Justice Department to provide assurances to banks that they will not face legal consequences if they comply and the borrowers subsequently default. Working against this initiative is that (a) the CFPB has drawn a bright line around the qualifying mortgage and (b) Ginnie Mae will flush an originator when they get 5% to 10% portfolio delinquencies. 

On the other hand, credit IS easing, especially for those who had short sales or foreclosures during the housing bust. Of the 7 million borrowers who had a foreclosure or a short sale, about 1 million are eligible for an FHA mortgage. Second, the return of the private label market (however small) will allow borrowers who don’t fit in the government bucket or the super high quality jumbo bucket to get financing.

Fannie Mae’s record profit has some questioning the future of the housing finance. According to the Administration’s White Paper, the intention seemed to be that the government would euthanize Fan and Fred and replace them with an entity that would act as a re-insurer. However, with more pressing issues facing the Administration, dealing with the GSEs has taken a back seat. In the interim, they are improving their balance sheets and have paid back nearly half of what they owe to the government. And with the stock approaching $1.00, the 4.6 billion shares owned by the government start to become significant. It will become harder to kill the company when the stock is worth some money.  That is obviously what the market has figured out, as the stock has tripled since Fannie announced they will be profitable nearly 3 weeks ago.

Chart:  Fannie Mae Stock Price:


Morning Report – Fannie Mae posts record profit 04/02/13

Vital Statistics:

  Last Change Percent
S&P Futures  1562.2 6.3 0.40%
Eurostoxx Index 2651.8 27.7 1.06%
Oil (WTI) 97.01 -0.1 -0.06%
LIBOR 0.282 -0.001 -0.18%
US Dollar Index (DXY) 82.75 0.016 0.02%
10 Year Govt Bond Yield 1.85% 0.01%  
Current Coupon Ginnie Mae TBA 104.6 0.0  
Current Coupon Fannie Mae TBA 103.3 -0.1  
RPX Composite Real Estate Index 189.5 -1.1  
BankRate 30 Year Fixed Rate Mortgage 3.68    

Markets are higher after Europe returned from a 4 day weekend. Italian sovereign yields are dropping, which is easing concerns about the Cyprus situation. Later this morning, we will get the ISM New York, factory orders and vehicle sales. Bonds and MBS are down small.

Fannie Mae just reported the largest net income in company history.  Good thing they didn’t release this yesterday or nobody would have believed it. They reported net income of $17.2 billion for 2012 and $7.6 billion in the 4th quarter. The refi boom of 2012 has certainly helped them, along with a drop in delinquencies, increasing home prices, and higher sales of Fannie Mae-owned properties. They still owe Treasury $85 billion. Fannie Mae stock has rallied from 30 cents a share two weeks ago to 80 cents a share as of yesterday on reports they will be profitable. The stock is trading up a nickel on low volume pre-market. Every dime the stock increases is roughly half a billion dollars in the US government’s coffers.

The Consumer Financial Protection Bureau has a new one-stop shopping site for financial gripes. They do not verify the facts of the complaints, but they give the company a chance to respond before they put it on their site. If you had ever been mad at your bank and wanted to create a http://www.thiscompanysucks.com website, well, there ya go.

Mohammed El-Arian says that the Cyprus situation is not fixed, just temporarily stabilized. Even if it doesn’t become a systemic problem (read: spread to Italy and Spain) it still could create a systemic threat if enough peripheral countries have issues. The EU seems to be against an Iceland-style fix, where Cyprus leaves the EU and devalues its currency.

Morning Report – Return of the Wealth Effect 04/01/13

Vital Statistics:

  Last Change Percent
S&P Futures  1562.4 -0.3 -0.02%
Eurostoxx Index 2624.0 11.6 0.44%
Oil (WTI) 96.53 -0.7 -0.72%
LIBOR 0.283 -0.001 -0.35%
US Dollar Index (DXY) 82.94 -0.032 -0.04%
10 Year Govt Bond Yield 1.88% 0.03%  
Current Coupon Ginnie Mae TBA 104.4 -0.2  
Current Coupon Fannie Mae TBA 103 -0.2  
RPX Composite Real Estate Index 190.5 -0.3  
BankRate 30 Year Fixed Rate Mortgage 3.67    

Markets are flat this morning as most European markets are closed for the Easter Holiday. We are kind on a lull period until next Monday when Alcoa kicks off earnings season. Bonds and MBS are down small.

The Markit U.S. Preliminary March Purchasing Managers Index rose to 54.9 from 54.3 in February, indicating that the economy is expanding at a faster rate.  Most indicators (new orders, employment, backlog) indicated the economy was expanding and accelerating. The Markit PMI is different than the more widely followed Institute of Supply Management Survey, which uses different weightings. 

NPR has a good backgrounder on how strength in housing feeds other sectors of the economy. Punch line:  the wealth effect, which was given up for dead in 2008 has returned. As home equity grows, people start spending again. 

The Feds are getting closer to Stevie Cohen. They have arrested Micheal Steinberg, one of Cohen’s senior lieutenants, who was implicated in insider trading in Nvidia and Dell. 

Morning Report – Undiversified Bond Investment? 03/28/13

Vital Statistics:

  Last Change Percent
S&P Futures  1558.1 1.3 0.08%
Eurostoxx Index 2633.5 21.0 0.80%
Oil (WTI) 96.39 -0.2 -0.20%
LIBOR 0.283 -0.001 -0.35%
US Dollar Index (DXY) 83.07 -0.148 -0.18%
10 Year Govt Bond Yield 1.85% 0.01%  
RPX Composite Real Estate Index 190.5 -0.3  

Markets are flattish on the last trading day of the quarter. 4Q GDP was revised upward from + .1% to + .4%. Personal consumption was revised downward as well.  Initial Jobless Claims rose last week to 357k. Bonds and MBS are flat.

The bond markets close at 1:00 pm EST today. Expect very little action today as traders will probably flatten positions ahead of quarter end.

The Office of Comptroller of the Currency has released the 4Q mortgage performance metrics. 89.4% of all mortgages are current, up from 88.6% last year. Delinquencies and foreclosures are down as the pipeline gets cleared and real estate prices start rebounding. More and more servicers are turning to mods as opposed to foreclosure initiations. The recidivism rate on these mods is around 17%.

The Private Label Securitization market is returning faster than people thought. Prior to this year, the only deals were the occasional Redwood Trust jumbo deal.  JP Morgan recently announced a deal, and now Springleaf plans a $1 billion subprime deal. The palette of products originators can offer is expanding in a big way.

FHFA has made mods easier to do on delinquent mortgages – anyone who is more than 90 days delinquent is automatically eligible for a loan mod. Borrowers do not have to show a financial hardship any more. This will only apply to Fan and Fred loans, and mods will be rate / term, not principal reductions. So this begs the question:  Why won’t everyone stop paying their mortgage in order to get a mod?  FHFA said they would use existing “screening measures to prevent strategic defaulters.”  Whatever that means. 

Is your house an undiversified bond investment? Was house price appreciation driven by falling interest rates? And does that mean that when rates start rising house prices will fall again? I would point out that interest rates aren’t the only factors affecting home prices – population growth, incomes, the availability of credit, and even global capital flows play a role. He does have a point, which is that a rapid rise in home prices like we saw from the early 90’s to 2007 is unlikely to be repeated given that we won’t have the tailwind of falling interest rates to increase affordability. That said, low interest rates can last a long time – from the end of WWI to the mid 60’s, short-term rates were 5% or lower. From 1932 to the mid 50’s, short term rates were under 2.5%.  I would also point out that real estate prices increased during the 1970s, even as short term rates moved up to 15%. 

Morning Report – Are we back in a real estate bubble? 03/27/13

Vital Statistics

  Last Change Percent
S&P Futures  1550.7 -6.5 -0.42%
Eurostoxx Index 2597.6 -43.6 -1.65%
Oil (WTI) 95.95 -0.4 -0.40%
LIBOR 0.284 0.000 0.00%
US Dollar Index (DXY) 83.21 0.328 0.40%
10 Year Govt Bond Yield 1.86% -0.05%  
RPX Composite Real Estate Index 190.8 -0.2  

Markets are lower this morning as Euro sovereign yields widen on the Cyprus situation. Mortgage applications rose 7.7% last week. This is the last full trading day of the week (Thurs is a half day), so volume should start to dry up as traders square their books for quarter-end and leave for the long weekend.  Bonds and MBS are up on the flight to safety trade.

We will have some Fed-speak today with Rosengren of Boston, Pianalto of Cleveland, and Kocherlakota speaking at various events during lunch. Hints about QE could move MBS, so watch your locks.

Consumer confidence fell in March to 57.9 from 61.4 a month earlier. The report blames Washington for the decrease. You certainly wouldn’t guess it from watching the stock market indices.  It will be interesting to see how the spending numbers shake out. 

New Home sales fell 4.6% MOM in February, but were up 12.3 YOY to a seasonally adjusted annual rate of 411,000 units. The median sales price was $246,800, an increase of 3% YOY. There definitely seems to be a bifurcation of the market, where existing homes are rising at a high single digit rate, yet the new home market is experiencing more modest price increases. Investor activity is probably driving the difference, as professional investors are purchasing distressed property for rentals, while new home sales are driven by actual homeowners. Volume is picking up, with the  sales in Feb up 13% from last summer. 

Bob Schiller pointed out that the latest housing data should be approached with caution. He points out that markets like Phoenix and Las Vegas are “frothy” and says that the recovery may even be a bubble. FWIW, I disagree that we are in another bubble – bubbles are psychological phenomenons that start with the view that “this time is different” and that the asset in question can only go up. That was the view of residential real estate in 2006.  It isn’t now. Our grandkids may experience another real estate bubble, but we won’t. Schiller believes that it will take 40 years for home prices to rise to pre-2007 levels. Yes, that is an eye-opening forecast, but he is talking about inflation-adjusted numbers. 

The government wants to impose a surcharge (through higher capital requirements) for the too big to fail banks. This will undoubtedly be another impetus for the big banks to break up voluntarily. 

Morning Report – Case-Schiller 03/26/13

Vital Statistics:

  Last Change Percent
S&P Futures  1550.2 3.3 0.21%
Eurostoxx Index 2637.9 -11.4 -0.43%
Oil (WTI) 95.58 0.8 0.81%
LIBOR 0.284 0.001 0.18%
US Dollar Index (DXY) 82.87 0.039 0.05%
10 Year Govt Bond Yield 1.93% 0.01%  
RPX Composite Real Estate Index 191 0.2  

Markets are higher this morning after a positive durable goods report, which showed orders increased 5.7% in Feb. January was revised higher.  Bonds and MBS are down small.

The S&P / Case-Schiller index of home values increased 8.1% YOY , better than the 7.9% estimate. The month on month index rose as well.  For the first time since the housing bust, we have not seen a seasonal drop in house prices.  The New York MSA finally reported positive returns. House prices are back to their Autumn 2003 levels.

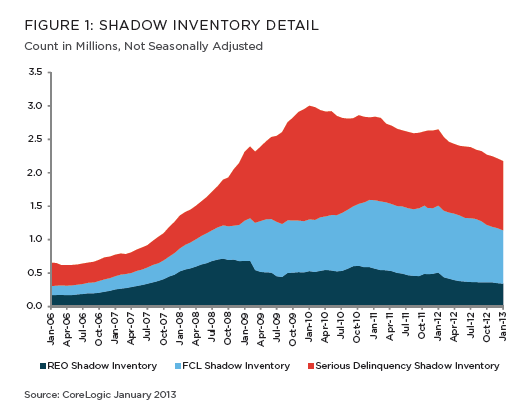
CoreLogic reported that shadow inventory (the number of homes that are seriously delinquent, in foreclosure, or REO, but not listed on the MLS) is down 28% from its peak three years ago when it stood at  3 million units. The current 2.2 MM units is down 18% from last year and represents 9 month supply.FL, NY, CA, NJ, and IL account for half of the shadow inventory. 

The Cyprus rescue, while small in actual dollar terms, may have reverberations all across the euro zone. Under the rescue plan, senior Cypriot bond holders will take haircuts and uninsured depositors will be wiped out. This sets a precedent – that all stakeholders can be targeted – which will probably cause even bigger outflows the next time another Euro country gets in trouble. Given that Cyprus instituted capital controls so that investors can’t take money out means that the exit door will be very narrow the next time someone gets in trouble.

Morning Report – Blackstone vs the first time home buyer 03/25/13

Vital Statistics:

  Last Change Percent
S&P Futures  1557.4 5.4 0.35%
Eurostoxx Index 2711.9 30.2 1.13%
Oil (WTI) 94.42 0.7 0.76%
LIBOR 0.283 -0.002 -0.53%
US Dollar Index (DXY) 82.52 0.147 0.18%
10 Year Govt Bond Yield 1.96% 0.04%  
RPX Composite Real Estate Index 190.7 -0.5  

Markets are higher after Cyprus agreed to shut its second-largest bank in exchange for a 10 billion euro bailout. Of course Russian money will flee the country, and Russian banking was the only thing keeping that economy afloat. So, I am sure we will be revisiting this issue in the near future. Bonds and MBS are down on the “risk-on” trade.

This is a short week, so expect activity to wind down as traders square their books for quarter end, and many take Thursday off.  In economic data, we have durable goods, new home sales, and Case-Schiller tomorrow. We will get the final revision to 4Q GDP on Thursday. 

The Chicago Fed National Activity Index came in at +44 in February from -.49 in January.  This is a broad-based index that focuses on 85 different indicators of economic activity. Since the individual monthly indices can be volatile, you want to focus on the 3 month moving average, which has been above zero (absolute historical trend) for the past 4 months. The main takeaway from the index is that we are performing slightly above trend, and that inflation is well-contained. 

The Wall Street Journal has an article this morning talking about how professional investors are impacting the real estate market. In hot markets like Orange County, professional investors make up about 22% of all sales. During the bubble years, they were about 10%.  They are having the effect of taking affordable housing off the market. This has had the added effect of improving the quality of neighborhoods as they have taken the abandoned homes off the market and maintaining them. Blackstone has bought $3.5 billion worth of homes so far and is buying more than $100 million a week. Of course the loser in all of this is the first time homebuyer, who already has to deal with a lousy job market and a tight credit market, and now faces bidding wars for a starter home from firms like Colony and Blackstone. These investors may find that being in the rental business is a lot harder than it looks and could turn net sellers are rental yields fall and home prices increase.